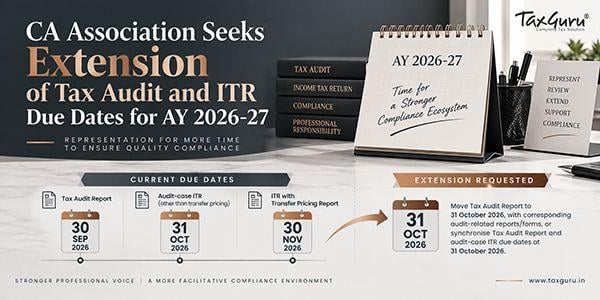
Summary: The Chandigarh Chartered Accountants Taxation Association has submitted a representation dated 14 September 2026 to the Union Minister of Finance seeking extension of the due dates for Tax Audit Reports, Forms 10B/10BB and Income-tax Returns for AY 2026-27. The Association welcomes the separate 31 August 2026 due date for business taxpayers not liable to audit but submits that the revised calendar has concentrated audit-related work into the August-September period. It highlights the progressive release and continued updating of ITR utilities, with ITR-3, ITR-5, ITR-7 and ITR-6 utilities becoming available at different times and several being updated as late as 1 September 2026. The representation also identifies technical difficulties involving AIS, TIS, Form 26AS, portal access, data retrieval, validation, digital signatures and uploading, together with overlapping GST, TDS/TCS, MCA and statutory audit compliances. It further refers to the revised ICAI Guidance Note on Financial Statements of Non-Corporate Entities and its phased implementation, stating that the revised presentation, disclosure and classification requirements require additional time and consequently affect the tax-audit process. The Association relies on the history of extensions to the 30 September Tax Audit due date in earlier assessment years and submits that the recurring nature of these difficulties is structural rather than exceptional. It requests extension of the Tax Audit Report due date from 30 September 2026 to 31 October 2026, corresponding extension of Forms 10B, 10BB and other linked audit reports, and consequential extension of the audit-case Income-tax Return due date so that a reasonable working interval remains available after furnishing the Tax Audit Report.
CHANDIGARH CHARTERED ACCOUNTANTS TAXATION ASSOCIATION
Ref: CCATAX/2026-27/REP/01 | Dated: 14 September 2026
To,
The Hon’ble Union Minister of Finance
Smt. Nirmala Sitharaman
Ministry of Finance, Government of India
North Block, New Delhi -110001
Subject: Request for extension of the due date for Tax Audit Reports, Forms 10B/10BB and Income-tax Returns for AY 2026-27
Respected Madam,
The Chandigarh Chartered Accountants Taxation Association, representing chartered accountants and the taxpayer community of the region, respectfully places before your good office this representation seeking an extension of the due date for furnishing Tax Audit Reports (TAR), Forms 10B/10BB and other audit-related reports, together with consequential relief in the filing of Income-tax Returns for AY 2026-27.
At the outset, we sincerely welcome the taxpayer-friendly measure of providing a separate due date of 31 August 2026 for business taxpayers not liable to audit, in place of the earlier common date of 31 July. However, the revised calendar has concentrated audit-related work into a narrow August-September window, placing audit taxpayers and the professionals serving them under considerable time pressure.
The present due dates for AY 2026-27 are as under:
| Particulars | Due Date (AY 2026-27) |
|---|---|
| Business | 31August 2026 |
| Tax Audit Report & other audit reports/forms | 31 October 2026 |
| Audit ITR | 30 November 2026 |
| ITR with TP Report | 30 November 2026 |
The specified date of 30 September 2026 applies not only to the Tax Audit Report (Forms 3CA/3CB along with Form 3CD) but also to Forms 10B and 10BB and other audit reports/statements whose due date is linked to the specified date under the Income-tax Act and Rules.
Consequently, the effective working period between furnishing the Tax Audit Report on 30 September 2026 and filing the corresponding audit-case Income-tax Return on 31 October 2026 is effectively limited to one month, even as the volume and complexity of audit and reporting work have risen sharply.
DELAYED AND CONTINUING UPDATES TO ITR FORMS AND UTILITIES
The release of the ITR utilities for AY 2026-27 was substantially delayed, particularly in respect of taxpayers falling under audit categories. As per the Income-tax Department’s own e-filing portal records:
| Utility / Category | First Released | Latest Update |
|---|---|---|
| Common Offline Utility (ITR-1 to ITR-4) | 20 May 2026 | Version 1.2.4 – 2 September 2026 |
| ITR-3 Excel Utility | 18 June 2026 | Version 1.3 – 1 September 2026 |
| ITR-5 Excel Utility | 07 July 2026 | Version 1.4 – 1 September 2026 |
| ITR-7 Excel Utility | 09 July 2026 | Version 1.2 – 1 September 2026 |
| ITR-6 Excel Utility | 04 August 2026 | Version 1.0 – 4 August 2026 |
These dates demonstrate that the utilities required for different categories of taxpayers, including audit cases, became available progressively and, in several cases, continued to be revised very close to the statutory compliance season. Since the Tax Audit Report and the Income-tax Return are intrinsically interconnected, finalisation of audit disclosures depends upon the corresponding return forms, schemas, validations and utilities being available and reasonably stable. This substantially reduces the effective time available for finalisation, reconciliation, review and error-free filing.
TECHNICAL DIFFICULTIES ON THE E-FILING PORTAL
Taxpayers and professionals continue to face practical difficulties in accessing, downloading and reconciling information available through the Annual Information Statement (AIS), Taxpayer Information Summary (TIS) and Form 26AS, along with issues relating to login, data retrieval, validation, digital signatures and uploading of forms. In audit cases, where the correctness of every disclosure must be independently verified, such interruptions have a cascading effect on the timely completion of the audit.
OVERLAPPING STATUTORY COMPLIANCES
The August-October period is already crowded with GST, TDS/TCS and MCA filings, statutory audits and finalisation of accounts. This leaves limited contiguous time to complete tax audits with the care and diligence they require.
REVISED FINANCIAL REPORTING FOR NON-CORPORATE ENTITIES
ICAI has introduced the Guidance Note on Financial Statements of Non-Corporate Entities, being implemented in a phased manner. As per the ICAI announcement dated 31 March 2026, Phase I applies to accounting periods beginning on or after 1 April 2025 for entities with turnover exceeding 5 crore. The revised formats, disclosures and presentation requirements call for additional time for preparation, review and finalisation of financial statements, which consequently affects the tax-audit process.
PRECEDENT – A CONSISTENT TRACK RECORD OF EXTENSIONS
Extension of the 30 September due date for furnishing the Tax Audit Report, on account of genuine practical difficulties, is well established. In eight of the last nine years the due date has been extended following representations from professional bodies:
| AY | Original Due Date | Final Extended Date | Remarks |
|---|---|---|---|
| 2017-18 | 30 Sep 2017 | 07 Nov 2017 | Two extensions by CBDT |
| 2018-19 | 30 Sep 2018 | 31 Oct 2018 | Two extensions by CBDT |
| 2019-20 | 30 Sep 2019 | 31 Oct 2019 | Extension by CBDT |
| 2020-21 | 30 Sep 2020 | 15 Jan 2021 | COVID-19 – multiple extensions |
| 2021-22 | 30 Sep 2021 | 15 Feb 2022 | COVID-19 – multiple extensions |
| 2022-23 | 30 Sep 2022 | 07 Oct 2022 | e-filing portal difficulties |
| 2023-24 | 30 Sep 2023 | 30 Sep 2023 | Forms 10B/10BB extended only |
| 2024-25 | 30 Sep 2024 | 07 Oct 2024 | Extension by CBDT |
| 2025-26 | 30 Sep 2025 | 10 Nov 2025 | Two extensions by CBDT |
| 2026-27 | 30 Sep 2026 | — | Present position – relief sought |
The above extensions were generally not confined to the Tax Audit Report alone; the corresponding audit-case Income-tax Return due dates (and, where applicable, related audit reports and forms) were revised in tandem. For AY 2025-26, for instance, the Tax Audit Report was extended in two stages to 10 November 2025, while the audit-case Income-tax Return due date was moved to 10 December 2025. Even setting aside the two COVID-affected years, six of the remaining seven cycles saw an extension — underscoring that the difficulty is recurrent and structural rather than exceptional. The grounds in the current year are materially similar, and consistent relief would be equitable.
OUR REQUEST
In view of the genuine difficulties set out above, we earnestly request your good office to kindly:
1. Extend the due date for furnishing the Tax Audit Report (Forms 3CA/3CB along with Form 3CD) from 30 September 2026 to 31 October 2026;
2. Correspondingly extend Forms 10B, 10BB and other audit reports/statements linked to the specified date to 31 October 2026; and
3. Grant a consequential extension of the due date for filing the corresponding audit-case Income-tax Returns, so that a reasonable working interval remains available after furnishing the Tax Audit Report.
Beyond the current year, we respectfully submit that the recurrence of these difficulties points to a structural rather than a one-time issue. A durable framework — a single, realistic common due date for audit reports and audit-case returns, timely and sequenced release of ITR forms and utilities well ahead of the season, and transparent readiness norms for the e-filing system — would greatly reduce the need for year-end extensions and lend certainty to taxpayers and professionals alike.
Tax audit is a substantive statutory responsibility and not a mere procedural formality: the auditor is required to examine the books of account and make numerous factual and statutory disclosures in Form 3CD that carry significant consequences for both the taxpayer and the Revenue. We wish to emphasise that this request seeks no deferral of tax payment and confers no undue benefit. It is intended solely to enable taxpayers and professionals to discharge their statutory obligations accurately, completely and after proper audit, reconciliation and verification — which is ultimately in the interest of the Revenue as much as the taxpayer.
Considering the delayed release of ITR forms and utilities and the enhanced compliance requirements introduced this year, we request that this representation be considered sympathetically and the necessary extension granted at the earliest.
Thanking you,
Yours faithfully,
For Chandigarh Chartered Accountants Taxation Association
CA/CMA Dr Ba!winder Singh
President
CA Manoj Kohli
General Secretary