
Serajuddin And Co. Vs DCIT/ACIT (ITAT Cuttack)
Telegram Talk Is Not Taxable Truth: Third-Party Chat, Without Corroboration or Confrontation, Cannot Justify Addition in Assessee’s Hands
A casual digital conversation may generate suspicion, but suspicion cannot be converted into taxable income without establishing its connection with the assessee. The Cuttack Bench of the ITAT deleted an enhancement of ₹3.50 crore made by the CIT(A) solely on the basis of a Telegram chat found on the mobile phone of a third party, particularly when neither the assessee nor any of its partners was a participant in the conversation.
During a search operation, the backup of the mobile phone belonging to Shri Mofazzulur Rahman was taken by the Department. A Telegram conversation between him and Shri Meraj Yusha allegedly referred to amounts connected with Serajuddin & Co. According to the Department, the conversation suggested that the assessee had received cash back of ₹3 crore from Sarosh Aliza Mining and ₹50 lakh from Modern Mining Pvt. Ltd., subsequently known as K.K. Resources Pvt. Ltd.
The Department sought to rely upon this conversation to contend that contractual payments made by the assessee to these entities were bogus and that a part of the payments had been returned to the assessee in cash.
Significantly, the AO was already aware of this digital material while completing the earlier assessment u/s 153A r.w.s. 143(3). After examining the issue, the AO had not made any addition on this account. Nevertheless, the CIT(A), while deciding the assessee’s appeal, issued a notice of enhancement and ultimately enhanced the income by ₹3.50 crore on the basis of the same Telegram conversation.
The assessee pointed out that the chat was neither found on its premises nor recovered from the mobile phone of any of its partners. The conversation was between two independent persons, namely Shri Meraj Yusha and Shri Mofazzulur Rahman. Neither of them was a partner of the assessee-firm.
More importantly, although both persons were available during the search proceedings, the Department did not record their statements concerning the Telegram message. No attempt was made to ascertain the nature of the amounts mentioned in the conversation, the context in which the message was exchanged or whether the alleged transaction had actually taken place. The message itself did not categorically state that cash had been paid back to the assessee.
The Tribunal observed that the message was found on the phone of Shri Mofazzulur Rahman and bore the name of Shri Meraj Yusha. It did not specifically speak about any cash transaction. Thus, at the highest, the material merely showed that two persons were talking about certain transactions having some reference to Serajuddin & Co.
If the Department considered the chat incriminating, the obvious course was to examine the persons who had actually exchanged the messages. However, no statement was recorded from either of them, despite their availability during the search. The Department also failed to undertake any independent investigation or bring any corroborative evidence establishing the alleged cash-back arrangement.
The Tribunal emphasised that the evidence was not found in the possession or control of the assessee or any of its partners. The persons who exchanged the messages were outsiders. Consequently, the contents of their conversation could not automatically be attributed to the assessee without first verifying the transaction with the persons directly connected with the message.
The Tribunal further noticed that the AO had knowledge of this very material during the original assessment but had not proposed any addition. Even the search team had not considered it necessary to conduct an enquiry regarding the message. In such circumstances, making an addition subsequently in the hands of the assessee, based exclusively upon an unverified third-party conversation, would amount to a travesty of justice.
The ITAT also remarked that the Income-tax Act does not permit such third-party chats to be treated, by themselves, as conclusive evidence against an assessee. Since the alleged transactions were not demonstrated to belong to the assessee and the chat was neither corroborated nor verified, the Tribunal found no justification for sustaining the enhancement. The ₹3.50 crore addition was accordingly deleted, and the assessee’s appeal was allowed.
Author’s Comments
The decision draws an important distinction between the admissibility of electronic material as a starting point for investigation and its sufficiency for making an addition. A Telegram, WhatsApp or other digital message may undoubtedly give the Department a lead. But a lead is not proof.
Where the conversation is between third parties, the Department must establish the identity of the participants, examine them, ascertain the context of the conversation, trace the movement of money and provide the assessee an effective opportunity to rebut the material. A digital chat cannot become a substitute for investigation merely because the assessee’s name appears somewhere in the conversation.
The wider proposition in the order that the Act does not permit chats to be treated as evidence should be understood in the factual context. The ruling does not mean that electronic conversations can never be relied upon. It means that an unverified, ambiguous and uncorroborated third-party chat cannot, standing alone, sustain an addition. A message may raise a question; it cannot supply the answer all by itself.
FULL TEXT OF THE JUDGMENT/ORDER OF ITAT, CUTTACK BENCH
This is an appeal filed by the assessee against the order of the CIT(A)-2, Bhubaneswar [hereinafter referred to as the ‘CIT(A)’] in appeal no.CIT(A), Bhubaneswar-2/10137/2020-21 dated 10.03.2026 for the assessment year 2021-22.
2. Shri Sunil Mishra, AR appeared on behalf of the assessee and Shri Jeetendra Kumar, CIT D.R. represented on behalf of the revenue.
3. It was submitted by the ld. AR that the only issue in this appeal is against the enhancement made by the ld. CIT(A) in respect of 3,50,00,000/- on account of a Telegram chat with Serajuddin & Co. and the screenshot of the chart is extracted by the ld. CIT(A) at page 36 of his order which reads as follows:
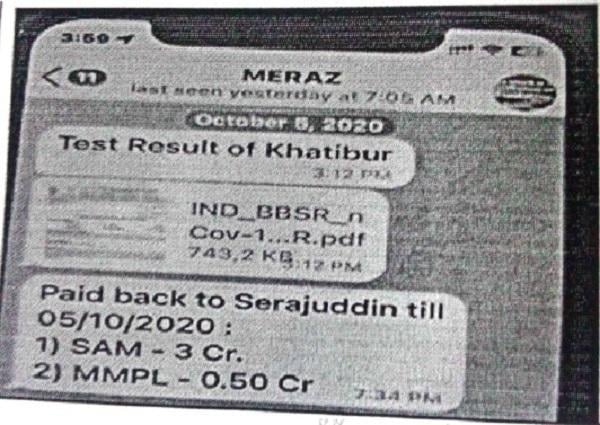 3.1 It was the submission that the ld. CIT(A) has categorically recorded in para 9.6 of his order that the Assessing Officer has pointed out back up of the mobile of Shir Mofazzulur Rahman was taken during the search operation with identification mark. He stated that there was telegram chat with Shri Meraj Yusha wherein there are evidences of Serajuddin & Co. receiving cash backs from the party Sarosh Aliza Minning. The Assessing Officer stated that the assessee, Serajuddin & Co., has received cash back of Rs.3 crores from SAM and Rs.0.5 crore from Modern Mining Pvt. Ltd. This chart was used to support the argument that the contractual payment made to Sarosh Aliza Mining and Modern Mining Pvt. Ltd. (now K.K. Resources Pvt. Ltd.) was bogus as cash was received back by the assessee from them. It was the submission that the ld. CIT(A) in para 9.7 has categorically given a finding that the issue has already been verified in the earlier assessment proceedings u/s 153A r.w.s. 143(3) and no additions have been made. Consequently, the ld. CIT(A) in para 10.1 has issued an enhancement notice to the assessee and the assessee has categorically mentioned that the Telegram message was from Shri Meraj Yusha to Shri Mofazzulur Rahman and in para 10.2, the message does not mention any cash paid back to Serajuddin & Co. It was the submission that there was no statement recorded from the said parties who were very much present during the course of search. It was the submission that they were also not partners of the Serajuddin & Co. It was the submission that the addition has been made merely on suspicion.
4. In reply, the ld. CIT-DR submitted that the date of the message is 05.10.2020 and the said message also clearly talks of paying back to Serajuddin & Co. till 05.10.2020. It was the submission that the assessee has not provided any proof to show that these transactions were recorded in the books of account of the assessee. It was the submission that the addition as made by the ld. CIT(A) is liable to be confirmed.
5. We have considered the rival submissions. The impugned assessment year is 2021-22. It is also admitted fact that the message was found on the phone of Shri Mofazzulur Rahman. The message also clearly shows that the name as Meraj Yusha. The message does not talk of any cash. It is not anymore in dispute that Meraj Yusha and Mofazzallur Rahman were present during the course of search and no statements were recorded from either of the party in respect of said message. This clearly shows that two persons were talking about some transactions in relation to Serajuddin & Co. and the assessee is being questioned in regard to the message found from somebody else. These evidences were not found in the hands of Serajuddin & Co. or the partners of the firm. Obviously, this transaction is to be verified with the persons connected with the message. This has also not done. When the Assessing Officer in the course of original assessment was in the knowledge of the said evidence and no addition has been proposed in the assessment and even the search party has not made any enquiry in regard to the said message, to now propose an addition in the hands of the assessee when such evidence has not been found in the hands of the assessee nor its partners would be a travesty of justice. It must also be mentioned here that the addition has been proposed only on a Telegram chat where the assessee nor its partners were involved and the Act does not permit such chats to be treated as evidence. Thus, we find no reason to confirm this enhancement of addition in so far as the transactions were not shown to belong to the assessee. In the circumstances, the addition as enhanced by the ld. CIT(A) stands deleted.
6. In the result, the appeal of the assessee is allowed.
Order pronounced in the open court on 10/09/2026.








