
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Additions for Unaccounted Sales Cannot Be Based on Mere Suspicion or Estimated Production Yield: SC
Chhattisgarh HC Deletes Income Tax Addition as Estimated Yield Was Based on Guesswork

Section 263 Revision Invalid as CIT Raised Issues Beyond Reassessment Scope: ITAT Delhi

ITAT Remands Section 69 Addition as Additional Evidence on PACS Transactions Required Verification

SC Upholds Pay Parity Relief as Juniors Drew Higher Salary Than Seniors After Departmental Exam

ITAT Upholds Section 263 Revision as AO Verified Expenses Only on Random Basis
Why Income Tax Notices Are Increasing in Property Transactions Below Circle Rate
Can a Homebuyer Be Taxed for Paying “On-Money” to a Builder?

Cash Withdrawn Earlier Cannot Become ‘Unexplained Cash’ on Re-Deposit: ITAT Bangalore
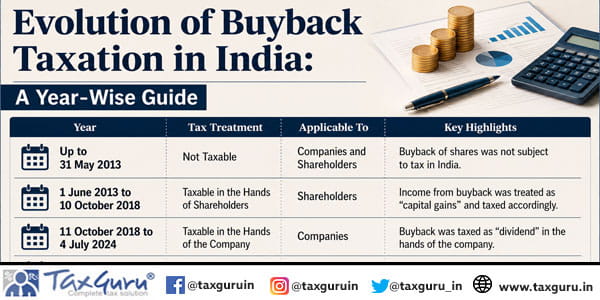
Evolution of Buyback Taxation in India: A Year-Wise Guide
ITAT Restores Appeal as Assessee Uploaded Replies in Wrong NFAC Window

Income Tax Return – Who should verify?

ITAT Rejects Bogus Purchase Allegation as AO Failed to Prove Discrepancies in Books
ITAT Allows Section 80IA Deduction Because JV Was Only a Pass-Through Entity
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

