
Muthumalai Murugan Trust Vs ITO (Exemptions) (ITAT Chennai)
Summary: The Income Tax Appellate Tribunal (ITAT), Chennai, allowed the appeal of Muthumalai Murugan Trust against the order dated 26 March 2026 of the Commissioner of Income Tax (Exemptions), Chennai, denying renewal of approval under Section 80G of the Income Tax Act, 1961. The assessee, a public charitable trust holding valid registration under Section 12A, had previously enjoyed approval under Section 80G for assessment years 2022-23 to 2026-27. It sought renewal from assessment year 2027-28, but the Commissioner rejected the application on the ground that the trust was established for religious and charitable purposes and was therefore ineligible for approval.
The assessee’s appeal was filed with a delay of 32 days. After examining the condonation petition and affidavit, the Tribunal accepted that reasonable and sufficient cause existed for the delay. Relying on the Supreme Court judgment in Collector, Land Acquisition Vs. MST. Katiji & Ors. (167 ITR 471), it condoned the delay and admitted the appeal.
On the merits, the assessee argued that its objects and activities had remained unchanged since the earlier approval. The authorised representative submitted that the Department had previously examined the trust’s objects and activities before granting approval and could not take a different stand at the renewal stage without any relevant change.
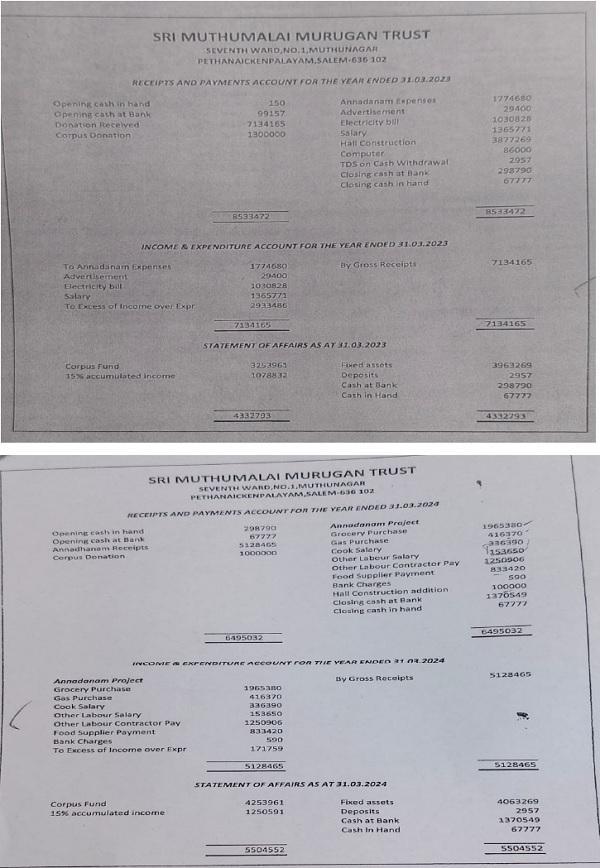
The Tribunal examined the financial statements for the years ended 31 March 2023, 31 March 2024 and 31 March 2025. It observed that the trust’s principal activity was Annadanam, namely providing meals free of cost to poor people. On the evidence considered, the Tribunal found that the assessee was not carrying on religious activities but was engaged in charitable activities through free food distribution.
The Tribunal held that rejection of Section 80G approval on the ground that the trust pursued religious-cum-charitable purposes was incorrect. It also took into account the earlier approval through assessment year 2026-27 and the absence of changes in the trust’s activities or objects. Accordingly, it directed the CIT(E) to allow approval under Section 80G in accordance with law. The assessee’s appeal was allowed by the order pronounced on 6 October 2026.
Assessee represented by: Mr. S.R. Srikrishna.
FULL TEXT OF THE ORDER OF ITAT CHENNAI
This appeal by the assessee is against the order of the Commissioner of Income Tax (Exemptions), Chennai (in short “CIT(E)”) dated 26.03.2026 denying approval u/s. 80G of the Income Tax Act, 1961 (in short “the Act”).
2. The assessee is a public charitable trust and is holding a valid registration u/s. 12A of the Act. The assessee made an application for renewal of a approval u/s. 80G of the Act from AY 2027-28 and an application in this regard was made on 26.03.2026. The said application was rejected on the ground that the assessee is established for religious and charitable purposes and therefore not eligible for approval u/s. 80G of the Act . The assessee is in appeal before the Tribunal against the order of the CIT(E).
3. There is a delay of 32 days in filing the appeal by the assessee. The assessee has filed condonation petition/affidavit stating the reasons for delay in filing the appeal. Having heard both the parties and perused the material on record, we are of the view that there is a reasonable and sufficient cause for the delay in filing the appeal before the Tribunal. Therefore, following the Hon’ble Supreme Court decision in the case of Collector, Land Acquisition Vs. MST.Katiji & Ors., (167 ITR 471) (SC), we condone the delay in filing the appeal and admit the appeal for adjudication.
4. We have heard the parties and perused the material available on record. The Ld. Authorized Representative (AR) of the assessee submitted that the assessee was given approval u/s. 80G of the Act from AY 2022-23 to 2026-27 and that since the approval there is no change to the objectives of the Trust. The Ld. AR further submitted that while granting earlier approval various details are called for with regard to the objects and the activities of the trust and that the approval was granted after due verification. Accordingly, the Ld. AR argued that the Department cannot take a different stand at the time of renewal of the registration u/s. 80G of the Act. We notice that from the perusal of financial statements of the assessee that the main activity of the assessee is providing Annadanam (meal on free of cost) to poor people. The relevant extract from the financial statements for year ending 31.03.2023, 31.03.2024 and 31.03.2025 are extracted hereinbelow:
–
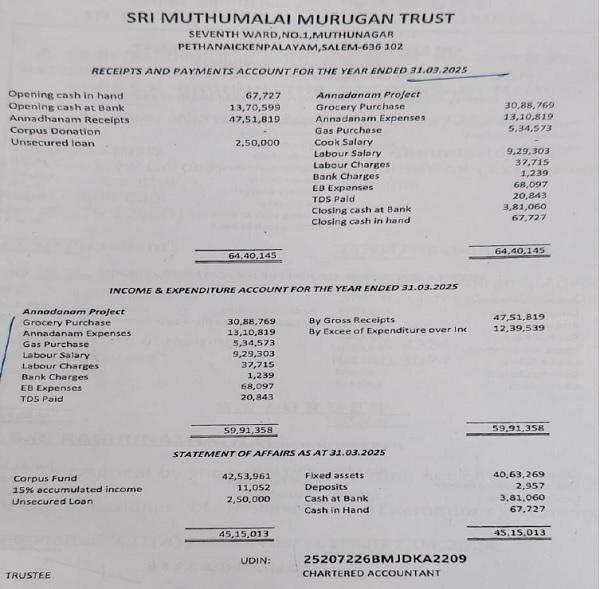
5. From the perusal of the above, it is clear that the assessee is not engaged in any religious activity i.e, purely carrying out charitable activities in terms of distribution of free meal to the poor. Therefore, in our considered view the rejection of approval u/s. 80G on the ground that the assessee is engaged in religious cum charitable purpose is not correct. Further, the revenue has granted approval u/s. 80G of the Act up to AY 2026-27 after considering the activities of the trust and that there is no change with regard to the activities or the objects of the assessee. Accordingly, we direct the CIT(E) to allow the approval u/s. 80G of the Act in accordance with law.
6. In the result, the appeal of the assessee is allowed.
Order pronounced on 06th day of October, 2026 at Chennai.







