Bharat Heavy Electricals Ltd. Vs Commissioner of CGST & Central Excise (CESTAT Chennai)
Summary: The Chennai Bench of the Customs, Excise and Service Tax Appellate Tribunal allowed Bharat Heavy Electricals Ltd.’s appeal against denial of CENVAT credit on input services distributed by its Input Service Distributor registered Input Service Distributor (ISD) cost centres. The appellant manufactured electrostatic precipitators, industrial fans and related products. For September 2013 to July 2014, the Department questioned the nexus between a wide range of services and manufacturing activity, confirmed the demand with interest and imposed a penalty of Rs.20,00,000 under Rule 15(1) of the CENVAT Credit Rules, 2004.
The appellant submitted that its corporate and marketing offices and operational divisions were registered as ISDs, procured common input services and distributed credit under Rule 7. The services included maintenance, advertising, telecommunications, legal consultancy, banking, recruitment, technical testing, training, courier and other business-related services. It referred to earlier orders in its own case and supplied a service-wise table explaining the business purpose, the Department’s objections and supporting decisions. The Department maintained that the appellant had not established the necessary nexus with manufacture.
The Tribunal observed that the Department had not challenged the eligibility of credit at the registered ISD cost centres or identified particular ineligible services with sufficient specificity. The show-cause notice contained general allegations against the manufacturing unit, even though the ISDs were subject to returns, verification and audit. The Tribunal considered the service-wise explanations and earlier decisions, including the treatment of outdoor catering before 1 April 2011 and civil works used for repair, maintenance and modernisation rather than factory setup. Holding that credit could not be denied on vague allegations at the recipient manufacturing unit, it set aside the impugned order and allowed the appeal with consequential relief, if any.
FULL TEXT OF THE CESTAT CHENNAI ORDER
Brief facts are that the appellant is engaged in the manufacture of Electrostatic Precipitators, Industrial Fans, etc. They are registered with the Central Excise department and are availing Cenvat credit on the inputs, capital goods and input services as under the Cenvat Credit Rules 2004.
2. The appellant availed input service credit based on the Input Distributor Service Invoices issued by their Input Service Distributor (ISD) namely “Cost Centres”. The appellant had corporate office at New Delhi, Power Sector Marketing Office at New Delhi, Industry Sector Marketing Office at New Delhi, Regional Operations Divisions and International Operations Division at New Delhi. These were called by the appellant as “Cost Centres”, which had obtained Input Service Distributor for distributing the input service credit. The appellant had availed credit of service tax on the invoices issued by these Cost Centres (ISD invoices). The department was of the view that the services availed by the appellant on the invoices distributed by the ISD do not have any nexus with the manufacturing activity of the appellant, and therefore is not eligible for credit. The various input services under dispute are as under: –
3. Maintenance or Repair Service, Advertising Agency Service, Telecommunication Service, Professional Charges for Patents, Renting of Immovable Property, Man Power Recruitment / Supply Agency services, Technical Testing Service, Air Travel Agent Service, Courier Service, Software Development, Goods Transport Agent Service, Legal Consultancy Service, Information Technology Software Service, Packaging Service, Erection, Commissioning or Installation Service, Security Agency Service, Business Auxiliary Service, Scientific or Technical Consultancy Service, Commercial Training Coaching or Technical Service, Consultancy Services, Facsimile Services, Outdoor Catering Service, Banking & Financial Services, Cable operators, Chartered Accountants, Accommodation Services, Convention Services, Renting of Immovable Proprieties, Share Transfer Agent, Membership, Insurance, Stock Exchanges, Sponsorship, AMC Services, Reverse Auction Services, Civil Works Services, Designing & Printing Services and Finance Lease Services.
4. The department noted that the Cost Centres (the offices of the appellant) are registered with the Central Excise department as Input Service Distributor and they distribute service tax credit to various manufacturing units and erection divisions based on turn over as per Rule 7 (c) or (d) of Cenvat Credit Rules, 2004. These Cost Centres do not have any turnover but only serve the manufacturing units by getting orders from customers, giving guidelines on policy matters to the units, arranging for funds required by the units.
5. The functions of the Coast Centres are as follows:-
Corporate office:
Control 14 manufacturing units and 4 erection divisions. Undertake guidelines on policy matters to the units, arranging for funds required by the units, finalization of technical collaboration, cash collection and allocation and overall administration.
Power Sector Marketing:
Submit bid based on tender floated by various developers of power projects, collection of outstanding dues, statutory forms, settlement of contractual issues and closing of contracts.
Operation Division:
Imports of raw materials and exports of final products. Also collects dues from customers.
Industry Sector Marketing:
Get orders from various companies and allocate orders to various manufacturing units and Erection divisions of BHEL. Also undertake collection of outstanding dues, statutory forms, settlement of contractual issues and closing of contracts.
International Operations Divisions:
Undertake the activity of getting order from developers in other countries.
6. The department was of the view that the appellant has not established that the services received through the ISD invoices are used in relation to manufacture of final products by them. Hence show cause notice dated 08.10.2014 was issued to the appellant proposing to deny the credit availed on input services for the period from September 2013 to July 2014 and proposing to recover the same along with the interest
and for imposing penalties. After due process of law, the original authority disallowed the credit and confirmed the demand along with interest and imposed penalty of Rs.20,00,000/- under Rule 15 (1) of Cenvat Credit Rule 2004. Aggrieved by such order, the appellant is now before the Tribunal.
7. The Ld. Counsel Ms. S. Sridevi, appeared and argued for the appellant. It is submitted that the period involved is from September 2013 to July 2014 which is the period after the major amendment to the definition of Input Services. The Ld. Counsel referred to the definition of input service under rule 2 (l) of Cenvat Credit Rules 2004 for the disputed period which reads as under:-As per Rule 2(1) of CENVAT Credit Rules, 2004 RULE 2(1): Input Services “Input Service” means any service,-
(i) used by a provider of output service for providing an output service; or
(ii) used by the manufacturer, whether directly or indirectly, in or in relation to the manufacture of final products and clearance of final products, up to the place of removal, and Includes services used in relation to modernization, renovation or repairs of a factory, premises of provider of output service or an office relating to such factory or premises, advertisement or sales promotion, market research, storage up to the place of removal, procurement of inputs, accounting, auditing, financing, recruitment and quality control, coaching and training, computer networking, credit rating, share registry, security, business exhibition, legal services, inward transportation of inputs or capital goods and outward transportation up to the place of rernoval; but excludes,-
(A) service portion in the execution of a works contract and construction services Including service listed under clause (b) of section 66E of the Finance Act (hereinafter referred as specified services) in so far as they are used for
(a) construction or execution of works contract of a building or a civil structure or a part thereof; or
(b) laying of foundation or making of structures for support of capital goods, except for the provision of one or more of the specified services; or
(B) Services provided by way of renting of a motor vehicle, in so far as they relate to a motor vehicle which is not a capital goods; or
(BA) Service of general insurance business, servicing, repair and maintenance, in so far as they relate to a motor vehicle which is not a capital goods, except when used by
(a) a manufacturer of a motor vehicle in respect of a motor vehicle manufactured by such person; or
(b) an insurance company in respect of a motor vehicle insured or reinsured by such person; or
(C) such as those provided in relation to outdoor catering, beauty treatment, health services, cosmetic and plastic surgery, membership of a club, health and fitness centre, life insurance, health insurance and travel benefits extended to employees on vacation such as Leave or Home Travel Concession, when such services are used primarily for personal use or consumption of any employee;
Explanation. – For the purpose of this clause, sales promotion includes services by way of sale of dutiable goods on commission basis.
8. It is submitted that the credit has been denied alleging that the appellant has not established that the input services were used for manufacturing activities. It is an admitted fact that the input tax credit has been distributed to the appellant as per rules laid down in terms of Rule 7 of Cenvat Credit Rules 2004. The appellant has 4 Cost Centres which are registered as input service distributors. The appellant has availed credit only through the invoices issued by these input service distributors. The provision for registering as an input service distributor is to facilitate procurement of credit on services centrally and for distribution to various units. These units use the services directly or indirectly with the manufacturing activity or for providing taxable output service. All the services received has a nexus with the manufacture and clearance of final products of the manufacturing units and erection divisions. The payments for procuring the input services which were commonly utilized by all the units were maintained by the Cost Centres registered as an ISD. These Cost Centres having registered as ISD has distributed the credit which qualifies as an input service in terms of Rule 2 (l) of Cenvat Credit Rules 2004, these Cost Centres are subject to verification and audit by their jurisdictional officers. These ISDs are also liable to file periodical returns which are subject to the scrutiny by their jurisdictional officers. The correctness of the credit taken and the manner of distribution of the credit are therefore subject to the
verification of the department. So far, no adverse inference has been made against the Cost Centres (ISDs) in availing the credit.
9. The department has sought to deny the credit that has been distributed to the appellant which is a manufacturing unit alleging that the input service credit availed by the ISD registered Cost Centres is not used either directly or indirectly or in relation to the manufacture and clearance of final products by the appellant. This allegation is erroneous.
10. The allegation in the show cause notice is that the appellant has not produced documentary evidences to prove as to how these services have been used by the appellant so as to qualify as input services.
11. The invoice for each service is available at the input service distributor and the credit after having been distributed to the appellant is availed by them. The invoices clearly show the nature of services availed. All these services are used directly or indirectly or in relation to the manufacturing activity and therefore eligible.
12. The Ld. Counsel submitted that in the appellant’s own case for earlier period similar show cause notice was issued. The appellant had filed appeal before the Tribunal against the denial of credit and confirmation of demand. The Tribunal vide Final Order No.42996/2018 dated 05.12.2018 had set aside the demand and remanded only two issues for further consideration. It was then noted by the Tribunal that Cost Centres being registered with the Central Excise Department as ISD, the department cannot deny the credit to the unit to which the credits have been distributed in accordance with law.
13. Similarly, in the appellant’s own case for different period April 2016 to June 2017 the Commissioner (Appeals) has set aside the demand allowing the appeal filed by the department vide O-I-A No. 12/2022 dated 03.03.2022. The allegations in the show cause notice of the said case are similar to the allegations raised in the present show cause notice.
14. In the appellant’s own case, for the period from March 2013 to June 2013, show cause notice was issued denying credit to the tune of Rs.1,18,075/- alleging that certain input services are not eligible for credit. Services in the nature of air travel service, accommodation service, was under dispute in the said show cause notice. The original authority, after considering the submissions of the appellant vide O-I-O No.20/2022 dated 30.03.2022 held that the credit is eligible and dropped the entire proceedings in respect of show cause notice C. No. IV/16/102/2013- Adj. dated 24.09.2013. similarly, the proceedings initiated vide show cause notice dated 17.04.2006 on issue of availing credit on certain input services was dropped by original authority vide O-I-O No.29/2022 dated 03.06.2022 (period is March 2005).
15. It is submitted by the Ld. Counsel that the disallowance of the credit is without any legal or factual basis. It is prayed that the appeal may be allowed.
16. The Ld. AR Shri. N. Satyanarayanan, appeared and argued for the department. It is argued that the appellant has to establish that the services are used directly or indirectly for manufacturing activity. The credit has been correctly disallowed by the adjudicating authority. It is prayed that the appeal may be dismissed.
17. Heard both sides.
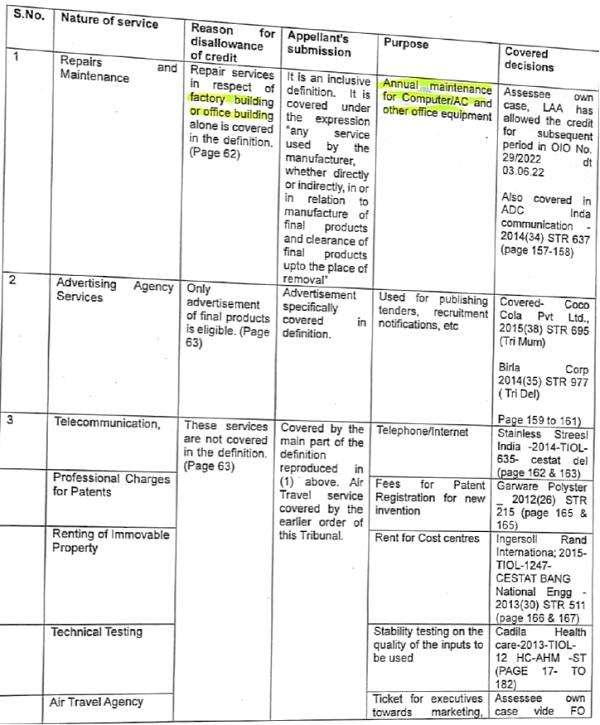
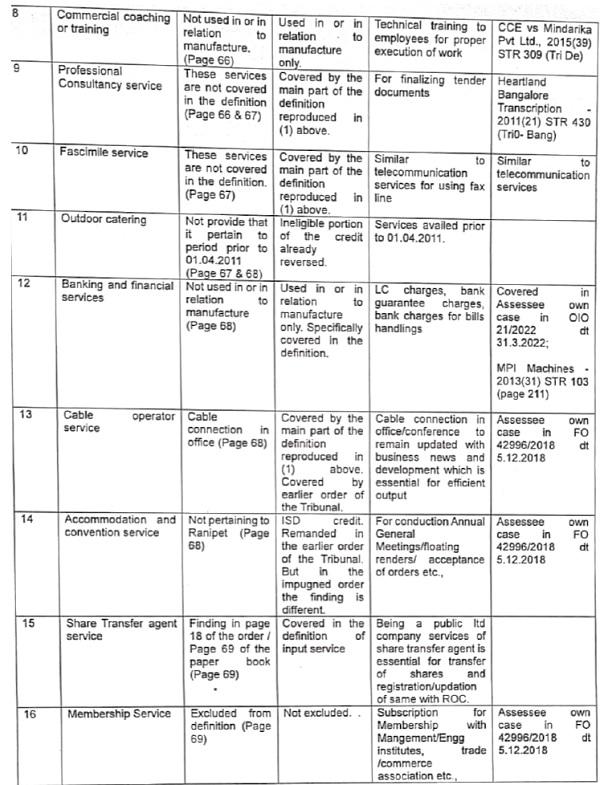
18. The only allegation raised in the show cause notice to disallow input service credit is that the appellant has not established that these services have been used directly or indirectly or in relation to the manufacturing of final products. The Ld. Counsel for appellant has given a tabulation with regard to the various services under dispute and the nexus of such services for the manufacturing activity. The said table reads as under:-
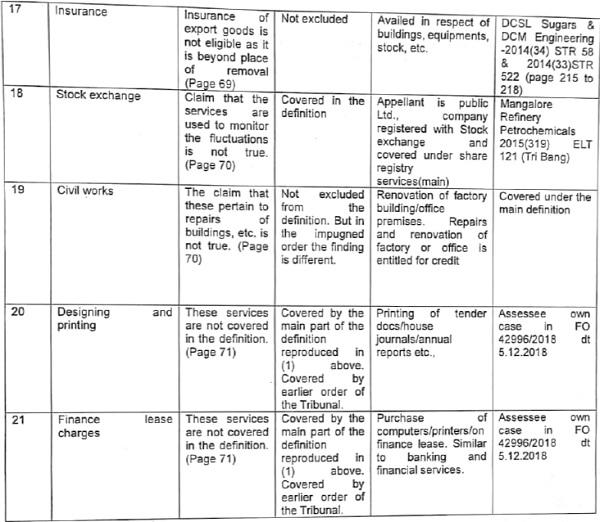
20. The department has sought to deny the credit at the end of the manufacturing unit which has availed the distributed credit. There is no allegation that the provisions of Rule 7 of Cenvat Credit Rules 2004 for distribution of credit has not been complied. The show cause notice is very vague in alleging that the appellant has not established that the credit is utilized for manufacturing activity.
21. When there is no dispute raised by the jurisdictional authorities against the input service distribution centres for availing the credit and distributing the same, the department cannot deny the credit at the end of the manufacturing unit on very vague allegations. The show cause notice does not make any specific allegation with respect to particular input service.
22. In the appellant’s own case for a different period the very same issue of disallowing credit at the manufacturing unit distributed by the Cost Centres and has been considered by the Tribunal vide Final Order No.42996/2018 dated 05.12.2018 in Appeal No E/40788/2018.
23. Almost all the services listed in the above table was held to be eligible for credit by the Tribunal, by the Commissioner (Appeals) and by the adjudicating authority as pointed out by the Ld. Counsel. The appellant has given the details of the case law in respect of each input service in the last column of the table. We find that the decisions in the appellant’s own case as well as the decisions passed by the Tribunal in
other appeals applies to the issue of eligibility of credit on the disputed input services.
24. In respect of outdoor catering services, it is seen that the services have been availed prior to 01.04.2011. So, also in the case of works contract services/ civil work these are availed for repair and maintenance as well as modernization and not of setting up of a factory. There is no allegation by the department that such civil works were availed for setting up of a factory.
25. We find that all the services are eligible input services. The credit cannot be denied on such vague allegations at the end of the manufacturing unit without disputing the credit availed by the input service distributor. For these reasons we find that the impugned order cannot sustain.
26. In the result the impugned order is set aside. The appeal is allowed with consequential reliefs, if any.
(Order pronounced in the open court on 11.07.2024)