
Sarvjeet Singh Through L/H Manjit Kour Vs ITO (ITAT Jaipur)
Background of the Case
The Jaipur Tribunal deleted an addition of ₹22,19,515 after finding that the Department had mistaken a purchase of property for a sale.
The information relied upon by the Assessing Officer and the purchase deed furnished by the assessee concerned the same property transaction. However, the authorities proceeded on the erroneous premise that the assessee was the seller, resulting in an addition towards alleged income from sale of land.
The Tribunal held that the addition failed on the facts themselves. The documentary record established that the assessee had purchased the property rather than sold it.
Reopening Based on Alleged Sale of Land
The Assessing Officer initiated reassessment proceedings under Sections 147 and 148 on information that the assessee had sold land for ₹18,50,000, against a stamp duty or DLC value of ₹22,19,515.
On that basis, the Assessing Officer formed the view that income had escaped assessment.
The assessee filed a return declaring income of ₹10,66,315 from real estate business on a presumptive basis under Section 44AD.
During assessment, the Assessing Officer questioned the assessee’s claim of carrying on business involving land transactions. He considered the income to arise from transfer of capital assets rather than business activity.
He also added ₹22,19,515, being the DLC value of the property allegedly sold, to the assessee’s income.
Purchase Deed Failed to Receive Proper Appreciation
The assessee challenged the assessment before the CIT(A), raising both factual and legal objections. The CIT(A), however, rejected the grounds and dismissed the appeal.
Before the Tribunal, the assessee’s representative submitted that the fundamental factual error had been repeatedly pointed out to both authorities.
The assessee had not sold land for ₹18,50,000 with a DLC value of ₹22,19,515. He had purchased land for that consideration.
The purchase deed had already been furnished before the lower authorities. The dispute therefore concerned the correct appreciation of an existing document rather than an unsupported explanation advanced for the first time.
Tribunal Calls for the Underlying Information
During the appellate proceedings, the Tribunal directed the Revenue to obtain a report from the Assessing Officer concerning the information on which the alleged sale was based.
The report was submitted on 23 June 2025.
The assessee’s representative compared the transaction particulars in that information with the purchase deed. The comparison identified the same property, consideration, DLC value and counterparty.
The information concerned Plot No. 387, Scheme No. 2, Lajpat Nagar, Alwar, with Harish Kumar identified as a party to the transaction.
The purchase deed showed Harish Kumar as seller and Sarvjeet Singh as buyer, with consideration of ₹18,50,000 and DLC value of ₹22,19,515.
Department’s Own Material Supported the Assessee
The Tribunal found that the relevant particulars in the Department’s information matched those in the purchase deed.
This established that the transaction relied upon for making the addition was a purchase by the assessee.
The Departmental Representative could not controvert the factual submission that the information related to purchase of land rather than sale.
The Tribunal consequently held that the addition arose from incorrect appreciation of the transaction itself. Once the assessee’s position as purchaser was established, the addition towards income allegedly earned from selling that property could not survive.
₹22,19,515 Addition Deleted
The Tribunal directed deletion of the entire addition of ₹22,19,515 made on account of the alleged sale.
The assessee’s appeal was allowed.
The operative decision rested on the demonstrated factual error. The Tribunal did not separately decide the wider objections concerning reassessment jurisdiction or lay down a general conclusion on the assessee’s eligibility under Section 44AD.
Accordingly, the order should principally be cited for its finding that the very transaction underlying the addition had been wrongly identified.
Author’s Comments
The case illustrates why information reporting a property transaction must be examined for the taxpayer’s actual role as buyer or seller before drawing an inference of taxable income.
A transaction value does not identify the nature of income, and a stamp duty value cannot establish that the person concerned sold the property. Those conclusions require examination of the underlying document.
Here, the assessee’s purchase deed was consistent with the Department’s own transaction particulars. A basic comparison of the two records would have exposed the error at an earlier stage.
The decision also highlights the value of seeking the precise information relied upon by the Assessing Officer. Comparing property identification, counterparty, consideration and stamp duty value can reveal whether the proposed addition rests on the correct transaction and the correct person.
The relief remains specific: the addition for an alleged sale was deleted because the assessee was the purchaser. The Tribunal did not adjudicate any separate issue concerning the source of the purchase investment.
FULL TEXT OF THE ORDER OF ITAT JAIPUR
The present appeal has been filed by the assessee against the order passed by the National Faceless Appeal Centre (NFAC), Delhi (hereinafter referred to as “Ld. CIT(A)”), dated 21.01.2025 under Section 250 of the Income Tax Act, 1961 (hereinafter referred to as “the Act”).
2. The grounds raised by the assessee read as under:-
1. The impugned additions and disallowances made in the order u/s 143(3r.w.s 147 r.w.s 144 dated 30.09.2021 are bad in law and on facts of the case, for want of jurisdiction and various other reasons and hence the same kindly be deleted.
2 The ld. AO erred in law as well as on the facts of the case in framing the asst. u/s 144 without affording adequate and reasonable opportunity and even without complying with the mandatory statutory requirement of law. The impugned order having been framed in gross breach of natural justice, kindly be quashed.
3. The very action taken u/s 147 r/w 148 is bad in law without jurisdiction and being void ab-initio, the same kindly be quashed. Consequently, the impugned assessment framed u/s 143(3)/148 dated 30.09.2021also kindly be quashed.
4. The ld. CIT(A)/NFAC seriously erred in law as wellas on the facts of the case in confirming addition of Rs. 22,19,515/ made by the AO. The addition so made and confirmed beingcontrary to the provisions of law & facts kindly be deleted full.
5. The ld. AO erred in law as well as on the facts of the case in charging interest u/s 234A, 234B & 234C of the Act. The appellant totally denies it liability of charging of any such interest. The interest, so charged, being contrary to the provisions of law and facts, kindly be deleted in full.
6. The appellant prays your honour to add, amend or alter any of the grounds of the appeal on or before the date of hearing.
3. Brief facts relating to the case are that reopening in the present case was resorted to by the AO by issuing notice u/s 148 of the Act on the basis of information in his possession that the assessee had sold land for a consideration of Rs.18,50,000/- the stamp duty value of which was Rs.22,19,515/- and income to the extent therefore had escaped assessment.
4. The assessee filed return of income declaring income of Rs.10,66,315/- from business of realtor on presumptive basis u/s 44AD of the Act .during assessment proceedings ,on the basis of information available , the AO found assesses claim of indulging in business activity of sale of land to be suspicious. He held that the income earned was by way of sale of capital assets, in the nature of capital gains. Accordingly he rejected assesses claim of business income returned to tax u/s 44AD of the Act. Further he also made addition of the land noted by him to have been sold, adding the DLC value of the same amounting to Rs.22,19,515/- to the income of the assessee.
5. The assessee challenged the order of the AO before the Ld. CIT(A) both on merits and on legal grounds also .The Ld. CIT(A) rejected all the grounds raised by the assessee and dismissed the appeal of the assessee.
6. Before us, ld. Counsel for the assessee contended that the Authorities Below had failed to appreciate the facts of the case. He contended that it was repeatedly pointed out both to the AO and the Ld. CIT(A) that the assessee had not sold any land for Rs.18,50,000/- DLC Value of Rs.22,19,515/- but in fact had purchased the land of this value. He pointed out that during the course of hearing before the ITAT, the Bench had directed the Ld. DR to submit a report of the AO of the information on the basis of which it was alleged that the assessee had sold land of value of Rs.18,50,000/- DLC value of Rs.22,19,515/-, which report , he stated, had been submitted on 23.06.2025. Referring to the same he pointed out that the details of the transaction in land conducted by the assessee contained in the information available with the AO submitted vide its report was in relation actually to the land purchased by him, the purchase deed of which was submitted to the Authorities below. He pointed out that as per the information of the transaction of land undertaken by the assessee, the same was as under:-
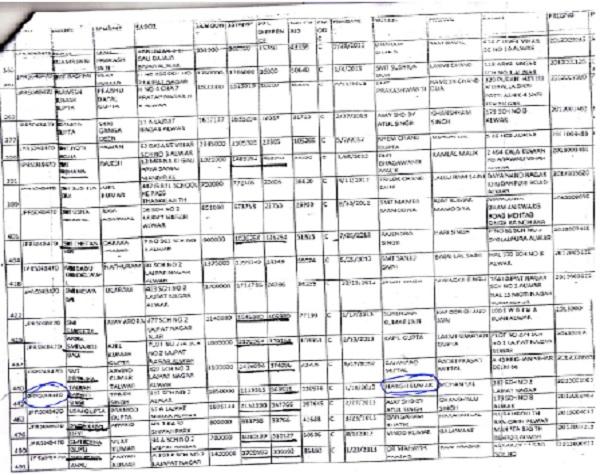
7. Referring to the same he pointed out that the information relating to the assessee revealed address of land 387 SCH No.2 Lajpat Nagar, one of the parties to the transaction is Mr. Harish Kumar, date of transaction is 18.02.2013 and the DLC Value is Rs.22,19,515/-
8. He thereafter drew our attention to the purchase deed submitted to the authorities below placed before us at paper book page No.21 reflecting the same fact of the seller being Harish Kumar, buyer being Sarvjeet Singh, the consideration for the transaction being Rs.18,50,000/- and the property being Plot No.387 Scheme No.2 Lajpat Nagar, Alwar, its DLC Value being Rs.22,19,515/- transaction being undertaken on 10.02.2013.
9. He contended therefore that it was clearly evidenced that the assessee had undertaken transaction of purchase and not of sale and therefore the addition made in the hands of the assessee was untenable on facts itself.
10. Ld. DR was unable to controvert the factual contention of the Ld. Counsel for the assessee that even as per the information available with the AO the same related to purchase of land and not sale of land and therefore addition made to the income of the assessee on account of alleged sale of land was incorrect.
11. In view of the facts as demonstrated above, undoubtedly the addition made in the hands of the assessee on account of sale of land is based on incorrect appreciation of facts itself. The transaction has been clearly demonstrated to be on account of purchase of land. This fact is demonstrated by showing the parity of facts relating to the transactions recorded in the information available with the AO and the purchase deed furnished by the assessee to the Authorities Below. The data contained in the information with the AO of the transaction and the data in the purchase deed furnished by the AO completely tally. Thereof the fact that the assessee during the impugned year had purchased the property and not sold the property stands established.
12. The addition made thereforeof Rs.22,19,515/- in the hands of the assessee on account of income earned by way of sale of land is held to be incorrect and is directed to be deleted.
13. In effect, the appeal of the assessee is allowed.
Order pronounced in the Open Court on 16.10.2026








