Jagjeet Singh Vs ITO (ITAT Chandigarh)
CIT(A) ignores ITAT remand & remand report; Chandigarh ITAT quashes appellate order & orders fresh adjudication
Chandigarh ITAT held that CIT(A) acted in clear disregard of earlier ITAT directions by confirming addition of peak cash credit u/s 69A without considering documents filed by Assessee or the remand report already called for by earlier CIT(A). Tribunal noted that in its earlier order dated 03-07-2019, it had specifically directed CIT(A) to first adjudicate jurisdictional challenge u/s 147/148 & thereafter decide appeal on merits after following due process. However, impugned order was passed merely on ground that Assessee failed to file evidence, ignoring available material & remand report, rendering findings unsustainable in law. Accordingly, Tribunal quashed order of CIT(A) & remanded matter back for fresh de-novo adjudication, directing CIT(A) to allow filing of evidence, call for remand report from AO, permit rebuttal & pass a reasoned speaking order. Appeal was allowed for statistical purposes
FULL TEXT OF THE ORDER OF ITAT CHANDIGARH
The present appeal is arising out of the order dated 05.12.2024 passed by the ld.CIT (Appeals) for assessment year 2009-10.
2. The assessee has raised the following grounds of appeal :
1. That the assessment order as well as the order of Learned CIT(A), (Addl./JCIT(A)-4, Kolkala), dated 05/12/2024 both are against the facts of the case and are untenable under the law.
2. That no reasonable opportunity of being heard was allowed by the A.O. before passing the order. As such, the assessment order is bad in law and is liable to be cancelled. Again, the worthy CIT(A) has grossly erred in confirming the addition of Rs.l2,02,991/- made by the Assessing Officer.
3. That the Ld. CTT(A) further failed to appreciate that issuance of notice 147/148 of the Income-Tax Act, 1961, is illegal, invalid and void ab-initio, as it does not fulfill the conditions as laid down under the law.
4. That there was no application of mind while issuing the notice under section 147/148 of the Income-Tax Act, 1961, and the initiation of proceedings is bad in the eyes of law and as such the assessment completed u/s 143(3)/147/148 may kindly be annulled.
5. That again the CIT(A) failed to appreciate that the cash which was deposited in the bank did not belong to appellant but the amount was related to other persons. Later on when their accounts were opened independently, I used to transfer those amounts to said parties. As such these amounts did not belong to assessee but different depositors who came to my bank for operating the bank accounts.
6. That the CIT (Appeals) did not appreciate that in order to increase the bank depositors I used to accept the cash from customers and used to deposit the same in my bank account because of the reason that it took some time to open the bank account. Later on when the accounts were opened of respective customers, I used to transfer the amounts to respective customers. The department has not been able to prove that these amounts belong to the assessee. As such the addition made is purely based on conjectures, surmises and suppositions.
7. That the authorities below did not appreciate that the assessee was an employee with bank and did not have any connection with these deposits. As such the addition made is unjustified, uncalled for and the same may be deleted.
8. That this case does not fall within the mischief of section 69A of the IT Act, 1961. As such the addition made is unjustified, uncalled for and the same may be deleted.
9. That alternatively the addition made is very high & excessive.
10. That interest charged u/s 234B of the IT Act, 1961, is not at all called for and the same is liable to be cancelled. Alternatively, the interest charged is very high & excessive.
11. That any other ground of appeal which may be argued at the time of hearing of the appeal.
3. The ld. AR has drawn our attention to the order passed by the ld.CIT (Appeals) and he has drawn our attention to page 10 of the order passed by the ld.CIT (Appeals) which is to the following effect :
Ground No 1 :- 1 have carefully perused the records, all submissions, assessment Order and the Order of the Hon’ble ITAT has been carefully perused. The Appellant has not furnished any further evidence or explanation regarding the Grounds No 3, 4 and 8 as raised before the Hon’ble ITAT. In absence of the same, it is apparent that the Order passed by the Ld AO has to be sustained. The Appellant has failed to furnish any document, explanation to show that proceedings initiated u/s 147 was bad and illegal, Invalid and void. I find that there was information before the Ld AO that huge cash was deposited in the Bank Accounts of the Appellant and the Ld AO has also found that such cash deposit is not reflected in the ITR. The Appellant has also admitted that such huge cash was deposited in his bank accounts. He stated that the cash don’t belong to him and related to other persons whose cash was deposited in his bank accounts. But he failed to prove the identity of those persons and the ownership of cash with them. Hence, there was nothing irregularity in initiation of the proceedings and addition of the same in the hand of the Appellant.
Regarding the Ground No 8, it is seen that the Ld AO has added the peak credit in the bank account and not the entire cash deposits though there was no evidence or even claim that the same cash was deposited to the bank accounts after withdrawal of the same from the bank accounts or there was any business run by the Appellant. The inter account transactions were also considered and kept outside the amounts for addition.
In this year, it is seen that the Peak Credit was reduced by the amount of Peak Credit for earlier years which have been added in that year. So, the addition was a very judicious one and all within the four corners of law. Hence, the Ground raised in Form No 35 (considering the grounds raised before the Hon’ble ITAT, which was referred to the First Appellate Authority for consideration) is DISMISSED.”
4. It was submitted that the Hon’ble Tribunal vide decision dated 03.07.2019 in ITA Nos.1574 to 1577/CHD/2018 had remanded back the matter to the file of the ld.CIT (Appeals) with the following direction :
“7. We have heard the submissions and perused the material available on record, it is seen that the jurisdictional challenge posed in the ground numbers 3 and 4 in the present proceedings was not raised before the C1T(A). Accordingly, there is no discussion on the issue. In the absence of relevant discussion on facts, it is deemed appropriate to set aside the issue back to the file of the C1T(A). As a result thereof, the impugned order is set aside back to the file of the CIT(A)with the direction to first address the jurisdictional challenge and thereafter proceed to decide the appeal on merits including the alternate prayer of the assessee couched in ground No. 8. While so directing it is hoped that the assessee participates in the proceedings fully and fairly and does not abuse the trust reposed. It is made clear that in the eventuality of abuse of the trust reposed, the C1T(A) would be at liberty to pass an order on the basis of material available on record.”
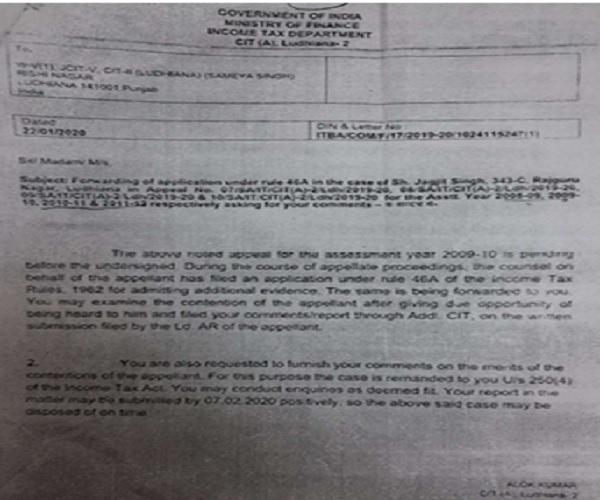
5. It was submitted that despite the direction given by the Tribunal, the ld.CIT (Appeals) has dismissed the appeal of the assessee on the ground that the assessee failed in filing the requisite documents in respect of Ground Nos. 3, 4 and 8. It was submitted that there was no occasion for the assessee to file these documents as the ld.CIT (Appeals) has grossly misconducted himself and has not taken into account the remand report which was called for by the earlier CIT (Appeals). It is available at page 12 of the Paper Book and have decided the appeal without considering the remand report. In this regard, our attention was drawn to the remand report given by the AO on 22.01.2020 at page 12, which is to the following effect :