Manav Utthan Seva Samiti Vs CIT (Exemption) (ITAT Surat)
Wrong Clause Selection Cannot Defeat 80G Approval Claim: ITAT Surat Orders Fresh Examination
The Income Tax Appellate Tribunal (ITAT), Surat Bench, in Manav Utthan Seva Samiti v. Commissioner of Income Tax (Exemption), Ahmedabad, held that inadvertent selection of an incorrect clause or code in an application constitutes a procedural lapse which should not, by itself, defeat a substantive claim for registration or approval.
By its common order dated 30 October 2026, the Tribunal restored the assessee’s applications concerning Section 80G(5) approval and Section 12A registration for fresh consideration. It also condoned a 633-day delay in filing the appeal against the earlier rejection of 80G approval.
Background: Existing Approval Followed by Incorrect Clause Selection
The assessee held approval under Section 80G(5) effective from 28 June 2016. Following the introduction of the revised approval regime effective from 1 April 2021, it submitted an application on 26 March 2022.
However, while filing the application, the assessee mistakenly selected clause (iv) of the first proviso to Section 80G(5), instead of clause (i) applicable to an institution having pre-existing approval.
Consequently, the Department granted provisional approval on 4 April 2022. Thereafter, the assessee submitted another application on 30 September 2023 under clause (iii), seeking renewal/permanent approval.
The CIT(E) rejected this application on 20 March 2024, holding that the prescribed filing deadline had expired on 30 September 2022, considering commencement of activities from 1 April 2022. The provisional approval was also cancelled.
Assessee’s Submissions
The assessee explained that the initial selection of the wrong clause had carried forward into the subsequent approval proceedings.
It submitted that the revised statutory framework contained several clauses governing different situations, resulting in confusion among taxpayers and professionals. The incorrect selection was inadvertent, conferred no benefit on the assessee, and represented a rectifiable procedural defect.
The assessee requested an opportunity to correct the applicable clause and have its application examined on merits. It also pointed out that rejection arising from such confusion could affect donors who had made substantial donations.
The Revenue opposed the request, arguing that the assessee itself had selected the incorrect clause and that the rejection order contained no error warranting interference.
ITAT: Procedural Error Should Not Defeat Substantive Claim
The Tribunal observed that the revised approval framework involved multiple clauses and sub-clauses concerning provisional, final and renewal approvals. Difficulties in understanding these provisions had resulted in inadvertent clause-selection errors in several cases.
It referred to decisions including Subhadra Foundation, Rambha Charitable Trust, North Eastern Social Research Centre, and Balaji Gau Sarakshan Sansthan.
According to the Tribunal, these decisions consistently recognised that an inadvertent selection of an incorrect clause or code, by itself, was a procedural lapse which should not defeat a substantive claim for registration or approval.
Following these decisions, the ITAT set aside the rejection order and directed fresh adjudication. The CIT(E) was required to permit rectification of the applicable clause or code, if necessary, and examine the application on merits without being influenced by observations in the earlier order.
The Tribunal also directed the authority to pass a speaking order after providing an opportunity of hearing.
Delay of 633 Days Condoned
The appeal against the order dated 20 March 2024 was filed with a delay of 633 days.
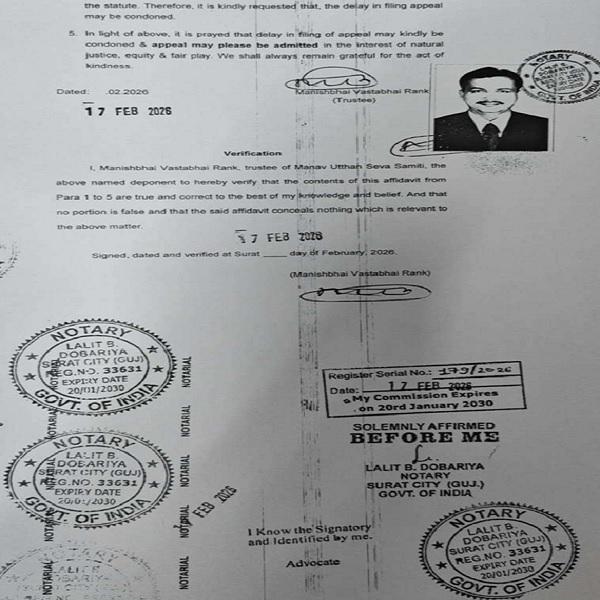
In its affidavit, the assessee explained that it had misunderstood the distinction between Section 12A registration and Section 80G approval. It believed that filing a fresh application would cure the defect and subsequently approached counsel after that application was also rejected.
The Tribunal accepted that sufficient cause had been established. Exercising its power under Section 253(5) and referring to the Supreme Court’s decision in Collector, Land Acquisition v. Mst. Katiji, it adopted a justice-oriented approach and admitted the appeal.
Section 12A Rejection Also Restored
In the separate appeal concerning Section 12A registration, the Tribunal found that rejection was primarily attributable to non-submission of the required details and documents.
Only one opportunity, dated 23 February 2026, appeared to have been granted before the rejection order dated 8 March 2026.
Considering the significant consequences of registration proceedings, the Tribunal directed fresh consideration after reasonable and adequate hearing opportunities. The assessee was directed to furnish the necessary
Cases Discussed:
- Subhadra Foundation Vs Commissioner of Income-tax Exemption, Pune — ITA Nos. 1744 & 1745/PUN/2025; 09.09.2025
- Rambha Charitable Trust, Mumbai Vs Commissioner of Income-tax — ITA No. 5111/Mum/2024; 29.11.2024
- North Eastern Social Research Centre Vs CIT(Exemption), Kolkata — ITA No. 741/Kol/2024; 09.07.2024
- Balaji Gau Sarakshan Sansthan Vs CIT(Exemption), Bhopal — ITA Nos. 887 & 890/Ind/2025
- National Association for the Blind Vs CIT(Exemption), Pune — ITA No. 2389/PUN/2024
- Raj Krishan Jain Charitable Trust — cited within reproduced precedent
- Collector, Land Acquisition Vs Mst. Katiji and others — 1987 AIR 1353; 1987 2 SCC 387
FULL TEXT OF THE ORIGINAL ORDER OF ITAT SURAT
The captioned three (3) appeals filed by assessee are inter-connected/inter-related, hence they are being disposed of by this common order. We proceed to take up these appeals, one by one, in a logical sequence instead of their registration numbers.
ITA 868/SRT/2026:
2. This appeal is directed against the order bearing DIN: ITBA/EXM/F/EXM45/2025-26/1087007099(1) and dated 08.03.2026 passed by learned Commissioner of Income-tax (Exemption), Ahmedabad [“Ld. CIT(E)”] by which the application filed by assessee for registration u/s 12A has been rejected.
3. Ld. AR for assessee carried us to the impugned order and submitted that the Ld. CIT(E) has passed ex-parte order while granting only one opportunity to the assessee, which the assessee could not avail. It was further submitted that the impugned order has been passed without examining the applications on merits. It was also emphasised that the registration u/s 12A is fundamental and necessary for the existence and functioning of assessee since the assessee is engaged in charitable/religious activities for the benefit of the public. It was further submitted that the assessee is ready with the requisite details and documents for making an effective representation before Ld. CIT(E). It was also assured that if one more opportunity is given, the assessee shall fully co-operate and make effective representation before Ld. CIT(E). Accordingly, it was prayed that in the interest of justice and fair play, the present matters be restored to the file of Ld. CIT(E) for a meritorious adjudication after affording reasonable opportunity of hearing to assessee.
4. Per contra, Ld. DR for revenue submitted that there is no infirmity in the order passed by Ld. CIT(E). He submitted that the assessee voluntarily filed application to Ld. CIT(E) seeking registration u/s 12A, therefore it was incumbent upon the assessee to stay diligent and make representation before Ld. CIT(E) when called upon. He submitted that the Ld. CIT(E) has given opportunity to assessee but the assessee failed to avail the same. Therefore, the Ld. CIT(E) could not get necessary satisfaction for granting registration due to the failure of assessee. He, therefore, submitted that the rejection of application by Ld. CIT(E) was fully justified and the impugned order be upheld.
5. We have considered the rival submissions of both sides and carefully perused the case files including the impugned order passed by Ld. CIT(E). We find that that the rejection of the application by Ld. CIT(E) is primarily on account of non-compliance by the assessee in furnishing the requisite details and documents. At the same time, on a perusal of Column No. 10 of the impugned order (main body of Form No. 10AD) passed by Ld. CIT(E), the Ld. CIT(E) appears to have granted only one opportunity on 23.02.2026 to assessee, which shows that the Ld. CIT(E) has not afforded sufficient opportunities. Considering the nature of proceeding relating to grant of registration u/s 12A, which has significant consequences for the assessee and in the interest of justice and fair play and also having regard to the fact that the remanding of this matter to the file of Ld. CIT(E) would not cause any prejudice to the revenue/respondent, we are of the view that the assessee should be granted one more effective opportunity to substantiate his application. Accordingly, we set aside the impugned order and restore this matter to the file of the Ld. CIT(E) for a fresh consideration. The Ld. CIT(E) shall examine the application afresh after providing reasonable and adequate opportunities of being heard to assessee. The assessee is also directed to make representation to Ld. CIT(E) and furnish all requisite details and documents without seeking unnecessary adjournments failing which the Ld. CIT(E) shall be at liberty to pass order in accordance with law. Ordered accordingly.
6. Accordingly, this appeal is allowed for statistical purposes.
ITA 230/SRT/2026:
7. This appeal is directed against the order bearing DIN: ITBA/EXM/F/EXM45/2023-24/1063038795(1) and dated 20.03.2024 passed by learned Commissioner of Income-tax (Exemption), Ahmedabad [“Ld. CIT(E)”] by which the application dated 30.09.2023 filed by assessee for approval u/s 80G(5) has been rejected.
8. There is a delay of 633 days in filing this appeal. The assessee has filed an application/affidavit for condonation of delay; the same is scanned and reproduced for an immediate reference:
AFFIDAVIT
I, the undersigned, Manishbhai Vastabhai Rank, trustee of Manav Utthan Seva Samiti, aged 60 years, residing at A-801, Shyam Luxury, Behind J.H. Ambani School, Vesu, Surat City, Surat, on this ___ day of February, 2026, solemnly affirm as under:
1. In this case, Commissioner of Income Tax (Exemption), Ahmedabad passed an order for rejection of approval under clause (ii) of first proviso to sub section (5) of section 80G of the I.T. act on 20.03.2024. As such, the appeal against above order ought to have been filed within 60 days of receipt of above order i.e. on or before 19.05.2024. However, we could not file appeal before the above date and there is a delay of approximately 635 days in filing appeal as on the date of making this affidavit. It may please be noted that there is no mala fide intention on our part in not filing the appeal within stipulated time-limit. Thus, we hereby request you to kindly admit its appeal as valid appeal in view of following reasons.
2. In this regard, it is respectfully submitted that the assessee had originally filed an application on 30.09.2023 for approval under clause (ii) of the first proviso to sub-section (5) of section 80G of the I.T. Act. The learned Commissioner of Income Tax (Exemption), Ahmedabad, passed an order dated 20.03.2024 rejecting the application on the ground that Form No. 10AB was not filed within the time prescribed under the statute. At that point of time, due to complexity in the law we were under a bona fide belief that since registration under section 12A(1)(ac)(iii) was already valid from A.Y. 2022-23 to A.Y. 2026-27, there was no immediate adverse consequence and no further action was required. The assessee is a charitable institution and not conversant with the technical distinction between approval under section 80G and registration under section 12A. It was genuinely believed that filing a fresh application would cure the defect, especially when the rejection was on technical ground of limitation and not on merits.
3. Accordingly, instead of preferring an appeal against the order dated 20.03.2024, the assessee filed another application on 29.09.2025 under clause (ii) of the first proviso to section 80G(5). The said application was again rejected. Immediately thereafter, the assessee approached counsel – Adv. Sapnesh R. Sheth – and upon detailed discussion, it was advised that the original rejection order dated 20.03.2024 ought to have been challenged in appeal and that filing a fresh application could not substitute the statutory appellate remedy. It was only at that stage that the assessee became aware of the legal necessity to challenge the original order.
4. We apologize for default on my part & request to condone the delay in filing of appeal as the same is caused purely due to the above bona fide reasons & we do not have any intention in disregarding the provisions of
9. We have considered the explanation furnished by the assessee in the affidavit filed in support of the application. The Ld. DR opposed the condonation of delay; however, after considering the matter, the Ld. DR left the issue to the discretion of the Bench. Having regard to the explanation furnished by the assessee and the material available on record, we find that the assessee has established sufficient cause for the delay in filing the present appeal. Section 253(5) of the Act empowers the Tribunal to admit an appeal after the expiry of the prescribed period if sufficient cause is shown for not presenting the appeal within such period. Further, the Hon’ble Supreme Court in Collector, Land Acquisition Vs Mst. Katiji and others 1987 AIR 1353, 1987 2 SCC 387 has emphasised the need for adopting a justice-oriented approach while considering an application for condonation of delay. Accordingly, considering the facts and circumstances of the present case and the explanation furnished by the assessee, we condone the delay of 633 days, admit the appeal and proceed to adjudicate the same on merits.
10. On merit of case, the Ld. AR submitted that the assessee was having approval u/s 80G(5) granted by Ld. CIT(E) vide Certificate No. Ahm/80G(5)/264/MUSS/2016-17/571 w.e.f. 28.06.2016 and the approval so granted was effective all along; copy of certificate is placed at Page 4 of Paper-Book. However, after amendment in the provisions of section 80G through TOLA, 2021 w.e.f. 01.04.2021, the assessee was required to obtain new approval and accordingly, the assessee filed application dated 26.03.2022 to Income-tax Department. While filing such application, the assessee mistakenly selected “Clause (iv) of first proviso to section 80G(5)” instead of correct clause “Clause (i) of first proviso to section 80G(5)” applicable to it [Clause (i) was applicable to an assessee having pre-existing approval u/s 80G(5), which the present assessee had]. On assessee’s application, the Income-tax Department also granted “Provisional Approval” under “Clause (iv) of first proviso to section 80G(5)” vide order dated 04.04.2022 for the period 04.04.2022 to AY 2024-25; copy of order is placed in Paper-Book at Pages 9-10. Subsequently, in continuation of such provisional approval granted by department, the assessee filed application dated 30.09.2023 for renewal/permanent approval under “Clause (iii) of first proviso to section 80G(5)”. The Ld. CIT(A) has, vide impugned order dated 20.03.2024, rejected assessee’s application as not maintainable, on the ground that the prescribed time-limit for filing such application had already expired on 30.09.2022 since the activities of the assessee had commenced from 01.04.2022 [Para 7 of impugned order]. The Ld. CIT(E) has also cancelled the Provisional Approval granted earlier to assessee. Therefore, aggrieved, the assessee has filed present appeal. [Subsequently, the assessee has also filed one more application dated 29.09.2025 under which also stands rejected by Ld. CIT(E) vide a separate order dated 19.01.2026 – Against this order of Ld. CIT(E), the assessee has filed appeal No. ITA 231/SRT/2026 which we shall be adjudicating separately in subsequent Para No. 17-20 of this order].
11. Having narrated thus, the Ld. AR submitted that in present case, the assessee was already having pre-existing approval u/s 80G(5) before 01.04.2021. Thereafter, due to introduction of new provisions in section 80G(5) from 01.04.2021 through TOLA, 2021, the assessee had to undergo the process of seeking new approval. However, as narrated earlier, there occurred a mistake of selecting wrong clause/code at the initial stage itself in the very first application dated 26.03.2022 filed by assessee. This mistake perpetuated in subsequent proceedings i.e. grant of provisional approval by department as well as subsequent application dated 30.09.2023 filed by assessee which is rejected by Ld. CIT(E) in impugned order. Ld. AR submitted that there are numerous decisions given by different benches of ITAT that such a mistake i.e. selecting wrong clause/code while filing application is a procedural mistake. Further, occurrence of this mistake is attributable to the reason that there is a substantial change made in the provisions of section 80G(5) whereby several clauses/sub-clauses have been introduced for different situations and the professionals/assessees across India have committed mistakes due to confusion/lack of understanding of provisions. He submitted that the case of assessee is also same, otherwise there was no reason of selecting wrong clause/code. He submitted that by selection of wrong clause/code, the assessee does not derive any benefit. He submitted that the inadvertent selection of an incorrect clause/code in the electronic application constituted a mere procedural defect capable of rectification and, therefore, it should not be a basis for rejection of assessee’s approval. He submitted that in the situation, he would be satisfied if the present matter is remanded back to the file of Ld. CIT(E) with a suitable direction, for a fresh consideration. He requested that the assessee be permitted to rectify the applicable clause/code, if required by Ld. CIT(E), and that the application be considered afresh on merits after affording due opportunity of hearing. He submitted that such a course of action is also necessary because, for the reasons of confusion and selection of wrong clause/code, the donors who have given substantial donations to assessee would be impacted. He assured that the assessee shall file all necessary details and documents for the satisfaction of Ld. CIT(E) and make an effective representation.
12. Per contra, Ld. DR for revenue strongly opposed the submission of assessee. He submitted that it is the assessee who had selected/filled wrong clause/code in the initial application. He submitted that there is no infirmity, perversity or error in the order passed by Ld. CIT(E). Therefore, the impugned order must be upheld.
13. We have considered rival submissions of both sides. We find that the Legislature has introduced a new regime for granting different types of approvals in section 80G(5) through TOLA w.e.f. 01.04.2021. The provisions contain multiple clauses and sub-clauses governing different situations of ‘provisional’, ‘final’ and ‘renewal’ of approvals. The taxpayers have faced difficulties in understanding and, therefore, inadvertent errors in selecting the correct/applicable clause while filing applications are not uncommon. There are cases all over India being dealt by benches of ITAT concerning the issues of wrong selection of clause/code. We find that in the undermentioned cases, the Benches of ITAT have examined such situations and have provided appropriate relief to the assessees by adopting a pragmatic approach:
i. ITAT, Pune in Subhadra Foundation Vs. The Commissioner of Income-tax Exemption, Pune, ITA No. 1744 & 1745/PUN/2025, dated 09.09.2025
ii. ITAT, Mumbai in Rambha Charitable Trust, Mumbai Vs. Commissioner of Income-tax, ITA No. 5111/Mum/2024, order dated 29.11.2024
iii. ITAT, Kolkata in North Eastern Social Research Centre Vs. CIT(Exemption), Kolkata, ITA No. 741/Kol/2024, order dated 09.07.2024
iv. ITAT, Indore in Balaji Gau Sarakshan Sansthan Vs. CIT(Exemption), Bhopal, ITA No. 887 & 890/Ind/2025
14. These decisions consistently hold that an inadvertent selection of an incorrect clause/code, by itself, constitutes a procedural lapse and should not defeat a substantive claim for registration or approval. For an immediate reference, we re-produce below the order of ITAT, Pune in Subhadra Foundation (supra):
“7. The ld. CIT(E) has alleged mis-representation of facts, however, ld. CIT(E) failed to substantiate it. Ld. CIT(E) failed to consider the elaborate submission filed by Assessee to establish genuineness of charitable activities. It is an admitted fact by Assessee that while filing the Form, the incorrect sub-clause was selected. However, this cannot be a grave mistake to make the Assessee ineligible for registration u/s.12A of the Act. ITAT Pune Bench in the case of National Association for the Blind Vs. CIT(Exemption)-Pune in ITA No.2389/PUN/2024 has held as under:
“6. We have heard Ld. Counsels from both the sides and perused the material available on record and also copy of case laws relied on by the assessee. We find that admittedly, the assessee trust was required to file application under clause (iii) of section 12A(1)(ac) of the IT Act but due to inadvertent error the application was filed under clause (vi) of section 12A(1)(ac) of the IT Act and for this reason alone Ld. CIT, Exemption, Pune rejected its application for registration. We find that under identical situations, a Co-ordinate Bench of this Tribunal in the case of Raj Krishan Jain Charitable Trust (supra) allowed the appeal of the assessee by observing as under:-
“9. As contended the appellant has committed a technical mistake in making the application under Section 12A(1)(ac)(ii) instead of clause (iii) of clause (ac) of sub-section (1) of section 12A of the Act. As pointed out the appellant has filed revised form 10AB for seeking registration under the correct provision i.e. Section 12A(1)(ac)(iii) which can also be considered.
10. In consonance with the decision rendered by the co-ordinate Bench, the typographical error deserves to be corrected. Accordingly, the appeal deserves to be allowed and impugned order dated 15.03.2024 of Ld. CIT(E) is liable to be set aside. Hence, the appeal is allowed and we set aside the order of Ld. CIT(E) dated 1503-2024 and remand the matter back to the file of the CIT(E) for fresh adjudication by considering amended application of the appellant under Section 12A(1)(ac)(iii) of the Act, or he can call for amended application from the appellant.
11. In the result, the appeal filed by the assessee is allowed for statistical purpose.”
7. Respectfully following the above decision passed by the Coordinate Bench of this Tribunal (supra), & considering the totality of facts of the case & in the interest of justice, we deem it proper to set-aside the order passed by Ld. CIT, Exemption, Pune and remand the matter back to him with a direction to treat the application already filed by the assessee as under clause (iii) of section 12A(1)(ac) of the IT Act instead of under clause (vi) of section 12A(1)(ac) of the IT Act and decide the same as per fact and law after providing reasonable opportunity of hearing to the assessee. The assessee is also hereby directed to respond to the notices issued by Ld. CIT, Exemption, Pune in this regard and produce supporting documents/evidences in support of application for registration without taking any adjournment under any pretext, otherwise, Ld. CIT, Exemption, Pune shall be at liberty to pass appropriate order as per law. Thus, the grounds of appeal filed by the assessee are partly allowed.”
8. The facts of the present case and National Association for the Blind are identical, therefore, respectfully following the Co-ordinate Bench’s Decision(supra), we set-aside the order of ld. CIT(E) for de novo adjudication. Ld. CIT(E) shall provide opportunity of hearing. The Assessee shall file necessary documents before the ld. CIT(E). Accordingly, grounds of appeal raised by the assessee are allowed for statistical purpose.
9. In the result, appeal of the assessee ITA No.1745/PUN/2025 is allowed for statistical purpose”
15. The core issue arising in the present appeal stands substantially covered by the aforesaid decisions of ITAT Benches. No distinguishing feature has been brought to our notice so as to warrant a different view. Therefore, respectfully following the view taken by ITAT, Pune in Subhadra Foundation (supra) and other decisions referred to in preceding para, we are inclined to set aside the impugned order of Ld. CIT(E) for a de novo adjudication in accordance with law after permitting the assessee to rectify the applicable clause/code, if so required, and thereafter examine assessee’s application on merits without being influenced by the observations recorded in the impugned order. The Ld. CIT(E) shall pass a speaking order after giving necessary opportunity of hearing to assessee and the assessee shall also extend full cooperation and furnish necessary documents and explanations as may be required by Ld. CIT(E).
16. Accordingly, this appeal is allowed for statistical purposes.
ITA 231/SRT/2026:
17. This appeal is directed against the order bearing DIN: ITBA/EXM/F/EXM45/2025-26/1084897769(1) and dated 19.01.2026 passed by learned Commissioner of Income-tax (Exemption), Ahmedabad [“Ld. CIT(E)”] by which the application dated 29.09.2025 filed by assessee for approval u/s 80G(5) has been rejected.
18. During hearing before us, the Ld. AR for assessee prayed for not pressing this appeal.
19. Ld. DR for revenue does not have any objection against prayer of Ld. AR.
20. Accordingly, this appeal is dismissed as not-pressed.
21. In result, ITA 230/SRT/2026 & 868/SRT/2026 are allowed for statistical purposes and ITA 231/SRT/2026 is dismissed.
Order pronounced in open court on 30/10/2026