
Gujarat Housing Umarwada Urban Co-Op. Credit Society Limited Vs DCIT (ITAT Surat)
Interest and Dividend from Cooperative Banks Qualify under Section 80P(2)(d): Surat ITAT Follows Jurisdictional Precedent
Background
The Surat Tribunal allowed deduction under Section 80P(2)(d) on interest and dividend received from cooperative banks, following its earlier decision in the assessee’s own case and the jurisdictional Gujarat High Court precedent.
Before deciding the substantive issue, the Tribunal also condoned a delay of 751 days in both appeals, accepting the society’s explanation concerning disruption in the management of its tax affairs.
The appeals challenged separate CIT(A) orders dated 17 October 2023. For Assessment Year 2014–15, the assessment had been passed under Section 143(3) read with Section 263. For Assessment Year 2017–18, it had been completed under Section 143(3).
Explanation for the Delayed Appeals
The society supported its condonation applications with an affidavit from its President, Shri Suresh Chandra Pranlal Dave.
The affidavit explained that taxation matters had previously been handled by the former President, who was removed by the District Registrar of Cooperative Societies in June 2022. The employee assisting him with tax matters left the society in May 2023 and subsequently went abroad.
According to the affidavit, these developments created a gap in responsibility for taxation matters. The incoming President was occupied with administrative difficulties arising from the management transition and was not initially attending to tax proceedings.
The adverse appellate order came to his attention in December 2025, when he enquired about a pending refund and consulted the Chartered Accountant. The necessary papers were thereafter collected, and the appeals were filed in January 2026.
The Revenue opposed condonation, pointing out that the society had participated in the first appellate proceedings but nevertheless delayed approaching the Tribunal.
Tribunal’s Approach to Condonation
The Tribunal accepted that the circumstances explained in the affidavit constituted sufficient cause, noting the absence of contrary facts or material.
It referred to Section 253(5), which permits admission of a delayed appeal where the Tribunal is satisfied that sufficient cause prevented its presentation within the prescribed period.
Relying on Collector, Land Acquisition v. Mst. Katiji, the Tribunal adopted a justice-oriented approach, recognising that substantial justice should prevail over technical considerations where the circumstances justify relief.
It also referred to Inder Singh v. State of Madhya Pradesh, 2025 LiveLaw (SC) 339, where the Supreme Court condoned a substantial delay while emphasising that meritorious adjudication should not be obstructed merely by limitation when sufficient cause exists.
Considering the explanation, supporting material and meritorious nature of the disputes, the Tribunal condoned the delays and admitted both appeals.
Interest and Dividend in Dispute
For Assessment Year 2014–15, the society claimed deduction on ₹22,20,971, representing interest on fixed deposits with Surat District Co-operative Bank.
For Assessment Year 2017–18, the disputed amount was ₹94,35,439, comprising interest of ₹94,31,629 on fixed deposits with Surat District Co-operative Bank and dividend of ₹3,810 from cooperative banks.
The lower authorities denied deduction by relying on the Karnataka High Court’s decision in PCIT v. Totagars Co-operative Sale Society, (2017) 83 taxmann.com 140.
The assessee submitted that the same issue had already been decided in its favour for Assessment Year 2020–21 in ITA No. 1050/SRT/2024, order dated 10 December 2024. It requested that the earlier decision be followed.
Earlier Decision and Jurisdictional Precedent
The Tribunal reproduced the relevant portion of its earlier order in the assessee’s own case.
That order had considered the Karnataka High Court decision relied upon by the Revenue and followed the consistent Surat Tribunal view favouring deduction under Section 80P(2)(d).
The cited decisions included Althan Bhatar Co-operative Credit Society Limited v. ACIT and Vishal Co-operative Housing Services Society Limited v. ITO. The reasoning was that cooperative banks are primarily cooperative societies, and interest earned by an eligible cooperative society on deposits with such banks qualifies under Section 80P(2)(d).
Crucially, the earlier order relied on the Gujarat High Court’s decision in Surat Vankar Sahakari Sangh Limited v. ACIT. It held that the jurisdictional High Court precedent was binding on the Surat Bench, notwithstanding the contrary Karnataka High Court decision cited by the Department.
Finding no reason to depart from its own earlier adjudication, the Tribunal directed the AO to allow the deduction in both years.
Decision
Both appeals were allowed on merits. The Tribunal directed allowance of deduction under Section 80P(2)(d) for ₹22,20,971 in Assessment Year 2014–15 and ₹94,35,439 in Assessment Year 2017–18.
This was substantive relief, rather than a remand for further examination.
Author’s Comments
The decision reinforces the importance of jurisdictional precedent in an area where High Courts have expressed differing views. The Surat Bench followed the Gujarat High Court position and its earlier order in the same assessee’s case.
For taxpayers in Karnataka, however, the order should not be presented as displacing the Karnataka High Court decision. A favourable Tribunal ruling from another jurisdiction does not override the applicable jurisdictional High Court precedent.
The condonation finding is equally fact-dependent. The Tribunal accepted a supported explanation concerning management disruption; it did not hold that a lengthy delay must invariably be excused merely because the substantive claim appears strong.
Cases Discussed
Inder Singh v. State of Madhya Pradesh, 2025 LiveLaw (SC) 339 (Supreme Court) — Relied upon for condonation of delay and examination of meritorious disputes.
The Gujarat Housing Umarwada Urban Co-operative Credit Society Limited v. DCIT, ITA No. 1050/SRT/2024, order dated 10.12.2024 (ITAT Surat) — Earlier decision in the assessee’s own case followed on Section 80P(2)(d).
Althan Bhatar Co-operative Credit Society Limited v. ACIT, ITA No. 143/SRT/2024 (ITAT Surat) — Considered through the earlier coordinate Bench order.
Vishal Co-operative Housing Services Society Limited v. ITO, ITA No. 886/SRT/2023, dated 22.02.2024 (ITAT Surat) — Followed in the quoted precedent concerning interest from co-operative banks.
PCIT v. Totagars Co-operative Sale Society, (2017) 83 taxmann.com 140 (Karnataka High Court) — Relied upon by Revenue; not followed in preference to jurisdictional precedent.
Surat Vankar Sahakari Sangh Limited v. ACIT, 421 ITR 134 (Gujarat High Court) — Treated as binding jurisdictional precedent.
Collector, Land Acquisition v. Mst. Katiji and Others, AIR 1987 SC 1353; (1987) 2 SCC 387 (Supreme Court) — Relied upon for justice-oriented condonation of delay.
FULL TEXT OF THE ORDER OF ITAT SURAT
The captioned two (2) appeals are filed by assessee, the details are as under:
(i) ITA 45/SRT/2026 is directed against the order of first-appeal dated 17.10.2023 passed by learned Commissioner of Income-tax (Appeals), NFAC, Delhi [“Ld. CIT(A)”], which in turn arises out of assessment-order dated 27.09.2019 passed by learned ACIT, Circle-1(2), Surat u/s 143(3) r.w.s. 263 of the Income-tax Act, 1961 [“the Act”] for Assessment-Year [“AY”] 2014-15.
(ii) ITA 46/SRT/2026 is directed against the order of first-appeal dated 17.10.2023 passed by learned Ld. CIT(A), which in turn arises out of assessment-order dated 20.11.2019 passed by Ld. AO u/s 143(3) of the Act for AY 2017-18.
2. Since these appeals involve identical issues, they were heard together at the request of parties and are being disposed of by this single order for the sake of convenience, brevity and clarity.
3. The registry has informed that both of these appeals are delayed by 751 days and therefore time-barred. Ld. AR for assessee submitted that the assessee has filed applications requesting for condonation of delays, supported by affidavit of Shri Suresh Chandra Pranlal Dave, President of assessee-society. The affidavit so filed is scanned and re-produced below for an immediate reference:
Affidavit for condonation of delay
I, Shri Sureshchandra Pranlal Dave an adult, residing at Surat, and on behalf of The Gujarat Housing Umarwada Urban Co. Op. Credit Society, Limited situated at 8, 173 to 176 Gujarat Housing Board Nr. Bombay Market Umarwada, Surat-395010 as President do hereby state and affirm as under.
That I am looking after affairs of the above society. It is further declared that what in stated above is true.
That during AY 2014-15 relevant to financial year 2013-14, we had received CIT(A)’s, order dated 17.10.23 bearing no. ITBA/NFAC/S/250/2023-24/1057122433(1). The above order was be served in October-23. This appeal need to be filed within 60 days of receipt.
It is further submitted that the financial matters in particular with regard to taxation was looked after by Shri Hemanthbhai Jeevabhai Kanani, the then president of the society. He was a president upto 27.06.22. He was dismissed by District Registrar, Co-operative Society, Surat vide Order no. 173/2022/1664 dated 27.06.22. Copy of dismissal order by the District Registrar is enclosed as a part of this Affidavit.
He was assisted by Ketanbhai Balvantbhai Patel who was relieved from his job in May 2023. He went abroad. He was also looking after taxation matter. He left Canada on employment visa and therefore his services to the society were not available. The immigrant visa granted by Canadian Government is also enclosed as a part of Affidavit.
There was a vacuum between 2022 to 2025. I joined as President in July 22 and there was a heavy pressure of work in the society. The work load consisted of pressure from Registrar as well as members. It took time to settle down various issues which arose on account of dismissal of past President. Further I was not looking after taxation matters. There was a bona fide and genuine reason during 2024 and 2025.
There was a vacuum between 2022 to 2025. I joined as President in July 22 and there was a heavy pressure of work in the society. There was no knowledge with regard to Appellate order passed in October 2023. It came to the knowledge of the society only in December 2025. There is no intention to file the Appeal late. It is requested that there being no intention laches on the part of society, the Condonation of Appeal by approximately 760 days.
In between period, nobody from the society was looking after the income tax matter. I started looking after the matter sometimes in December 2025 and asked about the refund not received for the above year of Rs. 13727/-. I enquired with the CA and I was told that demand is outstanding of Rs. 1150850/- and the matter is decided by CIT(A)’s against the society. He also told me that time for filing second Appeal had expired two years back. Once I came to such mistake committed by the Society, I collected the papers in December 2025. Thereafter, the paper book and Appeal memo were prepared and the Appeal was filed immediately on 20.01.26.
There is no intention of the Society to file the Appeal late because it cost substantially to the society. The society does not benefit anything for filing Appeal late but substantial amount of tax liability arises instead of refund due to the society.
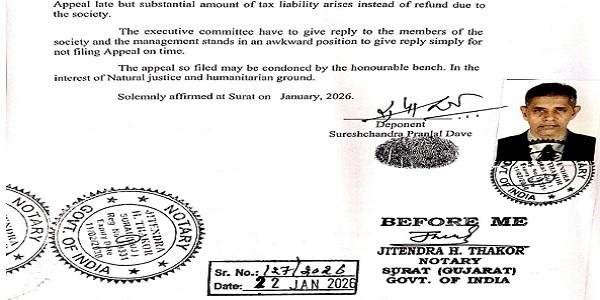
4. Ld. AR narrated the averments made in above affidavit and supported the same with reference to the documents filed in Paper-Book. Ld. AR thereafter submitted that the delay was due to “sufficient cause” as explained in the affidavit. He submitted that the delay was not intentional and the assessee did not have any malafide intention. He also submitted that the cases of assessee are meritorious. Accordingly, he requested for condonation of delay.
5. Ld. DR for revenue submitted that the assessee has participated in first appellate proceedings before Ld. CIT(A) and still made inordinate delay in filing these appeals to ITAT against the orders of Ld. CIT(A). He submitted that the delay should not be condoned.
6. We have considered assessee’s explanation and in absence of any contrary fact or material on record, the circumstances narrated by President of assessee-society in above affidavit constitute a “sufficient cause”. We find that section 253(5) of the Act prescribes thus:
“(5) The Appellate Tribunal may admit an appeal or permit the filing of a memorandum of cross-objections after the expiry of the relevant period referred to in sub-section (3) or sub-section (4), if it is satisfied that there was a sufficient cause for not presenting it within that period”.
Further, long back the Hon’ble Supreme Court has settled in Collector, Land Acquisition Vs Mst. Katiji and others 1987 AIR 1353, 1987 2 SCC 387 that whenever “substantial justice” and “technical considerations” are opposed to each other, the cause of “substantial justice” must be preferred by adopting a justice-oriented approach.
In a recent judgement in the case of Inder Singh Vs. The State of Madhya Pradesh reported in 2025 LiveLaw (SC) 339, the Hon’ble Supreme Court has condoned delay of 1,537 days while holding so:
“14. There can be no quarrel on the settled principle of law that delay cannot be condoned without sufficient cause, but a major aspect which has to be kept in mind is that, if in a particular case, the merits have to be examined, it should not be scuttled merely on the basis of limitation.”
7. Thus, taking into account the facts of case, the reasoning advanced by assessee, the meritorious nature of cases, the provision of section 253(5) and the decisions of Hon’ble Supreme Court, we take a judicious view, condone delays and admit these appeals.
8. The assessee has raised following grounds in these appeals:
AY 2014-15:
1. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in confirming addition of Rs 2220971/-.
2. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in not allowing deduction under section 80P(2)(d) as claimed in the return of income.
3. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in not granting deduction in respect of interest received from Co. Op Bank.
4. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in not appreciating that there are various decision in favor of the appellant including honorable bench decided in favor of the appellant on the same issue in Appeal no 1050/SRT/2024 wherein it was held that interest from Surat District Co-operative bank is eligible for deduction u/s 80P(2)(d).
5. On the facts and circumstances of the case, the appellant request the honorable bench to allow condonation of appeal for which separate affidavit is filed.
6. The appellant reserves right to add, alter, vary any or all grounds of appeal.
AY 2017-18:
1. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in confirming addition of Rs. 9435439/-.
2. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in not allowing deduction under section 80P(2)(d) as claimed in the return of income
3. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in not granting deduction in respect of Interest and Dividend received from Co. Op. Bank.
4. On the facts and circumstances of the case, the learned Commissioner of Income tax (Appeals) has erred in not appreciating that there are various decision in favor of the appellant including honorable bench decided in favor of the appellant on the same issue in Appeal no. 1050/SRT/2024 wherein it was held that interest or dividend from Surat District Co-operative bank is eligible for deduction u/s 80P(2)(d).
5. On the facts and circumstances of the case, the appellant request the honorable bench to allow condonation of appeal for which separate affidavit is filed.
6. The appellant reserves right to add, alter, vary any or all grounds of appeal
9. Thus, the assessee is claiming that the Ld. CIT(A) has erred in confirming the addition of Rs. 22,20,971/- in AY 2014-15 and Rs. 94,35,439/- in AY 2017-18.
10. Ld. AR at first referred the orders of lower authorities in both years. He demonstrated that in AY 2014-15, the assessee claimed deduction of Rs. 22,20,971/- u/s 80P in respect of interest on FDRs from Surat District Co-operative Bank. Further, in AY 2017-18, the assessee claimed deduction of Rs. 94,31,629/- u/s 80P in respect of interest on FDRs from Surat District Co-operative Bank (+) dividend of Rs. 3,810/- from co-operative banks.
11. Thereafter, Ld. AR submitted that the interest and dividend earned from co-operative banks is eligible for deduction u/s 80P(2)(d). However, the lower authorities have denied deduction to assessee on the basis of PCIT Vs. Totagars Co-operative Sale Society (2017) 83 taxmann.com 140 (Kar). Ld. AR submitted that the issue has been decided by co-ordinate bench of ITAT, Surat in assessee’s own case for AY 2020-21 in ITA No. 1050/SRT/2024, copy of order of ITAT dated 10.12.2024 is placed in case file. According to Ld. AR, the co-ordinate bench has considered various decisions including the decision in Totagars Co-operative Sale Society (supra) relied upon by lower authorities and has taken a view in favour of assessee. Ld. AR requested to follow the pre-existing order of co-ordinate bench in assessee’s own case and allow the claim of assessee in present appeals.
12. Ld. DR for revenue relied upon the orders of lower authorities and contended that the impugned additions/disallowances made by AO must be upheld.
13. We have considered rival submissions of both sides. At first, we re-produce the relevant portion of the order of co-ordinate bench for an immediate reference:
“4. We have considered the rival submissions of both the parties and have gone through order of lower authorities carefully. We have also deliberated the case law relied upon by both the parties. We find that Ld. AR of the assessee has made a limited prayer about deduction under section 80P(2)(d) of the Act which has been mentioned by Assessing Officer in para-10 of assessment order i.e., interest earned from co-operative bank. We find that ground of appeal raised by assessee is squarely covered by a series of decisions of this co-ordinate Bench of this Tribunal even after considering the decisions of Hon’ble Karnataka High Court in the case of Totagars Co-operative Sale Society (supra) relied by Ld. Sr-DR for the Revenue.
5. We find that in Althan Bhatar Co-operative Credit Society Ltd. Vs ACIT in ITA No. 143/Srt/2024, this combination on similar contention of the parties passed the following order;
“7. We have considered the rival submissions of both the parties and perused the orders of the lower authorities carefully. The dispute relates to deduction claimed under section 80P(2)(d) of the Act with regard to interest earned on fixed deposit with Surat District Co-operative Bank. We find that issue related with the deduction under section 80(P)(2)(d) is squarely covered by the series of decisions of jurisdictional High Court in Surat Vankar Sahakari Sangh Ltd. vs. ACIT (supra) as well as by decisions of this Tribunal in favour of assessee including in the case of Vishal Co-operative Housing Services Society Limited vs. ITO, in ITA No.886/SRT/2023, dated 22.02.2024 (Surat-Trib.), wherein it was held that Co-operative Banks are primarily the Co-operative Society and the interest earned on deposit with Co-operative banks are eligible for deduction under section 80P(2)(d) of the Act. Similar, view was taken in assesses own case for AY 2014-15 in ITA No. 151/SRT/2019, dated 31.03.2022. Having gone through the order of Co-ordinate Bench (supra), we see no reason to take a different view from the view taken by the Co-ordinate Bench (supra).”
8. Considering the aforesaid consisting decision, which is followed in a series of decisions by this co-ordinate Bench of this Tribunal and respectfully following the said decisions, we direct the Assessing Officer to delete the deduction under section 80P(2)(d) of the Act. So far as reliance on the decision of Hon’ble Karnataka High Court in case of PCIT vs. Totagars Co-operative Sale Society (supra) is concerned, we find that the decision of Jurisdictional High Court in Surat Vankar Sahkari Sangh (supra) has binding precedent on this bench.
9. In the result, the grounds of appeal raised by the assessee is allowed.”
10. Respectfully following above decision of the co-ordinate Bench rendered in assessee’s own case, we direct the Ld. AO to allow the deduction claimed by the assessee u/s 80P(2)(d) of the Act in both the assessment years under consideration. Accordingly, the grounds raised by assessee are allowed.
11. Resultantly, these appeals are allowed.
Order pronounced by putting up on notice board as per proviso to Rule 34(4) of ITAT Rules, 1963 on 07/10/2026






