Kanzeon Public Charitable Trust Vs Union of India (Madras High Court)
FCRA Registration Requires Correct Disclosure of Activities; Religious Character Alone Is Not a Disqualification
Background of the Dispute
Kanzeon Public Charitable Trust, established in 2021 and registered under Sections 12AB and 80G of the Income-tax Act, 1961, applied for FCRA registration. The trust operated a Zen Meditation Centre at Kodaikanal. Its application was rejected by the Central Government, leading to an appeal under Section 31(2) of the FCRA.
The trust contended that Zen meditation belonged to the Dhyana tradition and that its activities could not be classified as religious. It relied principally on Arsha Vidya Parampara Trust v. Union of India, along with decisions concerning charitable and religious institutions, including Dawoodi Bohra Jamat, Rajneesh Foundation, Patanjali Yogpeeth and Radhasoami Satsang.
The Government defended the rejection, maintaining that the trust conducted religious programmes and had incorrectly represented the nature of its organisation.
Zen Meditation Could Not Escape Religious Classification
The Court examined the disclosure requirements under Rule 9 of the Foreign Contribution (Regulation) Rules, 2011 and Form FC-3A. The application requires an organisation to identify itself under the religious, cultural, economic, educational or social category. Religious applicants must further disclose their religious classification.
The Court accepted the authority’s view that Zen Buddhism is a variant of the Mahayana Buddhist school. Applying the reasoning in Commissioner, HR&CE v. Shirur Mutt, concerning religious denominations and their constituent sects, it held that Buddhist schools fall within the broader umbrella of Buddhism.
Accordingly, the trust’s own description of its philosophy supported its classification as a religious organisation. The rejection was sustained because the application did not correctly disclose that character.
Religious Organisations Can Apply for Registration
The Court clarified that the FCRA does not exclude religious organisations from the registration framework. An organisation having a definite religious programme can apply under Sections 11 and 12.
However, the applicant must make a full and frank disclosure. The Court emphasised that an applicant cannot conceal its religious character while seeking the benefit of registration.
In its concluding formulation, the Court stated that religious organisations whose activities do not affect the nation’s secular fabric and social amity are entitled to obtain FCRA registration, while organisations engaged in converting persons from one religious faith to another should be denied registration.
The Court expressly clarified that it was not accusing the appellant trust of having a conversion agenda.
Teaching Indian Knowledge Systems Stands on a Different Footing
The Court distinguished religious programmes from the systematic teaching of Vedanta, the Bhagavad Gita, the Upanishads, Yoga and allied Indian Knowledge Systems through structured classes, residential courses, publications, research and preservation of manuscripts.
It observed that such activities fall within the educational or cultural category, referring to their recognition under the National Education Policy, 2020. The foreign-contribution framework, according to the Court, should operate consistently with that educational policy.
The Court approved the ratio of Arsha Vidya Parampara Trust, while emphasising that activities involving worship and rituals fall within the religious category. Thus, correct classification requires attention to the organisation’s actual programmes.
No Absolute Right to Receive Foreign Contributions
Relying on Noel Harper v. Union of India, the Court reiterated that there is no vested or absolute right to receive foreign donations. Even a properly completed application does not automatically compel the authority to grant registration.
The Court accorded considerable latitude to the Government in granting or refusing registration. Nevertheless, it recognised that rejection remains open to judicial interference where discretion is exercised perversely, relevant materials are ignored, or there is non-application of mind.
The appeal was consequently dismissed without costs, and the rejection order was sustained.
Author’s Comments
The practical lesson is that registration under Sections 12AB and 80G does not settle an organisation’s classification or eligibility under the FCRA. The two statutory frameworks serve different purposes. Trusts must ensure that their objects, actual activities and disclosures in Form FC-3A are consistent.
Equally, this decision should not be presented as holding that religious trusts cannot receive foreign contributions. The Court expressly recognised their eligibility to apply. The decisive finding against this trust concerned incorrect disclosure of its religious character.
Some broader observations warrant careful consideration. The Court described the authority’s discretion as “unfettered”, but immediately recognised judicial review for perversity, disregard of relevant material and non-application of mind. Read together, those observations recognise broad discretion subject to legal scrutiny.
The judgment also contains observations concerning the founder’s faith and the origin of Zen philosophy. These should be distinguished from the narrower finding supporting the dismissal: the mismatch between the trust’s disclosed classification and the religious nature attributed to its activities. For practitioners, accurate disclosure and evidence of actual programmes remain the central compliance lessons.
Cases Discussed
- Arsha Vidya Parampara Trust v. Union of India — relied upon by the appellant and approved by the Court on judicial review of FCRA registration discretion.
- CIT v. Dawoodi Bohra Jamat — relied upon by the appellant.
- CIT v. Rajneesh Foundation — relied upon by the appellant.
- CIT v. Patanjali Yogpeeth — relied upon by the appellant.
- Radhasoami Satsang v. CIT — relied upon by the appellant.
- Lloyd Electric v. State of Himachal Pradesh — relied upon by the appellant.
- Commissioner, HR&CE v. Shirur Mutt — relied upon by the Court in discussing religious denominations and Buddhist schools.
- Noel Harper v. Union of India — relied upon for the absence of a vested or absolute right to receive foreign contribution.
- State rep. by CBI v. M. Kurian, Chief Functionary of the Cross — relied upon concerning the statutory purpose of FCRA and the requirement of frank disclosure.
FULL TEXT OF THE JUDGMENT/ORDER OF MADRAS HIGH COURT
Does one have the right to obtain a certificate of registration from the Central Government under Section 11 of the Foreign Contribution (Regulation) Act, 2010 and if so, under what circumstances ?
2. The appellant, a trust founded in the year 2021 and already registered under Section 12AB and 80G of the Income Tax Act, 1961, sought certificate of registration under the provisions of the Foreign Contribution (Regulation) Act, 2010. The appellant’s application dated 18.06.2025 was rejected vide order dated 19.11.2025. Assailing the same, this civil miscellaneous appeal came to be filed.
3. The Registry initially raised a doubt if this appeal has to be heard by a Single Judge Bench or by a Division Bench. Any appeal against an order of rejection passed under Section 12(2) of the Act is filed under Section 31(2) of the Act. It states that the person aggrieved by such rejection order may prefer an appeal to the High Court. Section 31(3) of the Act reads as follows :
“Every appeal preferred under this section shall be deemed to be an appeal from an original decree and the provisions of Order XLI of the First Schedule to the Code of Civil Procedure, 1908 (5 of 1908), shall, as far as may be, apply thereto as they apply to an appeal from an original decree.”
Rule 2(5) of the Rules of the High Court, Madras, Appellate Side, 1965 reads as follows :
“2.The following matters shall be heard and determined by a Bench of two Judges –
….
(5) Every appeal –
(a) from a decree or order of a Civil Court ;
(b) under Clause 15 of the Letters Patent;
(c) from a decree where the value of the subject-matter of the Appeal is Rs. 25, 00, 000/- (Rupees Fifteen Lakhs) or upwards;
(d) under Section 37 of the Tamil General Sales Tax Act, 1959;
(e) For an admission of an appeal in forma pauperis except that specified in Rule 2 (2) (a);
(f) of an interlocutory character in appeals and other matters pending in the Court except an application posted before the Registrar under Order II of these rules;
(g) for the admission of a proceeding falling under this rule presented after the expiry of the period allowed by the law.]”
In view of Section 31(3) of the Act, the rejection order must be treated as a civil court’s decree. Hence, it will fall within the scope of Rule 2(5)(a) of the Appellate Side Rules. Rule 2(5)(a) must be read along with Rule 2(5)(c). If the value of the subject matter of the appeal is less than Rs.25.00 lakhs, the appeal has to be listed before the Single Judge Bench. Rule 2(5) does not talk about those cases that are incapable of monetary valuation. The order impugned in this appeal is not capable of valuation. The question regarding listing may have to be determined by taking into account the overall scheme set out in the Appellate Side Rules. It is seen that appeals / applications / revision petitions / references under various special statutes are listed before the Division Bench. FCRA is a special statute. It would, therefore, be in the fitness of things and in consonance with the overall statutory scheme that an appeal under Section 31(2) of the FCRA, 2010 is also heard by a Division Bench. It is relevant to note that in the Chartered High Court of Calcutta also such appeals are listed only before the Division Bench.
4. The learned counsel appearing for the appellant submitted that the appellant trust has established a Zen Meditation Centre at Kodaikanal and that its activities cannot be labelled as religious. According to him, the issue raised in this appeal is squarely covered by the decision of the Madras High Court reported in 2025 SCC Online Mad 13781 (Arsha Vidya Parampara Trust v. UOI). He also relied on the decisions reported in (2014) 16 SCC 222 (CIT v. Dawoodi Bohra Jamat), 2005 SCC Online Bom 867 (CIT v. Rajneesh Foundation), 2017 SCC Online Del 11398 (CIT v. Patanjali Yogpeeth), (1991) Suppl.2 SCR 312 (Radhasoami Satsang v. CIT) and (2015) 10 SCR 362 (Lloyd Electric v. State of Himachal Pradesh). The stand of the appellant is that they are not a religious organisation, while according to the respondent, they are engaged in religious programs. The appellant’s counsel waxed eloquent on the good impact that Zen Meditation practices have on oneself. Such practices belong to the Dhyana tradition of this nation and they should not be seen as religious. The learned counsel prayed that the order impugned in this appeal may be set aside.
5. Per contra, the learned Senior Standing Counsel submitted that the impugned order is well reasoned and that it does not call for interference. He added that the policy of the Government of India is to check the inflow of foreign funds that may be deployed for carrying out conversion and other activities which would harm the secular fabric of the country. He pressed for dismissal of this appeal.
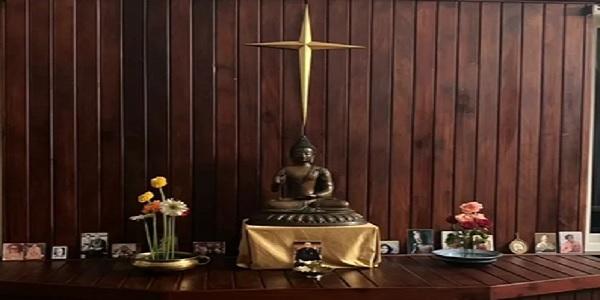
6. We carefully considered the rival contentions and went through the materials on record. The very word “Zen” has something catchy about it. There are several cult books on this theme. Many a celebrity has endorsed Zen. Anyone in pursuit of ultimate wisdom and enlightenment cannot ignore Zen. We wondered as to why a person treading the Zen path should be denied FCRA registration. At this stage, the learned standing counsel pointed out that the author of the trust and the moving spirit behind the appellant organisation is an ordained Christian priest. He is addressed as “Rev.Fr.Ama Samy SJ”. One cannot forget the fact that Christianity is a messianic religion. Their theological and religious mission is to bring everyone within the fold of Jesus Christ. There is a saying “a leopard will not change its spots”. Unlike Hinduism which is inclusive, the Abrahamic religions are inherently exclusive. The devout Jews, Christians and Muslims believe that theirs is the one true and complete revelation because that is what their Holy books say of themselves. With this nagging doubt, we stepped into the appellant’s website. We came across the following motif that has been prominently installed in the meditation centre :
7.We will now stop for a moment and see what the rules say regarding the procedure for registration. Rule 9 of FCR Rules, 2011 states that the application must be in Form FC-3A. Form FC-3A requires the applicant to disclose the nature of the organisation. It must be indicated under which of the following heads, they can be categorised :
a) religious b) cultural c) economic d) educational and e) social If the applicant is a religious person/association, it must be mentioned under which of the following classification they would fall :
“a) Hindu b) Sikh c) Muslim, d) Christian e) Buddhist f) others.”
The appellant trust claims to subscribe to Zen Buddhist philosophy. It is not for us to doubt if the said claim is genuine or spurious. A strong argument is being made that the native and local motifs are appropriated by the messianic religions so that the ground is prepared for eventual take over. It is not within our province to engage in such debates. They have to be waged elsewhere. But on the own showing of the appellant, they are a religious organisation. The reason set out in the impugned order is eminently sustainable. The authority rightly states that Zen Buddhism is a variant of Mahayana Buddhist School. The Hon’ble Supreme Court in Commissioner, HR&CE v. Shirur Mutt (1954) 1 SCC 412, observed that each one of the sects or the sub-sects of the Hindu religion are to be called as religious denominations. Applying the same logic, every Buddhist school will come under the broad umbrella of Buddhism. Zen can be no exception. Since the appellant’s application did not correctly identify its nature as religious, the application was rightly negatived.
8. The appellant need not have been so coy. Section 12 of the FCRA bars only an unregistered religious organisation from accepting foreign contribution. An organisation having a definite religious program is entitled to apply for a certificate of registration from the central government under Sections 11 and 12 of the Act. But one has to make a clean breast of everything. One cannot keep any card up one’s sleeve. This is no game of hide and seek.
9. It is necessary to make a clear distinction between a religious organisation and a cultural or educational entity. An organisation primarily engaged in the systematic teaching of Vedanta, the Bhagavad Gita, the Upanishads, Yoga and allied Indian Knowledge Systems through structured classes, residential courses, publications, research and preservation of manuscripts cannot to be classified as religious institutions. Indian Knowledge Systems would fall under the category of education or culture. The National Educational Policy, 2020 expressly provides for including IKS within the educational curriculum and specifically refers to philosophy and yoga among the fields in which such knowledge is to be taught. When NEP itself recognises these disciplines as legitimate fields of study, the foreign-contribution framework should not classify such organisations teaching the same subjects as religious. Such misclassification can have serious economic and funding consequences. The regulatory framework governing foreign contribution should operate in tandem with the New Educational Policy, 2020. Indians are now spread all over the world. The immortal novelist Raja Rao remarked that India is more an idea and not a mere territory. Indians living abroad would want to support certain cultural activities taking place within India. FCRA should not come as an obstacle. Let us take the example of Jews. The Jews were driven out of their homeland. They settled all over the world. They acted as effective pressure groups in each country where they were. The Bharatiya diaspora can play a similar role. Persons and organisations engaged in dissemination of Indian Knowledge Systems would thus stand on a different footing.
10. Zen philosophy is of Chinese origin. Organisations like the appellant trust cannot therefore claim any right to be registered under FCRA. The Hon’ble Supreme Court in Noel Harper v. UOI (2023) 3 SCC 544 made it clear that there is no vested right, much less an absolute right to accept foreign donation. The Hon’ble Supreme Court also hinted that there is a possibility of national polity being influenced by foreign contribution. They may destabilise the social order within the country. We are a pluralist nation. Unlike USA, we are not a melting pot but a salad bowl, a beautiful metaphor credited to Justice Ruma Pal. This status quo would be upset, if one religious group gains ascendency. In Kerala, one recently witnessed friction between the Christians and the Muslims. If foreign funds are freely allowed inside to facilitate conversion activities, the sovereignty of the nation would be imperilled. We specifically highlight the issue of conversion because radical Christian Institutions are notorious for indulging in such activities. We hasten to clarify that we do not accuse the appellant of having any such agenda. Section 12(4)(a)(ii) specifically refers to conversion from one religious faith to another. This provision applies to all religious organisations. A fundamentalist Hindu Organisation engaged in Ghar Wapsi cannot be registered under FCRA. The statutory regime which was put in place during UPA rule (2010) is intended to subserve secular objects.
11. Prof (Dr) P.Ishwara Bhat, a distinguished academic in his illuminating article “Balancing transnational charity with democratic order, security, social harmony and accountability: a critical appraisal of the Foreign Contribution (Regulation) Act, 2010” wrote the following :
“Globalization of charity is not a new phenomenon, but is an indispensable feature of a caring and cooperating international community, which includes individuals, organizations and states. But the values of democracy, social harmony and expressional freedom are far more superior and essential for survival of the constitutional polity. Hence, charity, in spite of its high moral ground should not have competence to subvert these values, but instead, should be complementary to them. The FCRA 2010 and its predecessor have reflected the instrumental role of transnational charity and supremacy of the democratic values. Indoctrination at the international level is encroachment of or intervention with intellectual sovereignty of the nation. But with the demise of cold war and emergence of globalization, the fear of indoctrination remains, as a paper tiger. However, being fed by FC, led by false fear and armed with borrowed ideas, chances of NPVOs acting to obstruct a developmental work may not be ruled out. Similarly, direct financial support by big nations or their bodies to public men of other nations, which had toppled the existing governments and enthroned new ones in the past, may be a potential danger. Further, transnational financial assistance to terrorism and communal disharmony threaten the health of the polity. FCRA arms the Central Government with adequate powers to deal with such contingencies. The procedural refinements and introduction of greater means of ensuring accountability of fund receivers under the new Act have added strength to support genuine charity.”
12. We hold that considerable leeway and unfettered discretion should be given to the authority in the matter of granting or refusing registration under Sections 11 and 12 of the FCRA, 2010. Of course, if the discretion is perversely exercised or the relevant materials are not taken into account or there is non-application of mind, the rejection order would certainly be interfered with by the writ court in exercise of the power of judicial review. Such an approach was adopted in Arsha Vidya Parampara Trust v. UOI (2025 SCC Online Mad 13781). We approve the ratio laid down therein.
13. The Hon’ble Supreme Court in State rep.by CBI v. M.Kurian, Chief Functionary of the Cross (2001) 4 SCC 290, while construing the repealed 1976 FCRA, observed that the entire purpose behind the Act was that the recipients of foreign contribution may not act in a manner inconsistent with the values of the sovereign republic which our founding fathers have given to us. The statutory scheme indicates the legislative intent and the purpose behind the Act and therefore, the provisions of the Act are to be construed accordingly. When the statute envisages a frank disclosure of all the details, any misrepresentation would entail rejection of the application itself. Though the applicant is engaged in religious programs, they wrongly projected themselves as non-religious. That is why, the respondent authority had to say “Illa Samy” (No Sir) to Rev.Fr.Ama Samy (which name literally translates as “Yes”).
14. Let us sum up. An application seeking FCRA registration should correctly disclose the nature of the applicant. Failure to do so will result in rejection of the application. Even if all the details are in order, the authority is still at liberty to negative the request. The decision of the authority will not be judged on a high threshold but in the light of the parameters mentioned in para 11. This is because there is no right as such to receive foreign contribution. It can at best be a privilege. The authority must however correctly classify the applicants. Persons and organisations engaged in upholding the civilisational heritage of India have to be classified as educational or cultural. If the programs of the applicant pertain to worship and rituals, they will fall under the religious category. Religious organisations, whose activities would not affect the nation’s secular fabric and social amity, are entitled to obtain FCRA registration. But organisations engaged in converting people of one religious faith to another shall be denied FCRA registration.
15. For the foregoing reasons, the order impugned in this civil miscellaneous appeal is sustained. This appeal is dismissed. No costs.