
Amrit Bottlers Private Limited Vs DCIT (ITAT Delhi)
Summary: The Delhi Bench of the Income Tax Appellate Tribunal allowed the appeal of Amrit Bottlers Private Limited for Assessment Year 2023-24 and quashed a penalty of ₹6,25,86,306 levied under Section 271AAB of the Income-tax Act, 1961. The penalty had been imposed by the Assessing Officer by order dated 30.03.2025 and was subsequently sustained by the Commissioner of Income Tax (Appeals)-24, New Delhi, in an order dated 28.10.2025. The assessee challenged the penalty principally on the legal ground that the notices initiating the penalty proceedings did not disclose the particular limb of Section 271AAB under which the penalty was proposed.
The assessee pointed to three penalty notices dated 18.07.2024, 02.09.2024 and 04.11.2024 and submitted that none of them specified the corresponding limb of Section 271AAB. It relied upon the coordinate Bench decision in DCIT Vs Sanjay Singh, ITA No. 6942/Del/2019, contending that failure to communicate the precise charge was fatal to the penalty proceedings. The Tribunal reproduced and adopted the detailed reasoning of that coordinate Bench decision, which dealt with the requirement that a penalty notice clearly communicate the statutory charge to the assessee. The reproduced discussion referred to authorities dealing both with the nature of “undisclosed income” under Section 271AAB and the invalidity of vague penalty notices.
The Tribunal applied that reasoning mutatis mutandis to the assessee’s case and concluded that the impugned penalty was not sustainable in law. The Revenue’s contentions in support of the penalty were rejected. Since the penalty was disposed of on this threshold legal issue, all remaining pleadings between the parties were treated as academic. Accordingly, the Tribunal allowed the assessee’s appeal and effectively deleted the Section 271AAB penalty of ₹6,25,86,306. The order was pronounced in open court on 17.08.2026. The official ITAT cause list independently identifies ITA No. 8941/Del/2025 as Amrit Bottlers Private Limited, AY 2023-24, before the Delhi Benches. [Income Tax Appellate Tribunal](https://itat.gov.in/public/files/upload/1779168299-EN88hfRH-CMS.pdf?utm_source=chatgpt.com)
Cases Discussed
- DCIT Vs Sanjay Singh, ITA No. 6942/Del/2019 (ITAT Delhi) — Directly relied upon and its detailed discussion reproduced. The Tribunal adopted the coordinate Bench’s reasoning that failure to specify the precise charge/limb in a Section 271AAB penalty notice is fatal to the penalty proceedings.
- Jaina Marketing & Associates Vs DCIT — Referred to in the reproduced coordinate Bench discussion on the requirement that a penalty notice specify the charge for which penalty is proposed.
- Shri Padam Chand Pungliya Vs ACIT, ITA No. 112/JP/2018 (ITAT Jaipur) — Referred to regarding the requirement that disclosed income must satisfy the statutory definition of undisclosed income for Section 271AAB penalty.
- Mahaveer Prasad Agarwal Vs DCIT, ITA No. 1218/JP/2019, order dated 02.06.2022 — Referred to in relation to a similar Section 271AAB notice.
- Shri Ashok Bhatia Vs DCIT, ITA No. 869/Ind/2018, order dated 05.02.2020 (ITAT Indore) — Referred to for the proposition concerning an unspecified charge in the penalty notice.
- PCIT Vs Kulwant Singh Bhatia — Referred to on the requirement that a penalty notice communicate a specific charge rather than use a general pro forma notice.
- CIT Vs Manjunatha Cotton and Ginning Factory — Referred to on defective penalty notices and the requirement of specificity.
- DCIT Vs R. Elangovan — Referred to in the reproduced coordinate Bench reasoning.
- Ravi Mathur Vs DCIT — Referred to in the reproduced coordinate Bench reasoning.
- Sushil Kumar Paul Vs ACIT, ITA No. 2274/Kol/2019, order dated 15.12.2022 (ITAT Kolkata) — Referred to on the requirement that a Section 271AAB notice make the proposed statutory charge clear.
- ACIT Vs Smt. Pallem Reddy Sreelakshmi, Tirupati, ITA No. 756/Hyd/2020, order dated 04.01.2022 (ITAT Hyderabad) — Referred to as another Tribunal decision taking a similar view.
FULL TEXT OF THE ORDER OF ITAT DELHI
This assessee’s appeal for assessment years 2023-24, arises against Commissioner of Income Tax (Appeals)-24 [in short, the “CIT(A)”], New Delhi’s order dated 28.10.2025, passed in order no. 10096/2022-23, involving proceedings under section 271AAB of the Income-tax Act, 1961 (hereinafter referred to as ‘the Act’).
Heard both the parties. Case files perused.
2. We now advert to the first and foremost legal issue between parties. The assessee is admittedly aggrieved against both the learned lower authorities’ action levying section 271AAB penalty of Rs. 6,25,86,306/- in its hands; in the Assessing Officer’s order dated 30.03.2025 as upheld in the lower appellate discussion.
3. That being the case, Mr. Agarwal refers to the assessee’s paperbook at pages 4 to 6 compiling the Assessing Officer’s impugned penalty notices issued on 18.07.2024, 02.09.2024 & 04.11.2024 on as many occasions nowhere specifying the corresponding limb(s) u/s 271AAB of the Act. He next quotes DCIT Vs Sanjay Singh in ITA No. 6942/Del/2019 decided on 28.11.2019 that such a failure is very much fatal to the impugned penalty; as follows: “
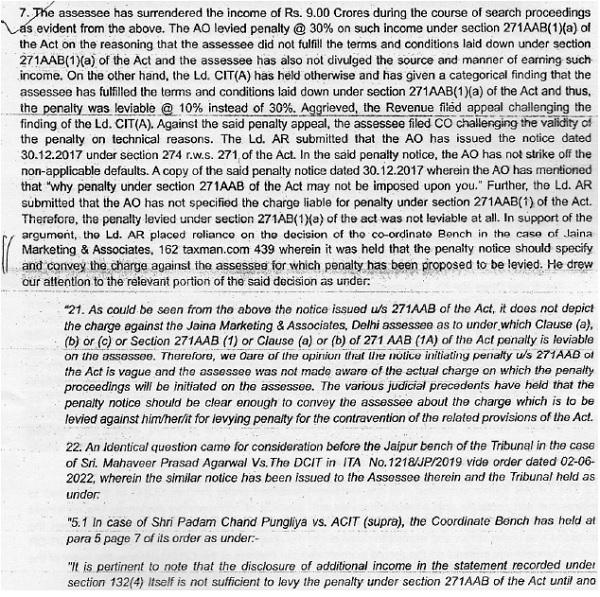
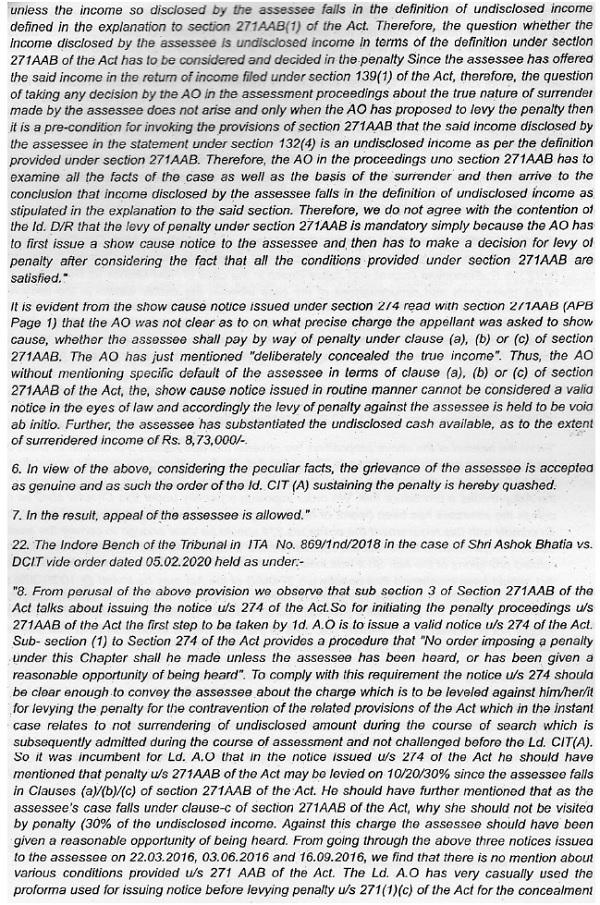
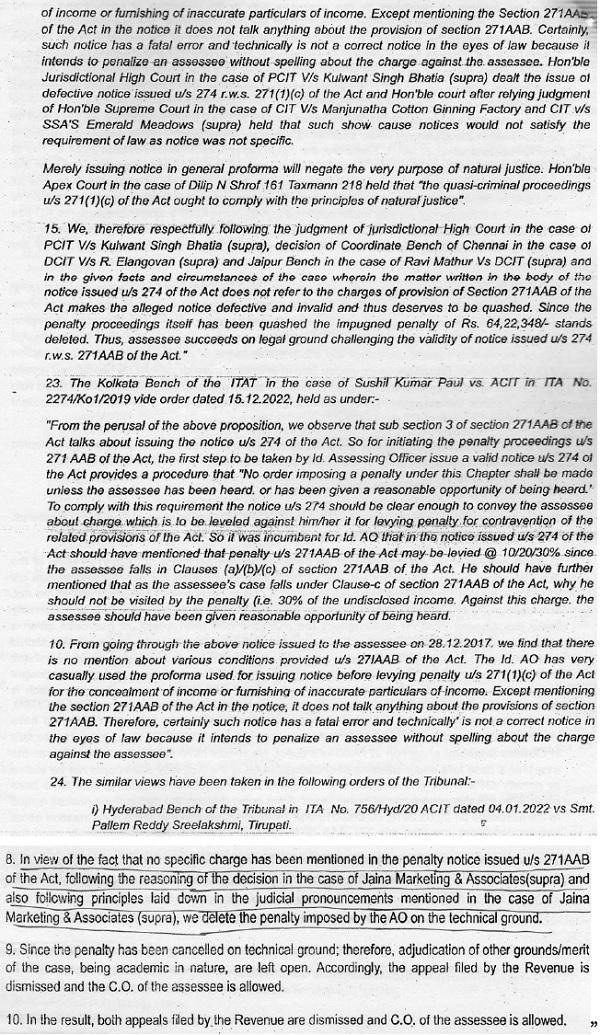
4. We adopt that the learned co-ordinate bench’s above extracted detailed discussion mutatis mutandis to conclude that the impugned penalty in the assessee’s case herein is not sustainable in law. The Revenue’s vehement contentions in support thereof are hereby rejected in very terms therefore. All other remaining pleadings between the parties stand rendered academic.
5. This assessee’s appeal is allowed.
Order pronounced in the open court on 17.08.2026.





