
Smt. Lalita Devi Vs ITO (ITAT Raipur)
Section 148A(b) Notice Giving Only Six Clear Days Invalid: ITAT Quashes Assessment
Introduction
The Income Tax Appellate Tribunal, Raipur Bench, quashed an assessment because the preceding notice under Section 148A(b) of the Income Tax Act, 1961, did not provide the assessee the mandatory minimum response period.
The notice was dated 24 February 2023, and compliance was required by 3 March 2023. Excluding both the notice date and the compliance date, the Tribunal found that the assessee had received only six clear days, against the statutory requirement of not less than seven days.
Holding the notice invalid and void ab initio, the Tribunal ruled that it could not support a valid assessment. The assessee’s appeal was consequently allowed.
Background of the Appeal
Smt. Lalita Devi challenged the order dated 7 July 2026 passed by the CIT(A), National Faceless Appeal Centre, Delhi, concerning Assessment Year 2019-20.
Before the Tribunal, the assessee raised a legal objection to the validity of the show-cause notice issued under Section 148A(b).
The challenge centred on the time allowed for responding to the notice. According to the assessee, the statutory expression “not less than seven days” required seven complete intervening days after excluding both terminal dates.
Since the notice failed this requirement, the assessee contended that the proceedings founded upon it were invalid.
The appeal was heard and decided by Shri Partha Sarathi Chaudhury, Judicial Member.
Issue Before the Tribunal
The question was whether a notice dated 24 February 2023, requiring a response by 3 March 2023, complied with the minimum period prescribed under the provision applicable to that notice.
Although the dates were seven calendar days apart, the assessee argued that this did not provide seven clear days for compliance.
The distinction concerned the method of computation: whether the notice date or response deadline could be included when determining the minimum period.
The Tribunal examined the notice and the judicial authorities addressing the meaning of the statutory wording.
Both Terminal Dates Must Be Excluded
The Tribunal held that both the date of notice and the date fixed for compliance must be excluded.
On that computation, the available intervening dates were 25, 26, 27 and 28 February, followed by 1 and 2 March—six clear days.
The Tribunal therefore found that the notice did not satisfy the statutory requirement. Its conclusion rested on the prescribed minimum opportunity itself, rather than an examination of the substantive tax dispute.
The failure to provide the required period rendered the notice invalid and bad in law.
Reliance on Earlier Raipur Bench Decision
The Tribunal relied extensively on its earlier decision in DCIT-1(1), Raipur Vs. Avani Ferro Alloys Pvt. Ltd., ITA Nos. 88 to 91/RPR/2025, dated 6 August 2026.
In that case, a notice dated 16 March 2022 required compliance by 23 March 2022. The Bench had held that the mandatory seven-clear-day period had not been provided.
That decision considered the Rajasthan High Court’s ruling in Bijendra Singh Vs. PCCIT, which applied the Supreme Court’s interpretation in Pioneer Motors (Private) Ltd. Vs. Municipal Council, Nagercoil.
The principle drawn from those authorities was that where legislation requires not less than a specified number of days, both terminal dates are excluded from the computation.
The earlier Bench decision also referred to the Karnataka High Court’s ruling in PCCIT Vs. Smt. Komarla Yogendra Keertana and the Gujarat High Court’s decision in Atul Mahavirprasad Paldecha Vs. ITO, supporting invalidation of notices that failed to provide the minimum statutory response period.
Consistent View in Other Decisions
The Tribunal additionally noted that the Raipur Bench had taken a similar view in Atal Agrawal Vs. ITO-1, Raigarh, ITA No. 231/RPR/2026, dated 3 September 2026.
It also referred to Kaizen Motoventures Private Limited Vs. ACIT-1(1), Raipur, ITA No. 409/RPR/2026, dated 22 September 2026.
Following the same reasoning, the Tribunal held that the notice issued to Lalita Devi was non-compliant with Section 148A(b).
Assessment and Subsequent Proceedings Quashed
The Tribunal concluded that an invalid notice could not give rise to a valid assessment order.
It accordingly quashed the assessment made pursuant to the defective notice and held that all subsequent proceedings were non-est in law.
Since the assessee succeeded on this legal ground, the remaining grounds became academic. The Tribunal did not adjudicate the underlying additions on merits.
Conclusion
The assessee’s appeal was allowed, with the assessment quashed because the notice provided only six clear days to respond.
The ruling highlights the significance of correctly computing the minimum response period under the provision governing the notice. A seven-day difference between the printed dates did not satisfy the requirement when both terminal dates were excluded.
The relief was final at the Tribunal stage on this legal issue; the matter was not remanded for reconsideration of the assessment.
Cases Discussed
- DCIT-1(1), Raipur Vs. Avani Ferro Alloys Pvt. Ltd. — ITA Nos.88 to 91/RPR/2025, 06.08.2026. Directly followed; seven clear days required.
- PCCIT Vs. Smt. Komarla Yogendra Keertana — (2025) 307 Taxman 106 (Kar.). High Court upheld quashing of short-period notice.
- Bijendra Singh Vs. PCCIT — (2025) 478 ITR 493 (Raj.). Both terminal dates excluded.
- Pioneer Motors (Private) Ltd. Vs. Municipal Council, Nagercoil — AIR 1967 SC 684. Supreme Court principle governing “not less than” periods.
- Atul Mahavirprasad Paldecha Vs. ITO — (2025) 307 Taxman 331 (Guj.). Seven-day statutory minimum is mandatory.
- Atal Agrawal Vs. ITO-1, Raigarh — ITA No.231/RPR/2026, 03.09.2026. Coordinate Bench decision applying the same reasoning.
- Kaizen Motoventures Private Limited Vs. ACIT-1(1), Raipur — ITA No.409/RPR/2026, 22.09.2026. Coordinate Bench decision applying the same reasoning.
FULL TEXT OF THE ORDER OF ITAT RAIPUR
The present appeal preferred by the assessee emanates from the order of the Ld.CIT(Appeals)/NFAC, Delhi dated 07.07.2026 for the assessment year 2019-20 as per the grounds of appeal on record.
2. The contention in law assailed by the Ld. Counsel for the assessee is that show cause notice u/s.148A(b) of the Income Tax Act, 1961 (for short ‘the Act’ is violative of the provision itself since the said show cause notice does not provide the assessee a clear cut 7 days time excluding the date of notice and date of compliance sought for from the assessee, therefore, such notice being void ab initio cannot set in motion a valid order of assessment and is liable to be quashed.
3. In this regard, relevant notice u/s.148A(b) of the Act, dated 24.02.2023 is extracted as follows:
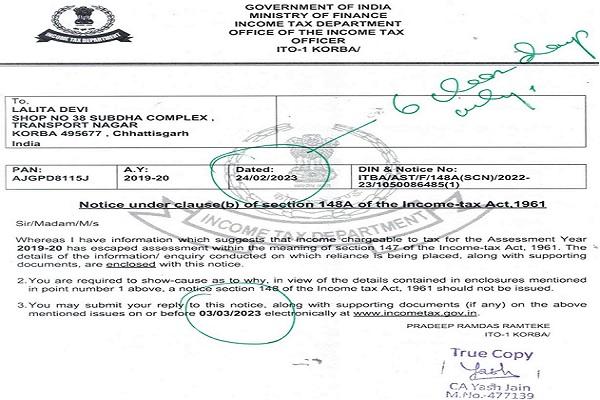
4. The date of notice is 24.02.2023 and date on which compliance sought for from the assessee is 03.03.2023 and in between, there is only 6 clear days time. However, Section 148A(b) of the Act provides that “being not less than 7 days”, which has been interpreted by various judicial forums that clear cut 7 days time has to be given to the assessee excluding the date of notice and date of compliance of the assessee. In the present case, as evident clear cut 6 days time only given to the assessee and hence, such notice u/s. 148A(b) of the Act is invalid and bad in law.
5. I find that similar issue has been dealt with by this Bench in favour of the assessee and against Revenue recently in the case of DCIT-1(1), Raipur Vs. Avani Ferro Alloys Pvt. Ltd, ITA Nos.88 to 91/RPR/2025, dated 06.08.2026 wherein it was held and observed as follows:
“60. The Ld. Counsel for the assessee submitted that the notice issued u/s 148A(b) on 16.03.2022 is void ab initio. He submitted that the notice called for a response on or before 23.03.2022 which does not constitute a clear 7 days as required by the mandatory provisions of section 148A(b). He submitted that the statutory mandate requires a period of ‘not less than seven days’ to be provided for compliance. He submitted that in computing this period, both the date of issuance and the date of compliance must be excluded. Consequently the jurisdictional notice is rendered void and all subsequent proceedings emanating from it are a ‘nullity and non-est in the eyes of law’.
61. Referring to the decision of Hon’ble Karnataka High Court in the case of PCCIT vs. Smt. Komarla Yogendra Keertana reported in (2025) 307 Taxman 106 (Kar), he submitted that the Hon’ble High Court in the said decision has held that where impugned notice issued u/s 148A(b) did not provide the assessee minimum statutory period of seven days to respond, same was rightly quashed.
62. Referring to the decision of Hon’ble Rajasthan High Court in the case of Bijendra Singh vs. PCCIT reported in (2025) 478 ITR 493 (Raj), he submitted that the Hon’ble High Court in the said decision following the decision of Hon’ble Supreme Court in the case of Pioneer Motors (Private) Ltd. vs. Municipal Counsel, Nagrecoil reported in AIR 1967 SC 684 has held that both the terminal dates have to be excluded for the purpose of complying with the requirement of words ‘not less than .. days”.
63. The Ld. DR on the other hand submitted that the Assessing Officer has issued notice u/s 148A(b) on 16.03.2022 asking the assessee to submit its details on or before 23.03.2022. Thus, a period of 7 days have been given. Therefore, the arguments advanced by the Ld. Counsel for the assessee are liable to be rejected and the notice issued is to be held as valid notice.
64. We have heard the rival arguments made by both the sides, perused the orders of the Assessing Officer and the Ld. CIT(A) / NFAC and the paper book filed on behalf of the assessee. We have also considered the various decisions cited before us. We find the Assessing Officer issued a notice under clause (b) of section 148A on 16.03.2022 by asking the assessee to submit the details in the portal on or before 23.03.2022, the details of which are as under:
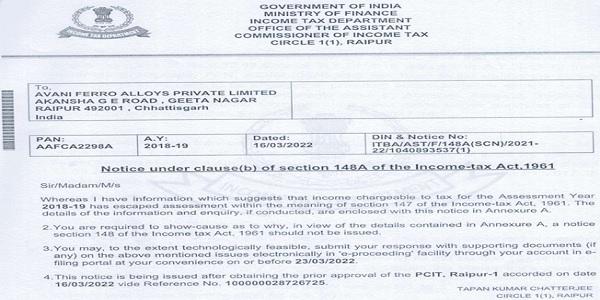
65. Under these circumstances, we have to see as to whether a period of 7 days as mandated by the provisions of section 148A(b) are fulfilled or not. We find an identical issue had come up before Hon’ble Rajasthan High Court in the case of Bijendra Singh vs. PCCIT (supra). The Hon’ble High Court in the said decision while deciding the aspect of calculating the days in a case where the provision requires a notice of ‘not less than particular days’, following the decision of Hon’ble Supreme Court in the case of Pioneer Motors (Private) Ltd. vs. Municipal Council (supra) has observed as under:
“10. Section 148A(b) of the Act requires providing opportunity of being heard to the assessee by serving upon him/her notice to show cause within such time, as may be specified in the notice being ‘not less than seven days‘ but not exceeding thirty days from the date, on which such notice is issued.
11. The aspect of calculating the days in a case where the provision requires a notice of ‘not less than particular days’, has been dealt with by the Hon’ble Supreme Court in the Pioneer Motors (Private) Ltd. vs. The Municipal Council, Nagrecoil : AIR 1967 SC 684, wherein it has, inter-alia, been laid down as under: “The words “not being less than one month” do imply that clear one month’s notice was necessary to be given, that is, both the first day and the last day of the month had to be excluded. To put it in the language used by Maxwell on Interpretation of Statutes, 10th Edition, p. 351 :- “..when…….. ‘not less than’ so many days are to intervene, both the terminal days are excluded from the computation.”
12. It has been laid down by the Hon’ble Supreme Court that both the terminal days have to be excluded for the purpose of complying with the requirement of words ‘not less than …. days “. Admittedly, in the present case, the notice dated 16.03.2022 was issued/posted on 17.03.2022 and the date fixed for response was 23.03.2022. Excluding two days i.e. the date of sending of the notice as well the last date indicated, even if the notice was received by the petitioner, the same falls short of seven days’ period, as envisaged by provisions of Section 148A(b) of the Act; and as such, for violation of mandatory provisions of Section 148A(b) of the Act, the notice issued to the petitioner cannot be sustained.”
66. We find the Hon’ble Karnataka High Court in the case of PCCIT vs. Smt. Komarla Yogendra Keertana (supra) has held that where impugned notice issued u/s 148A(b) did not provide the assessee minimum statutory period of seven days to respond, the same is liable to be quashed.
67. Similar view has been taken by Hon’ble Gujarat High Court in the case of Atul Mahavirprasad Paldecha vs. ITO reported in (2025) 307 Taxman 331 (Guj). Since in the instant case the Assessing Officer has not given the mandatory period of clear 7 days for replying to the notice issued under clause (b) of section 148A, therefore, such notice being not in accordance with law is liable to be quashed. We, accordingly, hold that the notice issued by the Assessing Officer on 16.03.2022 under clause (b) of section 148A is not in accordance with law and therefore, the same is quashed. Since the assessee succeeds on this legal ground, the appeal filed by the Revenue becomes infructuous and the same is dismissed.
68. In the result, all the 4 appeals filed by the Revenue are dismissed”
6. Similar view has been held by this Bench in the cases of Atal Agrawal Vs. ITO-1, Raigarh (C.G.), ITA No.231/RPR/2026, A.Y.2018- 19, dated 03.09.2026 and Kaizen Motoventures Private Limited Vs. ACIT-1(1), Raipur (C.G.), ITA No. 409/RPR/2026, dated 22.09.2026.
7. Resultantly, following the same parity of reasoning and upon examination of the notice u/s.148A(b) of the Act, I hold that the said notice being non-compliant of the said legal provision itself is invalid, void ab initio and such invalid, void ab initio notice cannot give rise to a valid assessment order. Hence, the assessment order in pursuant of such void ab initio notice is therefore, quashed. That all other subsequent proceedings are non-est as per law. Rest other grounds stands academic only.
8. In the result, appeal of the assessee is allowed.
Order pronounced in open court on 26th day of October, 2026.



