
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Section 153A Assessment Quashed – Mechanical Approval U/s 153D Held Invalid
Addition U/s 69A Deleted – Third Party Statement Without Corroboration Insufficient
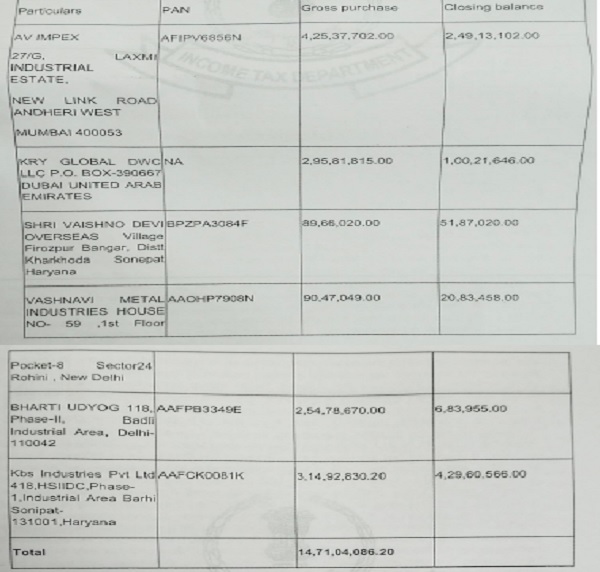
Bogus Purchase Addition Restricted to 10% – CIT(A) Relief Upheld
Reassessment Quashed – Notice U/s 148 Issued Before Approval & Mechanical Sanction U/s 151
Reopening Upheld but Addition Restored – Non-Speaking Order on Cost of Improvement
TDS Default u/s 201 – Matter Remanded for Verification of Payees’ Tax Payment
Loan Repayment Not Taxable U/s 68 & 14A Disallowance Restricted to Actual Expenditure
Addition u/s 69A Partly Sustained – Disallowance Restricted to 10%
Section 153C Additions Deleted – Hazir Johri Software Entries Held Unreliable Without Corroboration

Penalty U/s 271(1)(c) Deleted — Defective Notice U/s 274 Without Specific Charge Invalidates Penalty: ITAT Mumbai

Section 143(1) Adjustment without Notice Invalid – Carry Forward of Loss & Unabsorbed Depreciation Allowed by ITAT Kolkata
Interest Expenditure U/s 57 Allowed — Nexus Established through Computation
Reassessment Quashed — Approval by Wrong Authority U/s 151(ii) Invalidates Notice u/s 148 Entire Proceedings: ITAT Mumbai
Deemed Dividend U/s 2(22)(e) Largely Deleted & Sec.54 Deduction Allowed
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

