
Chat Computers Limited Vs DCIT (ITAT Mumbai)
Mumbai ITAT Deletes ₹23.98 Crore Section 68 Addition: Once Identity, Creditworthiness and Genuineness Are Proved, Share Capital Cannot Be Taxed as Unexplained Cash Credit
The Mumbai ITAT deleted the addition of ₹23.98 crore made under Section 68 in respect of preference share capital received from various Kolkata-based companies, holding that the assessee had discharged the initial burden of proving the identity of the investors, their creditworthiness and the genuineness of the transactions through extensive documentary evidence.
The assessee had issued cumulative redeemable preference shares and received ₹28.73 crore, comprising face value and share premium, from 37 investor companies. Pursuant to earlier Tribunal directions, an amount of ₹4.75 crore received from five companies had already been accepted as genuine. In the fresh assessment, the Assessing Officer treated the balance ₹23.98 crore as unexplained cash credit under Section 68, relying heavily on investigation reports alleging that the investor companies were accommodation entry providers.
Before the Tribunal, the assessee pointed out that identical transactions involving many of the same investor companies had already been accepted as genuine in its own case for subsequent years and also in connected group cases. Detailed records such as share application forms, board resolutions, certificates of incorporation, PAN details, income-tax returns, audited financial statements, bank instruments and financial strength of the investor companies had been furnished. The material showed that the investors possessed substantial capital, reserves and financial resources to make the investments.
The Tribunal noted that the Revenue had primarily relied on generalized investigation reports and statements without bringing any direct evidence linking the assessee to any accommodation entry arrangement. It further observed that the assessee had already produced substantial documentary evidence establishing the three essential ingredients required under Section 68, namely identity, creditworthiness and genuineness.
Following the decisions rendered in the assessee’s own cases and related matters involving similar preference share transactions, the ITAT held that the assessee had successfully discharged the burden cast upon it under Section 68. Once such evidence was produced, the addition could not be sustained merely on the basis of suspicion or general allegations regarding Kolkata-based investment companies.
Accordingly, the Tribunal held that the addition of ₹23.98 crore under Section 68 was unsustainable in law and directed its deletion, reiterating that documented share capital transactions supported by credible evidence cannot be treated as unexplained cash credits merely on the strength of investigation reports and presumptions.
FULL TEXT OF THE ORDER OF ITAT MUMBAI
The captioned appeal is preferred by the assessee, against the order of the Commissioner of Income Tax Appeals – 49, Mumbai [in short, “the Ld. CIT(A)”], dated 31.12.2024 for the assessment year 2005-06, arises from the assessment order under section 143(3) r.w.s. 254 of the Income Tax Act, 1961 [in short, “the Act”] dated 23.03.2016, passed by Deputy Commissioner of Income Tax, Central Circle 7(1), Mumbai [in short, “the Ld.AO”]. The grounds of appeal raised by the assessee, are as under:
“The Commissioner of Income-tax (Appeals)-49, Mumbai (hereinafter referred to as the CIT(A)) erred in upholding the action of the Deputy Commissioner of Income-tax, Central Circle 7(1), Mumbai (hereinafter referred to as the Assessing Officer) in making an addition of a sum of Rs 23,98,00,000, being amount received on allotment of preference share capital, on the ground that the share application money is not genuine and the same is treated as cash credit under section 68 of the Act.
The appellants contend that on the facts and in the circumstances of the case and in law, the CIT(A) ought not to have upheld the action of the Assessing Officer in making the impugned addition under section 68 of the Act inasmuch as the provisions of the section, in terms, are not applicable to the facts of the case.
The appellants further, contend that Assessing Officer erred in not following the directions of the Tribunal in their order dated 24th September, 2014; accordingly, the impugned addition requires to be deleted.
The appellants further, contend that the CIT(A) ought not to have upheld the action of the Assessing Officer inasmuch as he has violated the principles of natural justice in not furnishing the various statements on oath of directors of various companies, being preference shareholders of the appellant-company before passing the impugned assessment order.
The appellants further, contend that CIT(A) ought not to have upheld the action of the Assessing Officer in thrusting upon the appellants to produce the directors of the shareholder-companies for cross examination; the appellants submit that it is the obligationof the Assessing Officer to produce the said directors for cross examination, being the witness of the Revenue.
The appellants further, contend that the CIT(A) erred in upholding the action of the Assessing Officer inasmuch as he relied on the reports of examination of the directors of shareholder-companies by other officers of the Department instead of himself examining the said directors.”
2. Brief facts of the case, described in the order of Ld. CIT(A) are extracted as under:
“The appellant e-filed a return for the A.Y. 2005-06 on 31/10/2005 declaring a total income of Rs. 1,19,186/-. The assessment was completed u/s. 143(3) of the Act vide order dated 28.12.2017 assessing the income of the assessee at Rs. 28,73,00,000/-. Subsequently, the case was reopened u/s. 147 of the Act. The AO issued notice u/s. 143(2) & 142(1) along with questionnaires were issued and served on the assessee on various dates. The assessment order was passed on 23.03.2016 u/s. 143(3) r.w.s. 254 of the I.T. Act, 1961 after making an addition of Rs. 23,98,00,000/- u/s. 68 of the Act. The relevant extract of the assessment order is reproduced below for reference:-
“2.2 The order of 143(3) r.w.s 254 of the Act was passed on 27/12/2011 assessing the total income of the assessee at Rs 28,73,00,000/-. The amount of Rs 28,73,00,000/-received by the assessee on allotment of preference shares capital was added as unexplained cash credits u/s 68:of the Act
2.3 The assessee filed an appeal before the CIT(A) and vide order dated CIT(A)-36/IT-56/12-13 dated 26/12/12 allowed the appeal of the assessee. Meanwhile the case was reopned u/s 147 of the Act and the order u/s 147 r.w.s 143(3) of the Act was passed on 27/12/12. In this order, the Short Term Capital Gains of Rs 63,36,956/ were set off aginst the Short Term Capital Loss of AV 2001-02
2.4 Against the order of the CIT(A), the department filed appeal before the ITAT. The ITAT “C” Bench wide ITA No 2070/Mum/2013 dated 16/10/14 set aside the matter to files of the AO with directions to readjudicate the issue in light of the directions contained in the order of the ITAT order in No ITA No 1714/Mum/2009 dated 8/10/10. In the order the ITAT has observed that the preference shares capital recievd from the following companies was explained:
| SN | Name of the Company | Amount of preference share capital paid |
|---|---|---|
| i | M/s Regency Share Holding P Ltd | 1,35,00,000 |
| ii | M/s Yulam Marketing P Ltd | 1,05,00,000 |
| iii | M/s. Nihat Promoters & Fiscal P Ltd | 1,75,00,000 |
| iv | M/s. M G Green Field P Ltd | 30,00,000 |
| v | M/s. HooglyVinmay P Ltd | 30,00,000 |
| TOTAL | 4,75,00,000 |
Thus as per the direction of the ITAT, the amount of Rs 4,75,00,000/-is treated to be genuine preference share capital received by the assessee.
3. Notices u/s 143(2)/142(1) of the Act alongwith detailed questionnaire were issued to the assessee on 10/12/14 and the samewere served on the assessee, on the given date there was no compliance from the assessee. On 30/12/14, the assessee filed a letter stating that the details were under compilation and sought a short adjournment. On 5/1/15 another letter was filed by the assessee and it was stated that the details are under compilation and again a short adjournment was sought. Another notice u/s 142(1) of the Act alongwith questionnaire was issued to the assessee on 17/11/15 fixing the hearing on 4/12/15. In the questionnaire, the assessee was asked to produce the following parties alongwith the necessary documentation for verification and examination:
| Sr. No. | Name | Amount |
|---|---|---|
| 1. | Platinum Commerce Pvt. Ltd. | 1,40,00,000 |
| 2. | Ankita Finvest Pvt. Ltd. | 1,25,00,000 |
| 3. | Bansidhar Vyapar Pvt. Ltd. | 2,76,00,000 |
| 4. | Allworth Commodities Pvt. Ltd. | 75,00,000 |
| 5. | Jaishree Commotrade Pvt. Ltd. | 2,32,00,000 |
| 6. | Snehdeep Impex Pvt. Ltd. | 1,55,00,000 |
| 7. | Belfast Agencies Pvt. Ltd. | 25,00,000 |
| 8. | Ventex Trade Pvt. Ltd. | 1,37,00,000 |
| 9. | Pentex Expo Pvt. Ltd. | 1,28,00,000 |
| 10. | Surya Shakti Marketing Pvt. Ltd. | 50,00,000 |
| 11. | Topgrain Management Pvt. Ltd. | 2,70,00,000 |
| 12. | Kashimikal Marcantile Pvt. Ltd. | 50,00,000 |
| 13. | Nalimbur Suppliers Pvt. Ltd. | 50,00,000 |
| 14. | Zenith Goods & Services Pvt. Ltd. | 25,00,000 |
| 15. | Graceful Traders Pvt. Ltd. | 50,00,000 |
| 16. | Tulshi Barter Pvt. Ltd. | 20,00,000 |
| 17. | Neerav Holdings Pvt. Ltd. | 20,00,000 |
| 18. | Spartan Consultants &FinvestPvt. Ltd. | 25,00,000 |
| 19. | Cherry Tie Up Pvt. Ltd. | 50,00,000 |
| 20. | Imtihan Commercial Pvt. Ltd. | 80,00,000 |
| 21. | WelkanVinimay Pvt. Ltd. | 50,00,000 |
| 22. | Apsara Fintrade Pvt. Ltd. | 10,00,000 |
| 23. | PNR Holdings Pvt. Ltd. | 25,00,000 |
| 24. | Rajesh Vanijya Pvt. Ltd. | 20,00,000 |
| 25. | Ranjit Distributors Pvt. Ltd. | 25,00,000 |
| 26. | Santram Transformers Pvt. Ltd. | 10,00,000 |
| 27. | Shree Shyam Promoters Pvt. Ltd. | 15,00,000 |
| 28. | Goldcrest Tracon Pvt. Ltd. | 50,00,000 |
| 29. | Dabriwal Investors & Financials Pvt. Ltd. | 30,00,000 |
| 30. | Bakliwal Finvest Pvt. Ltd. | 50,00,000 |
| 31. | Sunny FincomPvt. Ltd. | 30,00,000 |
| 32. | Mrigiya Electronic Industries Pvt. Ltd. | 1,00,00,000 |
3.1 On 4/12/2015, the assessee filed a letter in which it has been stated that the details as required vide the questionnaire dated 17/11/15has already been filed earlier. However, the assessee has again filed the same details. It was also stated that the parties are based in Kolkata and as such it cannot be insisted upon them to travel to Mumbai for cross examination. It was also stated that the parties are witness of the department and not of assessee. The assessee also requested that the parties may be produced for cross examination.
4. I have carefully considered the above submissions of the assessee. The same are not tenable. The details submitted by the assessee has already been considered in the earlier assessment proceedings. As no new details/documents/evidences have been filed by the assessee in support of its claim of receipt of share capital and as the same has already been considered, the written submissions of the assessee are not acceptable.
4.1 For the year under consideration the assessee has claimed to have received an amount of Rs. 28,73,00,000/- on account of allotment of cumulative redeemable preference shares. Out of the total amount of Rs 28,73,00,000/-, the amount of Rs 5,74,60,000/- was claimed to be towards face value of the shares and the amount of Rs 22,98,40,000/-was claimed to be towards share premium. This amount of Rs 28,73,00,000/- was claimed to have been received from 37 Kolkota based companies. In this regard investigation report was received from the AddI DIT(Inv)-Unit-I, Kolkata wherein it was conclusively proved that the amount of Rs 28,73,00,000/- was assessee’s own money which was routed as cumulative redeemable preference shares. During the course of investigation opportunity was given to the assessee to cross examine the directors of the Kolkata based companies from whom the assessee had claimed to have received the share application. However, on each such opportunity the assessee sought adjournment, even during the original assessment proceeding, the opportunity to cross examine the directors of the Kolkata based companies was allowed to the assessee, which the assessee failed to avail. Thus on all the occasions the assessee has only stalled the time.
4.2 During the current proceedings also the assessee has tried to delay the matter and at the fag end of the financial year has put forward its claim of cross examination of the directors of the Kolkata based companies. Thus it is deliberate attempt of the assessee to stall the proceedings. However, as stated above, opportunities to cross examine the directors of the Kolkata based companies were allowed to theassessee in the earlier proceedings which it has failed to avail. In this regard it is pertinent to note that the claim of the assessee was that it has received the share capital. The primary onus to conclusively prove the genuineness of the transaction was cast upon the assessee. However, the assessee has failed to discharge the same. All these findings lead to only one conclusion that the share application received by the assessee is not genuine. The onus cast upon the assessee to conclusively prove that the transaction of receipt of share application is genuine, is not discharged.
4.3 Taking into consideration assessee’s approach towards the issue under consideration, it needs to be mentioned that Section 68 of the I.T. Act requires the assessee to provide explanation not only about nature and source of credit appearing in the books of accounts but also regarding the genuineness of the transaction. To put it differently, the statute has put cumulative conditions to be satisfied by the assessee i.e. not only source of credit appearing in the books of account but the assessee is obliged to provide explanation regarding the nature of the same. For sake of convenience the Section 68 is reproduced as under:
Section 68 where any sum is found credited in the books of an assessee maintained for any previous year, and the assessee offers no explanation about the nature and sources thereof or the explanation offered by him is not, in the opinion of the Assessing Officer, satisfactory, the sum so credited may be charged to income-tax as the income of the assessee of that previous year.”
Even a cursory reading of the above provisions reveals that conjunction used between two words ienature and source” is word “and” not “or”. This speaks about the intention of legislature that the cumulative satisfaction of the both conditions is required to get rid of application of section of 68 of the Act. In the instant case, the assessee has failed to establish the nature of credit on account of loan and for this very reason the assessee squarely gets covered by the provision of section 68 of the Act.
4,4 It is held in the following judgments that the overall circumstances and human probabilities have to be taken into consideration while ascertaining the true nature of the transaction:
(i) The Hon’ble ITAT, Dehi Bench in the case of DCIT vs. Smt. Phoolwati Devi (2009) 314 ITR AT 1 (Delhi) has held as under: despite the documentation supporting the claim of the assessee superficially, the evidence could not be accepted in view of the surrounding circumstances and human probabilities. There were certain features of the case which belie the documentary evidence.”
(ii) In the case of M/s. Kachwala Gems vs. JCIT, ITA No. 134/JP/2002 dated 10.12.2003, which has been affirmed by the Supreme Court in the case of M/s.Kachwala Gems vs. JCIT (2006) 206 CTR (SC) 585, 288 ITR 10 (SC), it was held that payment by account payee cheque is not sufficient to establish the genuineness of purchases.
(iii) In the case of CIT vs. Prashant (P) (1994) 121 CTR (Cal.) 20, the Calcutta High Court has held that even payment by account payee cheque is not sacrosanct and it would not make an otherwise non-genuine transaction genuine.
(iv) In the case of Sumati Dayal vs. CIT (1995) 214 ITR 801, the Supreme Court, inter alia, held as under:
“in such cases, a superficial approach to the problem should be eschewed and the matter has to be considered in the light of human probabilities and further that any transaction about which direct evidence is rarely available should be inferred on the basis of circumstances available on the record. In that case, the majority opinion of the Settlement Commission was approved as it was taken after considering the surrounding circumstances and applying the test of human probabilities.”
(v) It was settled in the case of CIT vs. Durga Prasad More 82 ITR 540 (SC) that where a party relies on self-serving recitals in a document, it is for that party to establish the truth of these recitals. It was further held by the Apex Court in this case that the tax authorities are entitled to look into the surrounding circumstances to find out the reality of such recitals. The Hon’ble Apex Court has specifically observed as under:
“Science has not yet invented any instrument to test the reliability of the evidence placed before a Court of Tribunal. Therefore, the Courts and Tribunals are applying the test of human probabilities Human minds may differ as to the reliability of a piece of evidence.”
4.5 Very recently, the Supreme Court of India in the case of Vodafone International Holdings B.V. [2012] 17 taxmann.com 202 (SC) has held that revenue can invoke ‘substance over form principle’ or piercing corporate veil’ test only after it is able to establish on basis facts and circumstances surrounding transaction that impugned transaction is a sham or tax avoidance. In the Instant case, the circumstances and facts of the case, evidences gathered and after analysis of accounts, it is concluded that it is a fit case to invoke principle of “piercing of corporate veil”.
4.6 On the issue of Share-Application money entry racket, the Hon’ble Delhi High Court in its judgment in the case of Commissioner of Income-tax v Nova Promoters &Finlease (P.) Lid. [2012] 18 taxmann.com 217 (Delhi) was held that where share application money entry racket is unearthed, burden of proof under section 68 cannot be discharged by merely submitting documentary evidence. It was categorically held by the Hon’ble Delhi High Court that in view of the link between the entry providers and incriminating evidence, n mere filing of PAN number, acknowledgment of income-tax retums of the entry provider, bank account statement etc. was not sufficient to discharge the onus.
4.7 Reliance is also placed on the ratio laid down by the Hon’ble Supreme Court in the case of CIT vs P Mohankala 291 ITR 278. In this case the Hon’ble Apex Court has held that “the money may have been received by bank cheques and was paid paid through the process of banking transaction but that itself has no evidence. The Apex Court also held that section 68 of the Act itself provides where any sum is found credited in the books of the assessee in any previous year the same may be charged to income-tax as the income of the assessee of the previous year if the explanation offered by the assessee about the nature and source of such sums found credited in the books of the assessee is in the opinion of the assessing officer not satisfactory.
5. All these findings lead to only one conclusion that the share application money received by the assessee is not genuine. The onus cast upon the assessee to conclusively prove that the transaction of receipt of share application is genuine is not discharged. The assessee has failed to establish the nature of credit on account of share application and for this very reason the assessee squarely get covered by the provision of section 68 of the Act. As a result, by invoking provisions of section 68 of the Act the share application received by the assessee of Rs. 23,98,00,000/- is brought to tax. Further reliance is alsoplaced on the following judicial pronouncement
i) SreelekaBenerjee vs. CIT (1963) 49 ITR 112 (SC)
ii) Zars Trading Pvt. Ltd (2010) TIOL-308-ITAT Del. Vide order dated 26/02/2010 in ITA No. 3284/Del/2009.
iii) Kushara Real Estate Pvt. Ltd. ITA No. 4247/Del/2009.
iv) Dhingra Global Credance P. Ltd. vs ITO (2010) | ITR 529 (Trib) Delhi.
Thus, an amount of Rs. 23,98,00,000/- is added to the total income of the assessee u/s. 68 of the I.T. Act.
6. In the circumstances, the assessee has concealed particulars of its income in respect non-genuine transactions within the meaning of S 271(1)(c) read with explanation 1 thereto, of the IT Act, 1961. Penalty proceedings under section 271(1)(c) are being initiated separately for furnishing inaccurate particulars of income and concealment of income.
7. Subject to the above, the total income of the assessee for the assessment year 200506 is computed as under:
| i. | Income as discussed above (Additions u/s.68) |
: | 23,98,00,000 | |
| ii | Short Term Capital Gains | : | 63,36,956/- | |
| Less Set off Short Term Capital Loss for the AY 2001-02 | : | 63,36,956/- | NIL | |
| GROSS TOTAL INCOME | 23,98,00,000 |
3. Brief facts are that during the year under assessment, the assessee has issued cumulative redeemable preference shares amounting to Rs.28,73,00,000/-,having face value of Rs.5,74,60,00/- ata premium of of Rs.22,98,40,000/-. As per facts on records, the amount was received from 37 Kolkata based companies referred to (supra), which were considered to be bogus concerns involved in the business of accommodation entries. The Ld. AO added the entire amount to the income of the assessee treating the same as unexplained cash credit u/s 68 of the Act. Subsequently, in first round of litigation, the issue was challenged before the Ld. CIT(A), who had decided the appeal in favour of the assessee vide order dated 26.12.2012.Against the order of Ld. CIT(A), the Department had filed an appeal before the ITAT, which was adjudicated by the ITAT “E”Bench, inITA No.2070/Mum/2013,vide order dated 16.10.2014 and set aside the matter to the file of AO with directions to re-adjudicate the issue in light of directions in the earlier order of ITAT in ITA No. 1714/Mum/2009 dated 08.10.2010. The ITAT had directed to treat the amount of Rs.4.75/-crore received from the first five companies referred to (supra) and treated the same as genuine preference capital received by the assessee. Accordingly, the Ld. AO completed the assessment vide order dated 23.03.2016, giving effect to the directions of ITAT and had added the balance of Rs. 23,98,00,000/-, as deemed income of the assessee u/s 68 of the Act. Before Ld. CIT(A), assessee could not furnish any fresh evidence or material or submissions to substantiate its contentions or to dislodge the findings of Ld. AO. Again, the matter of addition u/s 68 has been raised before the Ld. CIT(A),who had confirmed the addition made by the Ld. AO for Rs.23,98,00,000/- vide impugned order dated 31.12.2024.
4. Being aggrievedwith the aforesaid addition, assessee preferred the present appeal.
5. At the outset, the Ld. Authorized Representative (“AR”) of the assessee submitted that all the transactions with the companies from whom the assessee has received preference share capital are treated to be genuine transactions under various orders of ITAT. He placed his reliance on the decision of jurisdictional ITAT Mumbai in ITA No.3359/Mum/2009placed before us at page no.971 to 997 in assessee’s own case for AY 2006-07, vide order dated 22nd July, 2011, having dealt with identical issue. Further, reliance has been placed on the order in the case of Netscape Software Private Limited, in ITANo. 1716/Mum/2009 and 2069/Mum/2013 for AY 2005-06 and 2007-08, vide order dated 22.09.2017, The relevant findings of the Tribunal, covering various companies with whom the said company had received redeemable preference share are as under:
“The assessee has furnished written submissions and therein furnished the details of evidences furnished by it in order to discharge the initial proof placed upon it. For the sake of convenience; we extract below the relevant submissions made by the assessee:-
“(1) 7,700 7% Redeemable preference shares aggregating 3,85,00,000
1. Nilhut Promotors & Fiscal Pvt. Ltd. This company has made an application for 1,000 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft dawn on The South Indian Bank, Kolkata. The sum of Rs 50,00,000 has been paid by demand draft dated 21st April, 2006 vide draft no 854057. The company is assessed to Income-tax under P.A.No AABCN5606K. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Rohit Jain and Sri Shyamsukha, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss. The capital and reserves of the company are Rs 1,37,02,100 and Rs8,81,55,000 respectively and loans and advances are Rs 1,04,34,069.
2. K.B. Combine Pvt. Ltd. This company has made an application for 600 7% Redeemable preference shares and paid a sum of Rs 30.00.000 bu three demand drafts drawn on HDFC Bank. Kolkata, The sum of Rs 30.00.000 has been paid bu three demand drafts of Rs 10.00.000 each dated 25th April, 2006. 29th April, 2006 and 20th April. 2006 vide draft nos 271578. 271600 and 271588 respectively. The company is assessed to Income-tax under P.A.No AABCK0836G. The share applicant along with share application form has submitted the board minutes the directors of the company to make investments, certificateing incorporation of company memorandum and articles of association of director’s report, balance sheet and profit and loss. The capital and incorporation, acknowledgement evidencing filing of return of income, reserves of the company are Rs 1,60,00,000 and Rs 21,93,97,206.18 respectively and loans and advances are Rs 4,98,09,184.
The sum of Rs 1,45,00,000 has been paid by demand INCOME आवक share applicant along with share application form has submitted
3. Realstone Trading Co. Pvt. Ltd. This company has made an application for 2.900 7% Redeemable preference shares and paid a sum of Rs 1,45,00,000 by five demand drafts drawn on ABN Amro dr of Rs 25,00,000, Rs 50,00,000, Rs 10,00,000, Rs 50,00,000 10,00,000 dated 31st May, 2006, 20th June, 2006, 24th July, 2006 28th August, 2006 and 6th September, 2006 vide demand draft 7643, 637648, 637654, 637684 and 637693 respectively: The -THEOmany is assessed to Income-tax under P.A.No AACCR7800G. The extract of the board minute 9 containing board resolution authorizing Mr. Vishal Pancholi the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs advances are Rs 8,00,68,500. 3,22,00,000 and Rs 12,84,00,000 respectively and loans and
4. Goldstone Trading Co. Pvt. Ltd. This company has made an application for 3,200 7% Redeemable preference shares and paid a sum of Rs 1,60,00,000 by six demand drafts drawn on ABN Amro Bank, Mumbai. The sum of Rs 1,60500,000 has been paid by demand drafts of Rs 25,00,000, Rs 25,00,000, Rs 15,00,000, Rs 40,00,000, Rs 30,00,000 and Rs 25,00,000 dated 21st April, 2006 and 29th May, 2007 vide demand draft nos 187449, 189652, 189653, 189655, 189656 and 189662 respectively. The company is assessed to Income-tax under P.A. No. AACCG1763B. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Mr. Manish Agarwal the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement balance sheet profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 2,18,00,000 and Rs 10,63,00,000 respectively and loans and advances are 5,53,32,145
(II) 7,500 Redeemable preference shares aggregating Rs 3,75,00,000
1. Rajesh Vinimay &Byapaar Pvt. Ltd. – This company has made an application for 1,000 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 50,00,000 has been paid by demand draft dated 28th April, 2006 vide draft no 775652. The company is assessed to Income-tax under P.A. No AABCR2450B. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Narendra Kumar Jain the director of the company to make investments, certificate of incorporation of company, memorandum and articles of association of company, acknowledgement endencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 2,14,30,000 and Rs 16,59,87,639.24 respectively andloans and advances are Rs 2,41,94,465.
2. Apsara Trex Put. Ltd. This company has made an application For 7% Redeemable preference shares and paid a sum of Rs of Rs 50,00,000 has been paid by demand draft dated 24th April, 2006 vide draft no 182043. The company is assessed to Income-tax under P.A. No AACCA2015N. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Itebrata Biswas and Sri Chndresh Kumar Jam, the directors of the company to make investments, certificate of incorporation of company, memorandum and articles of association of company, director’s report, acknowledgement evidencing filing of return of income, balance sheet and profit and loss. The capital and reserves of the company are Rs 2,39,77,000 and Rs 14,92,23,631.24 respectively and loans and advances are Rs 46,87,200 for the year ended on 31st March, 2007.
3. Macro Leafin Pvt. Ltd. – This company has made an application for 1,000 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 50,00,000 has been paid by demand draft dated 26th April, 2006 videdraft no 409156. The company is assessed to Income-tax under P.A. No AACCM0345F. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Arihant Jain and Sri Chndresh Kumar Jam, the directors of the company to make investments, certificate of incorporation of company, memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company 13,10,38,775.68 respectively and loans and advances are Rs 9,65,40,1 are Rs 2,40,57,000 and Rs
12.4. Tobu Financial Ser Pvt. Ltd. This company has made an application for 400 7% Redeemable preference shares and paid a sum of Rs 20,00,000 by a demand draft drawn on HDFC Bank, Kolkata. The sum of Rs 20,00,000 has been paid by two demand drafts of Rs 10,00,000 dated 25th April, 2006 and 29th April, 2006 vide drafts no 246600 and 246502. The company is assessed to Income-tax under P.A. No AACCT2562R. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri G. Agarwal, Sri J. Agarwal and Sri R. K. Sharma, the directors of the company to make investments, certificate of incorporation of company, memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss. The capital and reserves of the company are Rs 70,30,000 and Rs 5,84,12,358 respectively and loans and addes are Rs 65,39,836 as of 31 March, 2007.
5. Basukinath Vanijva Pvt. Ltd. *
This company has made an application for 200 7% Redeemable preference shares and paid a sum of draft drawn on HDFC Bank, Kolkata. The आपकRs 10,00,000 has been paid bu demand draft dated 25th April, 2006 vide draft no 204597. The company is assessed to Income-tax under P.A. No AACCB6596R. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Ashok Kumar singh and Sri Ashim Lahiri, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company.
6. Gulab Merchandise Pvt. Ltd. This company has made an application for 300 7% Redeemable preference shares and paid a sum of Rs 15,00,000 by a demand draft drawn’ on HDFC Bank, Kolkata. The sum of Rs 15,00,000 has been paid by demand draft Rs 15,00,000 dated 2501 April, 2006 vide drafts no 260029. The company is assessed to Income-tax under P.A. No AACCG40790. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Sitanshu Shekhar Panda and Sri Ashirn Lahiri, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 29,80,000 and Rs 2,58,73,541.97 respectively and loans and advances are Rs 2,00,000.
7. Sanmati Commodities Pvt. Ltd. This company has made an application for 400 7% Redeemable preference shares and paid a sum of Rs 20,00,000 by a demand draft drawn, on HDFC Bank, Kolkata. The sum of Rs 20,00,000 has been paid by two demand drafts of Rs 10,00,000 dated 26th April, 2006 and 28th April, 2006 vide drafts no 251181 and 251180. The company is assessed to Income-tax under P.A. No AAICS9605E. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Nagendra Prasad Sah, and Sri Ashok Kumar Singh, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss. The capital and reserves of thecompany are 19,95,000 and 1,70,24,661.96 respectively and loans and advances are 9,05,610.
8. Tobu Toys Ltd. – This company has made an application for 200 7% Redeemable preference shares and paid a sum of Rs 10,00,000 by a demand he draft drawn on HDFC Bank, Kolkata. The sum of Rs 10,00,000 has been paid by demand draft Rs 10,00,000 dated 29th April, 2006 vide andadvances are 9.05.610.drafts no 155119. The company is assessed to Income-tax under P.A. No AACCIN. The share applicant along with share application form has YINGINE-FASURA extract of the board minutes containing board resolution Sri G. Agarwal, Sri J. Agarwal and Sri R. K. Sharma, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31″ March, 2007. The capital and reserves of the company are 99,02,200 and 4,66,86,317.62 respectively and loans and advances are 4,71,78,355.
9. Sidlow Commercial Pvt Ltd. This company has made an application for 200 7% Redeemable preference shares and paid a sum of Rs 10,00,000 by a demand draft drawn on HDFC Bank, Kolkata. The sum of Rs 10,00,000 has been paid by demand draft Rs 10,00,000 dated 2nd May, 2006 vide drafts no 226070. The company is assessed to Income-tax under P.A. No AADCS8307E. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Ornprkash Agarwal, and SriSajjan Kumar Kheria, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing flung of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 40,72,500 and Rs 3,41,21,091.83 respectively and loans and advances are Rs 6 1,30,382.
10. Lyton Consultancy Pvt. Ltd. This company has made an application for 1,200 7% Redeemable preference shares and paid a sum of Rs 60,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 60,00,000 has been paid by demand draft Rs 60,00,000 dated 26th April, 2006 vide drafts no 874363. The company is assessed to Income-tax under P.A. No AAACL5926D. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Rajesh Jam, the directors of the company to make investments, certificate of incorporation of company, memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 1,92,97,000 and Rs 11,24,15318.45 respectively and leans and advances are Rs 1,17,43,727.
11. BanabaliVinirnay Pvt Ltd. – This company has made an plication for 600 7% Redeemable preference shares and paid a sum of 30,00000 by a demand draft drawn on ABN Amro Bank, Kolkata. The of Rs 30,00,000 has been paid by demand draft dated 28th INCOMAZINE 006 vide drafts nпо 155454. The company is assessed to Incomeunder P.A. No AACCB5498C. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Amit Dutta, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 49,62,500 and Rs 4,37,65,713.32 respectively.
12. Dream Vvapaar Pvt Ltd. – This company has made an application for 400 7% Redeemable preference shares and paid a sum of Rs 20,00,000 by a detnand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 20,00,000 has been paid by demand draft Rs 20,001000 dated 28th April, 2006 vide drafts no 436704. The share applicant along with share application form has submitted extract of the board minutes containing board atesolforon authorizing Sri Subrat Mukherjee and SriRajesh Tayal, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31 st March, 2007. The capital and reserves of the company are Rs 8,20,000 and Rs 1,72,86,622 respectively.
13. Anupam Dealers Pvt Ltd. – This company has made an application for 600 7% Redeemable preference shares and paid a sum of Rs 30,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 3 0,00,000 has been paid by demand draft Rs 30,00,000 dated 2x May, 2006 vide drafts no 440678. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Vijay Kumar and Mrs Sujata Shethi, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2007. The capital and reserves of the company are Rs 7,20,000 and Rs 5300,837 respectively.”
11. In our view, the assessee has discharged the initial burden of proof in this year also. Accordingly, consistent with the view taken by the co-ordinate 5006-07, we uphold the order passed by Ld CIT(A).
12. We shall now take up the appeal filed by the assessee for AY 2005-06. During this year, the assessee had received a sum of Rs.35.40 crores by way of allotment of 70,800 cumulative preference shares of Rs.1000/- each at a premium of Rs.4000/- each. The AO assessed the same u/s 68 of the Act and the Ld CIT(A) confirmed the same during this year. Aggrieved, the assessee has filed this appeal before Tribunal.
13. The decision rendered by co-ordinate bench in the assessee’s own case for AY 2006-07, referred supra, shall be applicable during this year also. On merits, the assessee has furnished written submissions to show that the assessee has discharged the initial burden of proof placed upon it u/s 68 of the Act. For the sake of convenience, we extract below the relevant submissions made by the assessee:-
(1) AbhiflexTracon Pvt. Ltd. – This company has made an application for 300 7% Redeemable preference shares and paid a sum of Rs 15,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 15,00,000 has been paid by demand draft dated 10′ February, 2005 vide draft no 113879. The company is assessed to Income-tax under P.A. No AACCA5702A. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Narendra Kumar Jam, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(2) Allworth Commodities Pvt. Ltd. This company has made an application for 700 7% Redeemable preference shares and paid a sum of Rs 35,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 35,00,000 has been paid by a demand draft of Rs 35,00,000 dated 4th February, 2005 vide demand draft no 112935. The company is assessed to Income-tax under P.A. No AACCA5809Q. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Mr S. C. Saha the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 54,32,000 and Rs 4,46,29,282.19 respectively and loans and advances are Rs 1,26,74,096.42
Ankita Finyest Pvt. Ltd. – This company has made an application for 1000 7% Redeemable preference shares and paid a sum of Rs by four demand drafts drawn on The South Indian Bank, आयolkata. The sum of Rs 50,00,000 has been paid by demand drafts of Rs 30,00,000, Rs 9,00,000, Rs 9,00,000, and Rs 2,00,000 dated 29th December, 2004 and three drafts dated 14th February, 2005 vide demand draft nos 267499, 242119, 242118 and 242120 respectively. The company is assessed to Income-tax under P.A. No AACCA1414D. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Mr. Suresh Kumar Bagaria the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company.
(4) Bansidhar Vyapaar Pvt. Ltd. This company has made an application for 2,100 7% Redeemable preference shares and paid a sum of Rs 1,05,00,000 by eight demand drafts drawn on ABN Amro Bank, Mumbai. The sum of Rs 1,05,00,000 has been paid by six demand drafts of Rs 9,00,000 each, Rs 1,00,000 and Rs 50,00,000 dated 1 1 th February, 2005 and 29th December, 2004 vide demand draft nos 242098,242097, 242109, 242107, 242105, 242104, 242108, and 267495 respectively. The company is assessed to Income-tax under P.A. No AABCB43900. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing the director’s of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 1,70,32,200 and Rs 12,47,13,000 respectively and loans and advances 2,11,55,377.75. are share applicati containing be the comparmemoranevidensprofi
(5) Bhootnath Marketing Pvt. Ltd. This company has made an application for 400 7% Redeemable preference shares and paid a sum of Rs 20,00,000 by demand draft. An amount of Rs 20,00,000 has been paid by demand draft dated 4th February, 2005 vide draft no 084574 drawn on ICICI Bank, Kolkata branch. The company is assessed to Income Tax under P.A. No AABCB3659C. The share applicant along with share application form have submitted extract of the board minutes containing board resolution authorizing the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and lossas on 31st March, 2005. The share holder’s fund the company Rs 49,9859.86 respectively and loans and advances are Rs 10,10,401sum of Rs 40,00,000 has been paid by two demand drafts of Rs
(6) Concert Tradelink Pvt. Ltd. This company has made an application for 800 7% Redeemable preference shares and paid a sum of Rs 400,000 by two demand drafts drawn on ABN Amro Bank, Kolkata अडे0,000 and Rs 25,00,000 dated 4th February, 2005 and 14th February, 2005 vide draft nos 112835 and 155293. The company is. assessed to Income- tax under P.A. No AABCC9445K. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri S. C. Saha, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 1,45,02, 100 and Rs 8,54,95,954.66 respectively and loans and advances are Rs 1,26,42,181.
(7) Devlok Marketing Pvt. Ltd. This company has made an application for 500 7% Redeemable preference shares and paid a sum of Rs 25,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 25,00,000 has been paid by demand draft dated 5th February, 2005 vide draft no 112886. The company is assessed to Income-tax under P.A. No AAACD9682L. The share applicant along withshare application form has submitted extract of the board minutes containing board resolution authorizing Sri R. C. Sharma, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31 March, 2005. The capital and reserves of the company are R 73,40,300 and 3,27,30,512.33.
(8) Facit Commodities Pvt. Ltd.This company has made an application for 1,000 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft drawn on ICICI Bank, Kolkata. The sum of Rs 50,00,000 has been paid by demand draft dated 15th February, 2005 vide draft no 155468. The company is assessed to Income-tax under P.A. No AAACF3846L. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Vijay Prakash Verma and Sri Murari Sharmathe, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company.
(9) Goldcrest Tracon Pvt. Ltd.This company has made an application for 700 7% Redeemable preference shares and paid a sum of 35,00.000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 35,00,000 has been paid by demand draft of Rs 35,00000 dated 4th February, 2005 vide drafts no 112934. The company is assessed to Income-tax under P.A. No AABCG0772D. The share has extract of the hard minutes containing board resolution authorizing Sri Sandip Chaborty, the director of the company to make investments, certificate of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 78,33,700 and Rs 4,23,77,207.82 respectively and loans and advances are Rs 40,45,6 14.39.
(10) Goldstone Trading Company Pvt. Ltd. This company has made an application for 18,000 7% Redeemable preference shares and paid a sum of Rs 9,00,00,000 by thirteen demand drafts drawn on ABN Amro Bank, Mumbai. The sum of Rs 9,00,00,000 has been paid by thirteen demand draft of Rs 25,00,000, Rs. 1,00,00,000, Rs 45,00,000, Rs 1,65,00,000, Rs 50,00,000, Rs 50,00,000, Rs 2,00,00,000 Rs 40,00,000, Rs 15,00,000, Rs 85,00,000, Rs 15,00,000, Rs 95,00,000 and Rs 15,00,000 dated 4th October, 2004, 91h November, 2004, 19 November, 2004, 23rd November, 2004, 27th November, 2004, 29th November, 2004, 3rd December, 2004, 3rd December, 2004, 7″ 2004, 29th December, 2004, 31st December, 2004, 10th January, 2005 and 24thFebruary, 2005 vide draft nos 813544, 711519, 962762, 711525, 957322, 957436, 955129, 955065, 711532, 132965, 711544, 135210 and 187408 The company is assessed to Income-tax under P.A. No AACCG1763B. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Manish Agarwal, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, director’s report, balance sheet and profit and loss as on 3 1st March, 2005. The capital and reserves of the company are Rs 2,03,00,000 and Rs 9,78,26,046 respectively and loans and advances are Rs 55,00,000.
(11) Goodview Trading Pvt. Ltd. This company has made an application for 600 7% Redeemable preference shares and paid a sum of Rs 30,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 30,00,000 has been paid by demand draft Rs 30,00,000 dated 4th February, 2005 vide draft no 112936. The company is assessed to Income-tax under P.A. No AABCG0413H. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Ramawatar Lath, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, __acknowledgement evidencing filing of return of income, director’s report, irt reserves of the company are Rs 68,80,750 and Rs 2,81,75,956.66 spectively and loans and advances are Rs 58,63,828.
(12) Goodward Agency Pvt. Ltd. This company has made an tupplicatich for 1,300 7% Redeemable preference shares and paid a sum of Rs 5,00,000 by two demand drafts drawn on ABN Amro Bank, TAX Kolkata. The sum of Rs 65,00,000 has been paid by two demand drafts RS 50,00.000 and Rs 15.00.000 both dated 4th Feburary, 2005 vide drafts no 113759 and 112836. The company is assessed to Income-tax under P.A. No AABCG7433M. The share applicant along with share application fom has submitted extract of the board minutes containing board resolution authorizing Sri S. C. Saha, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 50,29,100 and Rs 1,00,13,547.13 respectively and loans and advances are Rs 25,66,599.11.
(13) Graceful Traders Pvt. Ltd. This company has made an application for 1,000 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 50,00,000 has been paid by demand draft Rs 50,00,000dated 12th February, 2005 vide draft no 181729. The company is assessed to Income-tax under P.A. No AABCG7432L. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Ramawatar Lath, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 62,52,500 and Rs 2,37,53,3 17.58 respectively and loans and advances are Rs 66,36,971.38
(14) Jaishree Commotrade Pvt Ltd. This company has made an application for 500 7% Redeemable preference shares and paid a sum of Rs 25,00,000 by a demand draft drawn on The South Indian Bank, Kolkata. The sum of Rs 25,00,000 has been paid by demand draft Rs 25,00,000 dated 29th December, 2004 vide draft no 267497. The company is assessed to Income-tax under P.A. No AAACJ7907N. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, director’s report, balance sheet and profit and loss as on 3 1st March, 2005. The capital and reserves of the company are Rs 1,50,28,000 and Rs 10, 725.16 and are Rs 1,03,17,545.
(15) M.G.Greenfiled Pvt Ltd. This company has made an application for 007% Redeemable preference shares and paid a sum of Rs 55,00000 by two demand drafts drawn on HDFC Bank, Kolkata. The um of Rs 55,00,000 has been paid by two demand drafts Rs 25,00,000 dated February, 2005 and Rs 30,00,000 dated 15th February, 2005 fts no 113292 and 213354 respectively. The company is assessed to Income-tax under P.A. No AABCM7720P. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Shiv Kumar Gupta and Sri Partha Kanjilal, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(16) K.B. Combines Pvt Ltd. – This company has made an application for 200 7% Redeemable preference shares and paid a sum of Rs 10,00,000 by two demand drafts drawn on HDFC Bank, Kolkata. The sum of Rs 10,00,000 has been paid by two demand drafts’ of Rs 5,00,000 each dated 14th February, 2005 vide draft nos 03708 and 03709 respectively. The company is assessed to Income-tax under P.A. No AABCK0836G. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri J Agarwal and Sri B. Agarwal, the directors of thecompany to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(17) Metropolitan Carriage & Trading Co. Pvt Ltd. This company has made an application for 200 7% Redeemable preference shares and paid a sum of Rs 1 0,00,000 by a demand draft drawn on ING Vysya Bank, Kolkata. The sum of Rs 10,00,000 has been paid by demand draft Rs 10,00,000 dated 12th February, 2005 vide drafts no 035430. The company is assessed to Income-tax under P.A. No AABCM6543L The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri S.K. Agarwal and Sri Jagdish Agarwal, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(18) Mirases Commercial Put Ltd. This company has made an application for 1,000 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft drawn on ICIC Bank, Kolkata. The sum of Rs 5 0,00,000 has been paid by demand draft Rs 50,00,000 Hated 12th February, 2005 vide drafts no 106455. The company is assessed to Income-tax under P.A. No AADCM3247K The share applicant alafig with share application form has submitted extract of the board mintites containing board resolution authorizing Sri Ramawatar Lath, the direction of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknodgement evidencing filing of return of income, director’s report, INCOME.TA Balance sheet and profit and loss. The capital and reserves of the Dany are Rs 64,68,200 and Rs 2,36,70,181.72 respectively and toans and advances are Rs 4,05,116.77 as of mast March, 2005.
(19) Nilhat Promoters & Fiscal Pvt Ltd. This company has made an application for 500 7% Redeemable preference shares and paid a sum of Rs 25,00,000 by a demand draft drawn on The South Indian Bank, Kolkata. The sum of Rs 25,00,000 has been paid by demand draft Rs 25,00,000 dated 2911 December, 2004 vide drafts no 267502. The company is assessed to Income-tax under P. A. No AABCN5606K. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Rohit Jam & Sri P. K. Shyamsukhaa, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(20) NorfioxVincon Pvt Ltd. This company has made an application for 700 7% Redeemable preference shares and paid a sum of Rs35,00,000 by a demand draft drawn on ICICI Bank, Kolkata. The sum of Rs 35,00,000 has been paid by demand draft Rs 35,00,000 dated 16 in February, 2005 vide drafts no 155511. The company is assessed to Income-tax under P.A. No AAACH8942R. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Pramod Sharma and Sri Pramod Agarwal, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(21) Omni Suppliers Pvt Ltd. This company has made an application for 9,576 7% Redeemable preference shares and paid a sum of Rs 4,78,80,000 by five demand drafts drawn on ABN Amro Bank, Mumbai. The sum of Rs 4,78,80,000 has been paid by five demand drafts Rs 1,00,00,000, Rs 1,00,00,000, Rs 2,00,00,000, Rs 3,80,000 and Rs 75,00,000 dated 1st December, 2004, 1st December, 2004, 2nd December, 2005, 18th December, 2004 and 29th December, 2004 vide drafts no 957549, 957548, 954849, 958865 and 132741. The company is assessed to Income-tax under P. A. No AAAC069131). The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Manish Agarwal the director of the company to make investments, certificate of incorporation company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balade sheet and profit and loss as on 31 March, 2005. The capital and resebes of the company are Rs 1,59,7 1,59,75,000 and Rs 11, 11,25,000 Spectively and loans and advances are Rs 7,87,45,000.
(22) Pentex Expo Pvt Ltd. This company has made an application for 7% Redeemable preference shares and paid a sum of Rs 50,00,000 by a demand draft drawn on The South Indian Bank, Kolkata. The sum of Rs 50,00,000 has been paid by demand draft Rs 50,00,000 dated 291h December, 2004 vide drafts no 267500. The company is assessed to Income-tax under P. A. No AABCP486IE. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Suresh Kumar Bagaria, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company.
(23) Platinum Commerce Pvt Ltd. This company has made an application for 2,600 7% Redeemable preference shares and paid a sum of Rs 1,30,00,000 by two demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 1,30,00,000 has been paid by demand draft Rs 80,00,000 and Rs 50,00,000 both dated 5th February, 2005 vide draft nos 113217 and 113216. The company is assessed to Income-tax under P. A. No AABCP8186E. The share applicant along with share application formhas submitted extract of the board minutes containing board resolution authorizing the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, director’s report, balance sheet and profit and loss as on 31 March, 2005. The capital and reserves of the company are Rs 62,47,000 and Rs 2,66,50,972. 15 respectively and loans and advances are Rs 18,41,524.
(24) Plus Jet Finvest Pvt Ltd. This company has made an application for 200 7% Redeemable preference shares and paid a sum of Rs 10,00,000 by two demand drafts drawn on HDFC Bank, Kolkata. The sum of Rs 10,00,000 has been paid by two demand drafts of Rs 5,00,000 each both dated 12th February, 2005 vide draft nos 3714 and 3715. The company is assessed to Income-tax under P. A. No AABCP9939M. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri R. P. Agarwal and Sri R. K. Sharma, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(25) Rahul Traders Pvt Ltd. This company has made an application 400 7% Redeemable preference shares and paid a sum of Rs 20,00,000 by four demand drafts drawn on HDFC Bank, Kolkata. The sums 20,00,000 has been paid by four demand drafts of Rs 5,00,000 mach, two demand drafts dated If February, 2005 and other two draftsted 14th February, 2005 vide draft nos 3712, 3713 3719 and.. Ee the company is assessed to Income-tax under P. A. No 3720 extract of the board minutes containing board resolution company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(26) Reaistone Trading Co. Pvt. Ltd. This company has made an application for 15,424 7% Redeemable preference shares and paid a sum of Rs 7,71,20,000 by 17 demand drafts drawn on ABN Amro Bank, Mumbai. The sum of Rs 7,71,20,000 has been paid by seventeen demand drafts of Rs 25,00,000, Rs 12,00,000, Rs 20,00,000, Rs 1,00,00,000, Rs 70,00,000, Rs 1,00,00,000, Rs 85,00,000, Rs 15,00,000, Rs 65,00,000, Rs 55,50,000, Rs 4,50,000 Rs 1,00,00,000, Rs 40,00,000, Rs 50,00,000, Rs 1,20,000 Rs 13,00,000 and Rs 15,00,000 dated 4th October, 2004, thi October, 2004, 6th October, 2004, 20th October, 2004, 18th November, 2004, 25th November, 2004, 6th December, 2004, 29th December, 2004, 10th January, 2005, 17th January, 2005 and 23rd March, 2005 vide draft nos 813543, 711558, 783100, 711560, 887893, 962649, 962650,711569, 963203, 957906, 711571, 132964, 132740, 135211, 960450, 711591 and 711594. The company is assessed to Income-tax under P. A. authorizing Sri Vishal Pancholi, the director of the company to make has submitted extract of the board minutes containing board resolution investments, certificate of incorporation of company memorandum and articles of association of company, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 2,13,00,000 and Rs 8,48,00,000 respectively and loans and advances are Rs 5,50,68,500.
(27) Regency Shares & Holding Pvt. Ltd. This company has made an application for 1,580 7% Redeemable preference shares and paid a sum of Rs 79,00,000 by eight demand drafts drawn on The South Indum Bank, Kolkata. The sum of Rs 79,00,000 has been paid by eight demand drafts of Rs 25,00,000, Rs 9,00,000, Rs 9,00,000, Rs 9,00,000, Rs 8,00,000, Rs 1,00,000, Rs 9,00,000 and Rs 9,00,000 dated 29th December, 20045 1 11h February, 2005 and 14th February, 2005, vide drafts no 267498, 242106, 242110, 242111, 242112, 242117, 242116 and 242115. The company is assessed to Income-tax under P.A.No. AABCR2441J. The share applicant along with share application form has Skmitted extract of the board minutes containing board resolution incorporation of company memorandum and articles of association of company.
(28) Snehdeep Impex Pvt Ltd. – This company has made an application 26207% Redeemable preference shares and paid a sum of Rs 8 Rs 8 1,00,000 has been paid by eight demand drafts of Rs 30,00,000, Rs 9,00,000, Rs 9,00,000, Rs 5,00,000, Rs 9,00,000, Rs 9,00,000, Rs 9,00,000 and Rs 1,00,000 dated 29th December, 2004, 11th February, 2005 and 14th February, 2005 vide draft nos 267496, 242103, 242096, 242101, 242099, 242100, 242102 and 242130. The company is assessed to Income-tax under P.A.No AAECS4057J. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, director’s report, balance sheet and profit and loss as on 31st March, 2005. The capital are Rs 1,64,64,200 and Rs and reserves of the company 10,36,60,455.75 respectively and loans and advances are Rs 2,16,57,329.
This company has made an application for 500 7% Redeemable preference shares and paid a sum of Rs 25,00,000 by a demand draft drawn on ICICI Bank, Kolkata. The sumof Rs 25,00,000 has been paid by demand draft Rs 25,00,000 dated 14th February, 2005 vide draft no 155294. The company is assessed to Income-tax under P.A.No AADCS5976P. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri R. C. Sharma, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income, directors report, balance sheet and profit and loss as on 31st March, 2005. The capital and reserves of the company are Rs 85,08,700 and Rs 3,15,55,125.76 respectively and loans and advances are Rs 55,55,905.
(30) Sukhvarsha Distributors Pvt Ltd. This company has made an application for 300 7% Redeemable preference shares and paid a sum of Rs 15,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 15,00,000 has been paid by demand draft Rs 15,00,000 dated 141 February, 2005 vide drafts no 113878. The company is assessed to Income-tax under P. A. No AADCS5992F. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Rajesh Kumar Jam, the director of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income..
(31) Techbuild Impex Pvt Ltd.- This company has made an application Jar 300 7% Redeemable preference shares and paid a sum of Rs 15,0000 by a demand draft drawn on ABN Amro Bank, Kolkata. The sum of Rs 15,00,000 has been paid by demand draft Rs 15,00,000 dated 1 Jia Repruary, 2005 vide drafts no 113912. The company is assessed to beome-tax under P. A. No AABCTI 877A. The share applicant along with hare application form has submitted extract of the board minutes Agarwal, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(32) Tobu Engineering Pvt Ltd. application for 200 7% Redeemable preference shares and paid a sum of Rs 10,00,000 by two demand draft drawn on HDFC Bank, Kolkata. The This company has made an sum of Rs 10,00,000 has been paid by two demand drafts of Rs 5,00,000 each dated 12th February, 2005 vide drafts no 3711 and 3710. The company is assessed to Income-tax under P. A. No AABCT8936G. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri R. P. Agarwal and Sri P. P. Bose, the directors of the company to make investments, certificate of incorporation of company memorandum andarticles of association of company, acknowledgement evidencing filing of
(33) Veevu Trader Pvt Ltd. This company has made an application for 300 7% Redeemable preference shares and paid a sum of Rs 15,00,000 by a demand draft drawn on ICICI Bank, Kolkata. The sum of Rs February, 2005 vide draft no 113913. The company is assessed to Income-tax under P.A.No AABCVI 152E. The share applicant alongwith 15,00,000 has been paid by demand draft Rs 15,00,000 dated 11th share application form has submitted extract of the board minutes containing board resolution authorizing Sri Mahendra Sethia and Sri Mangat Mal Sethia, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.
(34) Ventex Trade Pvt Ltd. – This company has made an application for 1,900 7% Redeemable preference shares and paid a sum of Rs 95,00,000 by six demand drafts drawn on The South Indian Bank, Kolkata. The sum of Rs 95,00,000 has been paid by demand draft Rs 50,00,000 and five demand draft of Rs 9,00,000 each dated 29111 December, 2004 and 14 1h February, 2005 vide drafts no 267501, 242121, 242122, 242123, 242124 and 242125 respectively. The company is assessed to Income- under P. A. No AAACV9866A. The share applicant along with share application for has submitted extract of the board minutes containing board resolution authorizing Sri Suresh Bagaria, the director of the Company make investments, certificate of incorporation of company memorandum and articles of association of company.
(35)Yulan Marketing Pvt Ltd. – This company has made an application 5,00,000 by five demand drafts drawn on The South Indian Bank, Kolkata. The sum of Rs 95,00,000 has been paid by demand draft Rs 65,00,000, three demand draft of Rs 9,00,000 and Rs 3,00,000 dated 29th December, 2004 and 14th February, 2005 vide drafts no 267503, 242126, 242127, 242128 and 242129 respectively. The company is assessed to Income-tax under P. A. No AAACYI8I IC. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Rohit Jain and Sri M. K. Shyamsukha, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgment evidencing filing of return of income.
(36) Zipper Mercantile Pvt Ltd. This company has made an application for 400 7% Redeemable preference shares and paid a sum of Rs 20,00,000 by a demand draft drawn on ABN Amro Bank, Kolkata.
The sum of Rs 20,00,000 has been paid by demand draft Rs 20,00,000 dated 1 1th February, 2005 vide ‘draft no 113911. The company is assessed to Income-tax under P. A. No AAACZ1039K. The share applicant along with share application form has submitted extract of the board minutes containing board resolution authorizing Sri Mahendra Sethia and Sri M. M. Sethia, the directors of the company to make investments, certificate of incorporation of company memorandum and articles of association of company, acknowledgement evidencing filing of return of income.”
14. In our view, the assessee has discharged the initial burden of proof in this year also. Accordingly, consistent with the view taken by the co-ordinate bench in AY 200607, we set aside the order passed by Ld CIT(A) and direct the AO to delete the impugned addition.”
6. Based on aforesaid submissions by the assessee, it was concluded by the Tribunal that once the assessee has discharged the initial burden of proof, as per consistent view taken by the Co-ordinate Bench of the Tribunal, the order of Ld. CIT(A) is set aside and the Ld. AO is directed to delete the impugned addition. Further, in the case of GibsComputers Ltd. in ITA1715 & 3858/Mum/2009 and ITA2066 & 2071 for AY 2007-08 and 2008-09 vide order dated 04.03.2016, ITAT Mumbai had decided the issue in favour of assessee by observing that the Co-ordinate Benches of Tribunal are consistently taking a view that Assessing Officer has not disproved the documents furnished by the assessee to discharge the initial burden placed upon it u/s 68 of the Act. Further noted that, since the facts and circumstances are identical with the cases decided by the Co-ordinate Bench of ITAT and the CIT(A) has followed the decision of ITAT, we do not find any reason to interfere with the orders passed by the Ld. CIT(A) on the issue agitated before the Tribunal.
7.In another case, in the case of Luminant Investments Limited in ITA No. 2067/Mum/2013 vide order dated 27.09.2017, a similar view is taken by the Tribunal, wherein in total 41 companies are involved from whom the assessee has received investment in the form of share capital and share premium and some of such companies are part of investors in the present case.
8. Further, in assessee’s own case for assessment year 2006-07, the Coordinate Bench of ITAT Mumbai has decided the identical issue, in ITA No. 3859/Mum/2009 dated22.07.2011 for Ay 2006-07, wherein the share capital and premium received by the assessee company from various entities, added by the Ld. AO treating the same as unexplained cash credit u/s 68 of the Act was deleted by the Tribunal observing that the issue of application money cannot be treated as income of the assessee company, until and unless it is proved beyond doubt that the assessee’s own money has come back through some closely related applicant. Once the identity of the applicant is disclosed and found as correct, then even if the said transaction is suspected by the revenue authorities, the same cannot be treated as income of the assessee company, which is a public limited company. Accordingly, we delete the addition made by the Assessing Officer and confirmed by the Ld. CIT(A). The companies and transactions involved in the aforesaid order are as under:
| Sl.No. | Name of the Party | Shares allotted | Amount Recd. |
|---|---|---|---|
| 1 | Regency Shares & Holdings P Ltd | 1000 | 5000000 |
| 2 | Yulan Marketing P Ltd | 1200 | 6000000 |
| 3 | Nilhat Promoters & Fiscals P Ltd | 600 | 3000000 |
| 4 | M G Greenfield P Ltd | 1200 | 6000000 |
| 5 | Dabriwal Investment & Financiers P Ltd | 200 | 10000000 |
| 6 | AsraraFintrade P Ltd | 1000 | 5000000 |
| 7 | Hooghly Vinimary P Ltd | 1000 | 5000000 |
| 8 | Clix Securities P Ltd | 150 | 750000 |
| 9 | PNR Holdings P Ltd | 200 | 10000000 |
| 10 | Cube Trafin P Ltd | 1000 | 5000000 |
| Total | 11150 | 5,57,50,000 | |
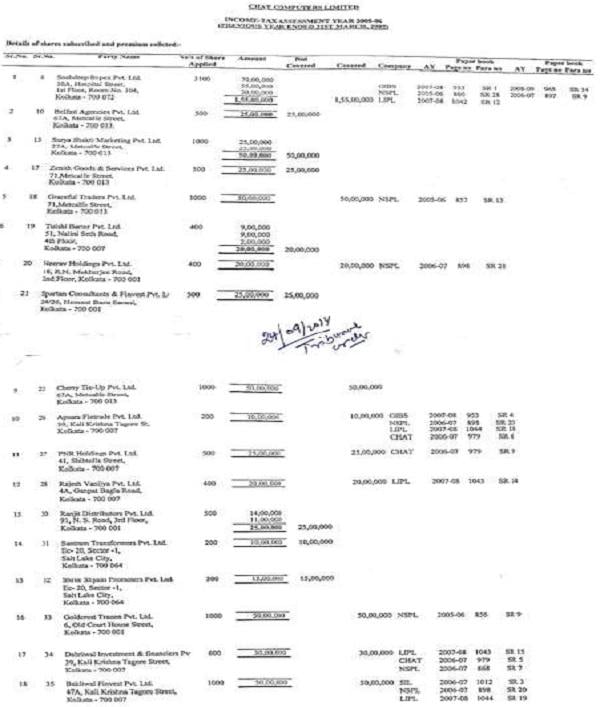
9. To sum up the aforesaid observations of the Tribunal qua various entities involved in the transaction pertaining to year under consideration, Ld. AR has furnished a chart mentioning the details of various ITAT orders along with their page numbers, the same is extracted, here under for the sake of convenience and reference:
–
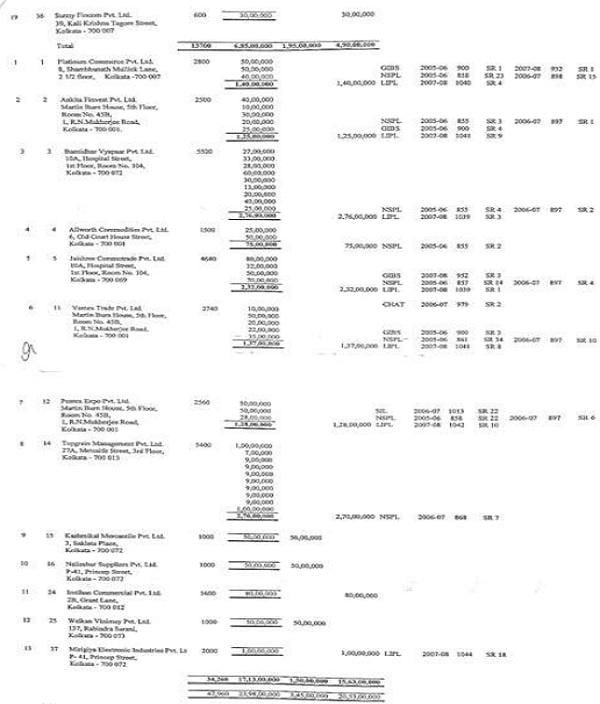
10. On perusal of the aforesaid chart and decisions of Tribunal, it is found that most of the companies, who had invested in the assessee’s preference share capital, are covered by the decisions of Tribunal in aforesaid cases.Further, some companies are not covered, where from the assessee has received a share capital of Rs.3,45,00,000/-.We found that, the circumstances and facts are identical, as the assessee has furnished basic / primary documents to substantiate the character of transactions in the form of identity and creditworthiness of the investors and genuineness of the transactions, such documents are placed before us at page no.6 to 655 in the assessee’s paper book, containing therein the relevant documents such as acknowledgement slip for receipt of payment towards application money for redeemable preference shares, copy of cheque received from the investor, copy of application for issue of shares, abstract of the minutes of meeting of the investor company, ITR of the investor company, certificate of registration as NBFI by RBI, confirmation, audited financials, memorandum and article of association, certificate of incorporation etc.
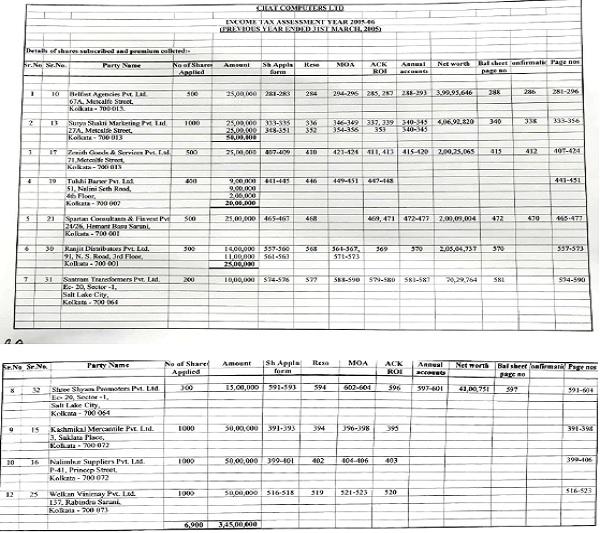
11. Considering the aforesaid facts and circumstances, wherein the assessee has furnished all the primary information before the AO to satisfy the requirement of section 68, following the consistent view adopted by the coordinate benches of the Tribunal in case of various entities, we do not see any reason to deviate from the same in absence of any contrary material, decision or argument by the revenue. Further, regarding the companies which are not covered by the aforesaid cases, Ld. AR has furnished a chart stating therein the details of various documents furnished before the revenue authorities .To decide the fate of the companies, which also stand at the same pedestal in terms of facts and circumstances, as that of the other companies which are covered by the decision of Tribunal (referred to supra). the same is extracted as under:
12. Before proceeding any further, it would be relevant to extract the findings of Tribunal in assessee’s own case for assessment year 2006-07, in ITA ITA No.3359/Mum/2009 (supra), wherein the identical issue was raised and decided by the Tribunal with the following observations:
“5 We have considered the rival contention and perused the relevant material on record. The Assessing Officer has discussed the issue in para 4.1 to 4.4 of his orderas under:
“4.1 During the assessment proceedings, it has been observed that the assessee has repaid the loan to the tune of Rs. 5.51 crores by allotting preference shares to private corporate bodies. It is verified from records that 11,150 cumulative redeemable preference shares of Rs. 1000 each at a premium of Rs. 4000/- per shares were allotted to the difference private corporate bodies. Further, it is seen that the amount of Rs. 1,11,50,000 is received towards the face value of the shares and Rs. 4,46,0,00 is received towards premium of the shares, hence total amount of Rs. 5,57,50,00 received 15owards allotment of11,150 cumulative redeemable preference shares.
4.2 Department has conducted investigation to verify the source of funds taken by the assessee for repayment of its dues to M/s Madhavpura Mercantile Cooperative Bank Ltd. Special team was constituted for this purpose by CBDT. The reports of the AddI.DIT (Inv). Unit I, Kolkata was received by this office on 4.12.2006,23,2.2007 and on 24.4.2007.
As per the investigation report received from theADdI.DIT) (Inv) Unit -1 Kolkata, the following companies has paid share application money to the assessee:
| Sl.No. | Name of the Party | Shares allotted | Amount Recd. |
|---|---|---|---|
| 1 | Regency Shares & Holdings P Ltd | 1000 | 5000000 |
| 2 | Yulan Marketing P Ltd | 1200 | 6000000 |
| 3 | Nilhat Promoters & Fiscals P Ltd | 600 | 3000000 |
| 4 | M G Greenfield P Ltd | 1200 | 6000000 |
| 5 | Dabriwal Investment & Financiers P Ltd | 200 | 10000000 |
| 6 | AsraraFintrade P Ltd | 1000 | 5000000 |
| 7 | Hooghly Vinimary P Ltd | 1000 | 5000000 |
| 8 | Clix Securities P Ltd | 150 | 750000 |
| 9 | PNR Holdings P Ltd | 200 | 10000000 |
| 10 | Cube Trafin P Ltd | 1000 | 5000000 |
| Total | 11150 | 5,57,50,000 | |
4.3 The ADIT(Inv). Unit 1, Kolkata has also recorded statement of one Shri Kishan Kumar Verma S/o Vijay Kumar Verma, resident of Howrah 2 who has admitted in his statement recorded u/s 131 of the IT Act, 1961 on 13.10.2006 that he rendered his individual bank account as well his propriety concerns Bank accounts to deposit cash in lieu of signed blank account payee cheques to Shri Pawan Kumar Agarwal, S/o Shri Agarwal, resident of 2C Dover Rioad, Kolkata 19 and Shri D K Nahata resident of Kolkata for a commission of Rs. 100 for per Rs. 1,00,0/-. He also stated that similar transactions were made with one Shri Murari Agarwal. The blank cheques so issued were used by Shri Pawan Kumar Agarwal and Shri N K Nahata as and when required. He also stated that all the cash deposited in his accounts’ were made by Delhi based parties which were not known to him, Later on statement of Shri Pawan Kmar Agarwal who was former Director of M/s Mrugiya Electronics Industries P Itd recorded by the ADIT(Inv0 Unit 1 Kolkata /s 131 of the IT Act. In his statement he has denied the ownership of the cash. But at the same time he has admitted that the cheques received from Shri Kishan Kumar Verma and Shri Murari Agarwal were utilized to invest in the shareapplication money of M/s Chat Computers P Ltd (formerly known as M/s Chitrakut Computers P Ltd). It is very much clear from the above that the assessee has mobilized the unaccounted cash by creating various ayers of which they are the ultimate beneficiary.
4.4 Similar transactions have been done by the group concerns of the assessee which are given in Annexure I which is the report of Investigation wing of the department. Wherein it is clearly established that cash was deposited in one account and after passing through various levels it has reached to the assessee company. Few such instances are covered in the report annexed herewith.
6 It is evident from the assessment order that the Assessing Officer has not conducted any independent enquiry during the assessment proceedings; but simply relied upon the report of the ADIT(Inv), Unit 1, Kolkata as well as the statements of the directors of various Kolkata based companies, who have paid the application money. The said investigation by the ADIT(Inv) Unit 1. Kolkata was not carried out during the assessment proceedings; therefore, the said investigation was neither thequiry carried out during the assessment proceedings not part of the assessment proceedings. It is clear that the scrutiny assessment commenced after about one year from the alleged investigation was over. The Assessing Officer has heavily relied upon the investigation report and proceedings and specifically on the point that the assessee was given opportunity to cross examine the directors of the investing companies, who paid the application money and further, the assessee was also asked by the Assessing Officer to produce the directors, whose statements were recorded by the investigation unit 1, Kolkata for cross examination of them.
6.1 In para 4.5 and 4.6, the Assessing Officer has recorded the reasons for forming the view that the assessee was given several opportunities to cross examine the directors of the investing companies as under:
4.5 As per the statements of the Directors of various Kolkata based companies and the other persons, it is clear that the assessee had given cash to so called companies which in turn issued back to assessee cheques/demand draft of equivalent amount. This fact was stated on oath by the directors of the said companies. However, director of the assessee Shri Kiriti Kumar N Parekh denied to have paid any cash to these parties in his statement before ADIT(Inv) Unit IX(2), Mumbai. In his statement he stated his intention to cross examine the aforesaid directors to prove his stand. DDIT(Inv) Unit 1(2) Kolkata has given several opportunities to the assessee to cross examine the aforesaid directors at its Kolkata office. In spite of repeated opportunities given to the assessee, the said cross examination could not take place as the assessee sought adjournment every time. Thereafter, the assessee stated that ‘he would exercise his right of cross examine at the time of assessment.
4.6 to the A letter dated 16.9.2008 was issued by this office Managing Director of the company giving him opportunity to cross examine the share4 applicants and was asked to file confirmation of the said share applicants on 30th Sept, 2008. However, no one appeared on 30th Sept 200. It is pertinent to mention here that assessee was given several opportunities by the DDIT(Inv) Unit 1(2) Kolkata to cross examine the said directors of Kolkata based companies to prove the genuineness of his stand which he ahs recorded to the ADIT(Inv). Unit IX(2) Mumbai. But, instead, assessee ahs sought adjournment every time andelmeMarsover, the onus of proving genuineness of the transaction tes on the assessee, which the assessee has tried to shift on the Assessing Officer’s shoulder.
6.2 Since the investigation proceedings were not part of the assessment proceedings in the case of the assessee and even the investigation was not either u/s 132 or u/s 133 of the IT Act. It seems that investigation by the ADIT(Inv) Unit 1, Kolkata is preliminary investigation only to verify the suspicion of any concealment of income. The Assessing Officer, during the course of assessment proceedings asked the assessee to produce the said directors for cross examination. It is evident from the letter of the Assessing Officer dated 01.10.2008 as well as dated 16.9.2008 that the Assessing Officer did not summon these directors to be present in the office In the Assessing Officer for the purpose of cross examination by the assessee; but on Toontrary, the assessee was asked to produce these directors for cross examination purpose. This is a gross violation of principles of natural justice when the Assessing Officer asked the assessee to produce the directors for availing Opportunity of cross examination. The Assessing Officer relied upon the statement of the directors of the investing company recorded during the investigation proceedings by the ADIT(Inv) Unit 1, Kolkata. Instead of ensuring the presence of these persons for giving opportunity to the assessee to cross examine, the Assessing Officer asked the assessee to produce them, which in our considered opinion is an absolute unjust and opposite to the rule of law and what procedure demands.
Therefore, there is a total denial of opportunity to the assessee to cross examine the persons, whose statements are used against the assessee. Further, when the director of the assessee categorically denied, during the Investigation, the allegation of giving cash to those investing companies then the onus is on the revenue to prove that the application money received by the assessee is assesse’s own money routed through those applicants companies. There is no evidence or material brought on record by the Assessing Officer, except the un-cross examined statements of the third party, to show any movement of cash routed back to the assessee in form of application money in the alleged allotment of cumulative preferential shares. Rather, it is undisputed fact that the application money was received through account payee cheque/bank draft given by the investing companies from their respective bank account. It is also an accepted fact that source of the application money was found in the bank account of the investing companies deposited through account payee cheques; therefore, no cash transaction was found by the Assessing Officer in the bank account of the investing companies.
6.4 The Assessing Officer doubted the movement of cash from the assessee as being passing through various levels and reached to the assessee company. However, no finding has been given to the effect as to how the alleged cash/money of the assessee company routed through various levels finally reached to the assessee. Not an lota of evidence or material has been brought on record to show even, prima facie that the said amount representing application money moved from the assessee and reached to the assessee. Rather, documentary evidence on record exhibits different facts i.e. as per books of account of the assessee as well as those of investing companies together with the return of income. board resolution go to prove that the said application money was paid by theInvesting company to the pointment of the preferential shoros. The Investing companies have shown the said amount as investment in their books of account. The money routed through banking channels and through account payee cheques/bank draft, undisputed given by the parties. Even, the source of the application money was found in the bank account of the investing companies not by any cash deposit; but through account payee cheques. Therefore, when all the documentary evidence contradicts the statements of the directors recorded by the investigation unit of the department then such statements alone cannot be taken as the basis much less a good or proper basis for any addition.
6.5 It is settled proposition of law that the statement recorded during the course of investigation without corroborative evidence has no evidentiary value. It is pernment to mention that the statements recorded in this case are not under search orsurvey or assessment proceedings therefore the same cannot be used against the assesse without following the due process of corroboration and cross examination. Even otherwise, the statement without cross examination and corroborative evidence cannot be used against the assessee.
6.6 As pointed out by the Id AR of the assessee the credibility of the statements is also not free from doubt as it appears that all the statements are prepared by the department in an identical fashion and manner before those were got signed on different dates. It is apparent that certain identical mistakes are appearing in those statements allegedly recorded on different dates.
For example:-
Queshonno.4 Does you company has transaction with the following companies? If so, give details and nature of such transactions
This mistake “Does you” is appearing in question No. 4, of all the statements, which shows that questionnaire was already prepared and answers were already written in the same manner as it is evident from the answer to question no.6 as under:
Question No. 6 Do you have to say anything else?
Ans: I have gone through the above statement and the same has been recorded correctly and without any fabrication. The above statement gas been given by me without the use of any force, coercion or threat.
The mistake in the answer no. 6 is also identical in all the statements recorded on different dates. Since the statements were recorded by the investigation team of Unit 1, Kolkata and not during the proceedings before any Court of law, therefore all these facts suggest and indicate to believe that the same are not as a verbatim of what the concerned person stated; but obtained by the recon Flebonment in a mechanical manner. However, without going into validity of the statements when all other records, material and documentary evidences contradict and nullify the statements then the reliance placed by the Assessing Officer on such statement is highly unjustified and improper.
7. Even otherwise, in the case of the Ashwani Gupta (supra), the Hon’ble Delhi High Court has taken a note of the finding of the Tribunal in para 2 as under:
“2. The Tribunal has confirmed the order passed by the CIT(A) which held the entire addition made by the Assessing Officer to be invalid and had deletedthesom The CINA had clearly held that the Assessing Officer nad postal the assessment order in violation of the principles of natural justice in as muer as he had neither provided copies of the seized material to the assessee nor had he allowed the assessee to cross-examine one Mr. Manoj Aggarwal on the basis of whose stalement the said addition was made. The CIT(A) also held that the entire addition deserved to be deleted, particularly so, because the transactions also stood duly reflected in his regular returns.”
7.1 The Hon’ble High Court has held that once there is violation of principles of natural justice by not providing seized material to the assessee as well as cross examination of the persons on whose statements, the Assessing Officer relied upon, amounts to denial of opportunity and would be fatal to the proceedings. The Hon’ble Delhi High Court has observed in para 7 as under:
“7. In view of the foregoing circumstances, we feel that no interference with the impugned order is called for. The Tribunal has correctly understood the law and applied it to the facts of the case. Once there is a violation of the principles of natural justice in as much as seized material is not provided to an assessee nor is cross-examination of the person on whose statement the Assessing Officer relies upon, granted, then, such deficiencies would amount ta a denial of opportunity and, consequently, would be fatal to the proceedings. Following the approach adopted by us in SMC Share Brokers Ltd. (supra), we see no reason to interfere with the impugned order. No Substantial question of law arises for our consideration.”
8. Similarly, in the latest decision, the Hon’ble Delhi High Court in the case of Oasis Hospitalities P Ltd (supra), after considering all the relevant decisions on the issue including the decision of the Hon’ble Supreme Court in the case of Lovely Exports P Ltd (supra), decision of the Full Bench of the Hon’ble Delhi High Court in the case of Sophia Finance Ltd reported in 205 ITR 98 (Del) (FB) and the decision in the case of Divine Leasing & Finance Ltd (supra) has observed in paras 11 to 16 as under: tris clear from the above that the initial burden is upon the asse see to explain the nature and source of the share application money received by the assessee. In order to discharge this burden, the assessee is required to prove:
(a) the identity of shareholder:
(b) the genuineness of transaction; and
(c) the creditworthiness of shareholders.
12 In case the investor/shareholder is an individual, some documents will have to be filed or the said shareholder will have to be produced before the Assessing Officer to prove his identity. If the creditor/subscriber is a company, then the details in the form of registered address or PAN identity, etc., can be furnished.
13 The genuineness of the transaction is to be demonstrated by showing that the assessee had, in fact, received money from the said shareholder and it came from the coffers of that very shareholder. The Division Bench held that when the money is received by cheque and is transmitted through banking or other indisputable channels, the genuineness of transaction would be proved. Other documents. showing the genuineness of transaction could be copies of the areholders register, share application forms, share transfer register,
As far as creditworthiness or financial strength of the editor/subscriber is concemed, that can be proved by producing Ahe bank statement of the creditor/subscriber showing that it had sufficient balaince in its accounts to enable it to subscribe to the share capital. This judgment further holds that once these documents are produced, the assessee would have satisfactorily discharged the onus cast upon him. Thereafter, it is for the Assessing Officer to scrutinize the same and in case he nurtures any doubt about the veracity of these documents to probe the matter further. However, to discredit the documents produced by the assessee on the aforesaid aspects, there have to be some cogent reasons and materials for the Assessing Officer and he cannot go into the realm of suspicion.
15 At this stage, we would like to refer to the judgment of the Bombay High Court in the case of CIT v. Creative World Telefilms Ltd. (in I. T. A. No. 2182 of 2009 decided on October 12, 2009) [2011] 333 ITR 100. The relevant portion of this order is reproduced below:
beat hand, it is not dispute to the sesee hug given the details of name and addres of the shareholder, their PA/GIR number and had also giver the cheque number, name Investigation and reach the of the bank was expected on the part of the Assessing Officer to make proper shareholders. The Assessing Officer did nothing except issuing summons which were ultimately returned back endorsement not traceable’. In our considered view, the Assessing Officer ought to have found out their details through PAN cards, bank account details or from their bankers so as to reach the shareholders since all the relevant material details and particulars were given by the assessee to the Assessing Officer. In the above circumstances, the view taken by the Tribunal cannot be faulted. No substantial question of law is involved in the appeal. In the result, the appeal is dismissed in limine with no order as to costs.” (emphasis supplied)
16 The court thus clearly held that once documents like PAN card, bank account details or details from the bankers were given by the assessee, onus shifts upon the Assessing Officer and it is on him to reach the shareholders and the Assessing Officer cannot burden the assessee merely on the ground that summons issues to the investors were returned back with the endorsement “not traceable”. The same view is taken by the Karnataka High Court in Madhuri Investments Pvt. Ltd. v. Asst. CIT (in L. T. A. No. 110 of 2004, decided on February 18, 2006). In this case also, some of the share applicants did not appear and notices sent to them were returned with remarks “with no such person”. Addition was made on that basis which was turned down by the High Court in the following words:
”6. Having heard the learned counsel for the parties, we notice that whenever a company invites applications for allotment of shares from different applicants, there is no procedure contemplated to find out the genuineness of the address or the genuineness of the applicants before allotting the shares. If for any reason the address given in the application were to be incorrect or for any reason if the said applicants have changed their residence or the notices sent by the Assessing Officer have not been received by such applicants, the assessee-company cannot be blamed. Therefore, we are of the view that the Tribunal was not justified in allowing the appeal of the Revenue only relying upon the statement of Sri Anil Raj Mehta, a chartered accountant.”
8.1 The Hon’bl High Court further discussed the issue in paras 20 to 24 asunder:
“20 The observations of the Supreme Court in the case of Lovely Exports P. Ltd. [2009] 319 ITR (St.) 5 (SC) go to suggest that the Department is free to proceed to reopen the individual assessments in the case of alleged bogus shareholders in accordance with law and. thus, not remediless. It is, thus, for the Assessing Officer to make further inquiries with regard to the status of these parties to bring on record any adverse findings regarding their creditworthiness. This would be more so where the assessee is a public limited company and has issued the share capital to the public at large, as in such cases the company cannot be expected to know every detail pertaining to the identity and the financial worth of the subscribers. Further the initial burden on the assessee would be somewhat heavy in case the assessee is a private limited company where the shareholders are family friends/close acquaintances, etc. It is because of the reason that in such circumstance, the assessee cannot feign ignorance about the status of these parties.
21. We may also usefully refer to the judgment of the Supreme Court in the case of CIT v. P. Mohanakala [2007] 291 ITR 278, In that case, the assessee had received foreign gifts from one common donor. The payments were made to them by instruments issued by foreign banks and credited to the respective accounts of the assessees by negotiations through bank in India. The evidence indicated that the donor was to receive suitable compensation from the assessees. The Assessing Officer held that the gifts though apparent were not real and accordingly treated all those amounts which were credited in the books of account of the assessee, as their income applying section 68 of the Act. The assessee did not contend that even if their explanation was not satisfactory the amounts were not of the nature of income. The Commissioner of Income-tax (Appeals) confirmed the assessment. On further appeal, there was a difference of opinion between the two Members of the Appellate Tribunal and the matter was referred to the Vice President who concurred with the findings and conclusions of the Assessing Officer and the Commissioner of Income-tax (Appeals). On appeal, the High Court re-appreciated the evidence and substituted its own findings and came to the conclusion that the reasons assigned by the Tribunal were in the realm of surmises, conjecture and suspicion. On appeal tothe S out while revoring the decision of the High Court he has the findings of the Assessing Officer, Commissioner of Income-tox (Appeals) and the Tribunal were based on the material on record and not on any conjectures and surmises. That the money came by way of bank cheques and was paid through the process of banking transaction as not by itself of any consequence. The High Court misdirected itself and erred in disturbing the concurrent findings of fact. While doing so, the legal position contained in section 68 of the Act was explained by the Supreme Court by assessing that a bare reading of section 68 of the Act suggests that (i) there has to be credit of amounts in the books maintained by the assessee (ii) such credit has to be a sum of money during the previous year; and (iii) either (a) the assessee offers no explanation about the nature and source of such credits found in the books, or (b) the explanation offered by the assessee, in the opinion of the Assessing Officer, is not satisfactory. It is only then that the sum so credited may be charged to income-tax as the income of the assessee of that previous year. The expression “the assessee offers no explanation” means the assessee offers no proper, reasonable and acceptable explanation as regards the sums found credited in the books maintained by the assessee. The opinion of the Assessing Officer for not accepting the explanation offered by the assessee as not satisfactory is required to be based on proper appreciation of material and other attending circumstances available on the record. The opinion of the Assessing Officer is required to be formed objectively with reference to the material on record. Application of mind is the sine qua non for forming the opinion. In cases where the explanation offered by the assessee about the nature and source of the sums found credited in the books is not satisfactory there is, prima facie, evidence against the assessee, viz., the receipt of money. The burden is on the assessee to rebut the same, and, if he fails to rebut it, it can be held against the assessee that it was a receipt of an income nature. The burden is on the assessee to take the plea that even if the explanation, is not acceptable, the material and attending circumstances available on record do not justify the sum found credited in the books being treated as a receipt of income nature.
22 We would like to refer to another judgment of the Division Bench of this court in the case of CIT v. Value Capital Services P. Ltd. [2008] 307 ITR 334. The court in that case held that the additional burden was on the Department to show that even if share applicants did not have the means to make investment, the investment made by them actually emanated from the coffers of the assessee so as to enable it to be treated as the undisclosed income of the assessee. In theabsence of such findings, addition could not be made in the income of the assessee under section 68 of the Act.
23 It is also of relevance to point out that in Cit v. Stellar Investment Ltd. [1991] 192 ITR 287 (Delhi) where the increase in subscribed capital of the respondent-company accepted by the income-fax Officer and rejected by the Commissioner of Income-tax on the ground that a detailed investigation was required regarding the genuineness of subscribers to share capital, as there was a device of converting black money by issuing shares with the help of formation of an investment which was reversed by the Tribunal, this court held that even if it be assumed that the subscribers to the increased share capital were not genuine, under no circumstances the amount of share capital could be regarded as undisclosed income of the company. This view was confirmed by the apex court in CIT v. Steller Investment Ltd. [2001] 251 ITR 263.
24 Having taken note of the legal position in detail, we now proceed to decide each appeal on the application of the aforesaid principles. I. T. A. No. 2093 of 2010 and I. T. A. No. 2095 of 2010″
9 It is clear from the decision of the Hon’ble Delhi High Court in the case of Oasis Hospitalities P Ltd (supra) that once the assessee filed copy of PAN, Acknowledgement coy of the return of income of the investing companies, their bank accounts statements for the relevant period; then even the parties were not produced in spite of the specific directions of the Assessing Officer, the addition could not be sustained as the primary onus was discharged by the assessee by producing the PAN, balance sheet, copy of the acknowledgernent copy of return of the applicants etc.
10 In the case in hand, there is no dispute about the identity of the applicant companies, who had paid the application money and the source of the application money was also found in the respective bank accounts of the investing companiesand there worno trace of cash delaatit in counts of the re companies, Inen, the action of the Assessing Officer under influenced of the report of the investigation wing without giving opportunity to the assessee for cross examination of the persons, is not sustainable.
11 The Assessing Officer has raised some doubts and suspicion about the movement of the money through various levels but could not establish any direct or indirect link of the said outward movement from the assessee and then again received by the assessee in the form of application money. Even the revenue has falled to bring anything on record to show movement of the alleged cash from the assesse.
The Hon’ble Delhi High Court, in the case of Oasis Hospitalities P Ltd (supra) in and 34 has observed as under:
33 The Tribunal while confirming the aforesaid view of the Commissioner of Income-tax (Appeals) has summarized the discussion as under:
“9. We have carefully considered the rival submissions in the light of the material placed before us. The necessary details.were filed by the assessee with the Assessing Officer to show the identity of the person who had applied for the shares. The shares also been allotted to respective persons in respect of which intimation was given to the Registrar of Companies and necessary evidence has also been placed on record in the paper book which found place at pages 23 and 24 of the paper book. The assessee also had placed on record the evidence as well as copy of income-tax returns of the share applicants. Keeping in view all these evidence it cannot be held that the assessee did not establish the identity of the share applicants. If it is so, then the law as pronounced by the hon’ble Supreme Court in the case of CIT. Lovely Exports P. Ltd. (200 319 ITR (St.) 5 is clear that if the share application money is received by the assessee-company from alleged bogus shareholders whose names are given to the Assessing Officer, then the Department is free to proceed to reopen their individual assessments in accordance with law, but the same cannot be regarded as undisclosed income of the assessee. In this view of the situation, we find no infirmity in the order of the Commissioner of Income-tax (Appeals) vide which addition made on account of share application money has been deleted.”
34 Having regard to the decisions noted above, we are of the view that the addition was rightly deleted by the Commissioner of income-tax (Appeals) and the Tribunal Requisite documents were furnished showing the existence of the shareholders from bank accounts and even their income-tax details. From bank accounts of these shareholders, it was found that they had deposed certain cash and source thereof was questionable. The Assessing Officer should have made further probe which he failed to do. Moreover, the remedy of The Department lies in reopening the case of these investors and the addition cannot be made in the hands of the assessee.”
Thus, in view of the above observation of hon’ble High Court when requite document were produced and available with the A O to establish that no cash was deposited in the bank accounts of the investing companies then without further probe to prove contrary the addition in the hand of the assesse cannot be made.
13 As regards the order of the coordinate Bench of the Tribunal in assessee’s own case for AY 2005-06, it is evident that the coordinate bench of the Tribunal was also of the view that the Assessing Officer did not fully establish his case that the money has been received by the investing companies from the assessee company. The Tribunal has observed in para 11 as under:
“11. Assessee has furnished various documents in support of the contention that it has received share application money from various companies duly supported by their annual reports and Balance Sheets and evidenced in respect of cheques. The A.O. did not fully establish his argument that the monies have been received by the companies from the assessee company tological and the opinion that assessee has couled own monies. As seen then the bank accounts of the said companies enclosed as on evidence it can be noticed that those companies invariably received fund by way of cheques from another source. On the basis of enquiry in few cases the A.O. was of the of nion that all the monies were from the assessee and treated them as income from unaccounted sources. It is one of the contentions of the assessee that the assessee was not given all the statements and only 15 of the 37 statements were furnished. As seen from the record this aspect is correct. As seen from the statement recorded from the companies in Kolkata, it is noticed that they have invested in various group companies of the assessee at the same point of time. This aspect also has not been examined and the issue whether the investment in those companies by the same company was accepted or not was also not on record. Few of the companies of the assessee’s group like Luminants Investments Ltd., Netscape Software Pvt. Ltd. and Saimangal Investrade Pvt. Ltd. were also involved in getting share application money / funds as can be seen from the statement recorded by the ADIT. Sources of fund also required to be examined/correlated whether those companies have capacity to invest monies in assessee company’s case and also in other group companies and the treatment given in their cases about the source of their funds.”
3.1 Since there was a plea on behalf of the assessee that the assessee was not an opportunity to cross examine the witnesses, the Tribunal, instead of going the merits of the case, remanded the matter to the records of the Assessing per on the reason as recorded in para 13 as under:
“13. In view of the above, prima-facie it cannot be concluded that the assessee received share application money which cannot be treated as unaccounted income. Complete facts are not on record to give such a finding. However, it is noticed that the assessee was not given proper opportunity to substantiate its claim and defend the department’s observations/allegations. It is also noticed that the Department has not followed up its own investigation to its logical end and not placed on record the complete enquiries made in the case of Madhavpura Mercantile Cooperative Bank Ltd. or in the group companies so as to come to a conclusion that about the source of funds received. The status in the hands of those companies who were also alleged to have received funds in cash has not been placed on record. Since it is one of the contentions of the assessee that they were not given proper opportunity in the course of the assessment and also raised ground that adequate opportunity for cross examination of said companies has not been allowed to the assessee, we are of the opinion that the sve reg tre set aside back to the file of the A.Q. to make comple enquiry and to give proper opportunity to the assessee.”
13 There is no quarrel on the aspect that so far as it is possibile the consistency of the view has to be maintained; however, in the case of the assessee, the Tribunal, for the AY 2005-06 has not formed any opinion or given any finding on this issue; but remanded the same to the file of the Assessing Officer for fresh adjudication.
13.1 Before us, the Id AR of the assessee has forcibly urged that in view of the decision of the Hon’ble Delhi High Court in the case of Oasis Hospitalities P Ltd (supra) as well as the decision of the Hon’ble Gujarat High Court in the case of Rajeh Babubhai Damania (supra), the issue may be decided on merits on the basis of the material available on record.
14 It is to be noted that it is not the case of any additional evidence or fresh material produced by any of the parties before us which requires examination or investigation to verify the correctness of the new facts first time brought before us. The case of the revenue is that the cash moved from the assesse routed though various leveland then reached to the assesse in the form of share application money. The stand of the revenue is not in consonance with the statements of the directors of thhe investing companies which is the basis of the investigation report as well as addition by the AO. In their statements the directors stated to have received cash from assesse for investing in the preferential share of the assesse company. whereas, this fact was not found to be correct from the record and the revenue also took a stand that the cash was not directly given to the investing companies but routed through various levels. When it was found by the investigating unit as well as recorded by the AO that the fund in the bank account of the investing companies was deposited through a/c payee cheques than it is apparent that the statementsoftors are in the contradiction of the fact emerged from the well as stund of the revenues. Hence the soldi statements do not support the case of the revenue and the reliance place by the AO on such statements is highly misplaced and improper. When the stand of the revenue is in total contraction of the material on record then then in view of the latest decision of the Hon’ble Delhi High Court in the case of Oasis Hospitalities P Ltd (supra), we are of the considered opinion that the issue can be decided on merit and need not to be remand to the record of the AO because at the time of the order for the AY 2005-06, the coordinate Bench of the Tribunal was not having the benefit of the decision of the Hon’ble Delhi High Court in the case cited supra. Further in view of the decision of hon’ble Gujrat High Court in case of Rajeh Babubhai Damania (supra), we see no reason for giving the A. O. any further innings to fill up the lacunas or lapses in the assessment which would cause a great injustice to the assesse.
15 view of the above discussion and the facts and circumstances of the case, the share application money cannot be treated as income of the assessee company until and unless it is proved beyond doubt that the assesse’s own money has come back through some closely related applicant. Once the identity of the applicant is disclosed and found as correct then, even if the said transaction is suspected by the revenue authorities, the same cannot be treated as income of the assessee company which is a public limited company. Accordingly, we delete the addition made by the Assessing Officer and confirmed by the CIT(A) on thisaccount. However, we may clarify that our findings on the issue are based on respective rights of the parties for the other assessment years.”
13. In backdrop of aforesaid facts, circumstances and various orders of Tribunal following the principles / decisions of Hon’ble Higher Courts, we are of the considered view that the issue in hand shall be decided on a consistent view adopted by the Tribunal, in the case of various entities involving therein identical issue, consisting of transitions with the same entities, which are involved herein as investors for the assessee, the addition made by Ld. AO and confirmed by Ld. CIT(A) cannot sustain, as the assessee had furnished all the necessary basic documents to prove the identity of the share applicants and the revenue was unable to brought on record any material to prove that the assessee’s own money has come back through some closely held channels or related applicants.
14. We thus respectfully following the decisions of Co-ordinate Bench of Tribunal, referred to (supra), set aside the impugned order passed by Ld. CIT(A) and direct the Ld. AO to delete the impugned addition u/s 68 of the Act.
15. In result, the appeal of assessee for assessment year 2005-06, in ITA No.149/Mum/2025 is allowed, in terms of our aforesaid observations.
Order pronounced in the open court on 12-06-2026.







