
Shyam Sundar Murarka Vs ITO (ITAT, Ranchi Bench)
A Bank Credit Is Not Automatically Income: ₹1.35 Crore Addition Deleted
The Controversy
The Ranchi Tribunal granted relief on both the validity of reopening and the merits of an addition under section 69A. It quashed the reassessment initiated on the basis of an old Investigation Wing report and independently deleted the addition of ₹1,35,48,160, finding that the sources of the bank credits had been sufficiently explained.
The decision addresses two distinct issues: whether subsequently uploading an existing investigation report on the Insight Portal validated the reopening, and whether explained receipts could be treated as income merely because the underlying advances carried no interest.
Entire Bank Credits Treated as Unexplained
The Assessing Officer received information from the Investigation Wing through a report dated 17 March 2020, concerning bank deposits aggregating to ₹1,35,48,160. Of this, only ₹26,200 represented cash deposits; the remaining ₹1,35,21,960 comprised other credits.
The recorded reasons also alleged that the assessee had not filed his return for Assessment Year 2014-15. A notice under section 148 was issued on 31 March 2021.
In response, the assessee filed a return declaring income of ₹2,55,730 and explained the bank transactions. The Assessing Officer nevertheless treated the entire credits as unexplained money under section 69A.
The CIT(A) confirmed the addition, holding that adequate evidence concerning the parties and transactions had not been furnished.
Additional Legal Grounds Admitted
Before the Tribunal, the assessee raised additional grounds challenging compliance with CBDT instructions dated 4 March 2021 and the clarification dated 12 March 2021. He also disputed the allegation that no original return had been filed.
The Revenue opposed admission because these objections had not been raised before the lower authorities and the assessee had participated in the proceedings.
The Tribunal admitted the grounds, following Pawan Kumar Khandelwal v. ITO, [2026] 189 taxmann.com 84 (ITAT Ranchi) and the principle in National Thermal Power Co. Ltd. v. CIT, [1998] 229 ITR 383 (SC) concerning legal grounds arising from facts already on record.
Participation in the assessment proceedings therefore did not prevent examination of the jurisdictional challenge.
An Old Report Did Not Become New Information
The Revenue relied on the fact that the information had been uploaded on the Insight Portal on 8 March 2021, after the CBDT instructions of 4 March 2021.
However, the Tribunal found that the recorded reasons specifically referred to the manual Investigation Wing report dated 17 March 2020. They contained no discussion of information flagged on the Insight Portal.
Further, the uploaded document was the same investigation report already received manually. The Revenue produced no additional information supporting its position.
The Tribunal held that uploading the same material was a mere formality in these circumstances, while the earlier manually received report remained the actual basis of reopening. Applying the CBDT instructions and the coordinate Bench decision in Pawan Kumar Khandelwal, it quashed the section 148 notice and the consequential assessment.
It also verified that the assessee had filed his original return on 30 July 2014, contradicting the factual allegation in the recorded reasons.
The ₹1 Crore Credit Was Repayment of an Earlier Advance
The Tribunal separately examined the merits.
The principal credit of ₹1 crore represented repayment by Mayur D. Chavda of an advance given in an earlier financial year.
The assessee explained the transaction chain. Funds received from his daughter and son had originally been advanced to Ketan Madhusadan Shroff in Financial Year 2011-12. When that advance was repaid on 22 December 2012, the amount was advanced to Mayur D. Chavda.
Chavda repaid it on 28 November 2013, following which the assessee advanced the same amount to Suchit Chandrakant Patel.
The assessee referred to bank statements and confirmation supporting the earlier transactions. The current-year receipt was explained as recovery of an existing advance, rather than fresh income.
Other Credits Were Also Explained
The remaining credits included ₹18,39,500 received from the wife, ₹5,35,400 from the son, ₹1,45,000 from LIC maturity, ₹9 lakh as a refundable advance against land, ₹1 lakh as repayment of another advance, and ₹2,060 as bank interest.
The small cash deposit of ₹26,200 was explained from opening cash and withdrawals during the year.
The Tribunal found that the Revenue had not rebutted the source-wise explanation or identified discrepancies in it.
Importantly, it held that failure to charge interest did not, by itself, make the source unexplained. The CIT(A)’s reliance on human probabilities could not sustain the addition on the facts accepted by the Tribunal.
The entire section 69A addition was deleted, and the appeal was allowed.
Author’s Comments
This decision reinforces the importance of examining the nature of each credit, rather than treating the total movement through a bank account as taxable income.
At the same time, banking channels alone do not establish every transaction. The relief here rested on the explained transaction chain and the absence of identified discrepancies.
The reopening ruling also remains tied to the particular CBDT instructions governing the March 2021 period. Its practical lesson is precise: uploading old information does not necessarily change the material on which the recorded reasons actually rest.
Cases Discussed
- Pawan Kumar Khandelwal Vs ITO, [2026] 189 taxmann.com 84 (ITAT Ranchi), ITA Nos. 59, 60 & 61/Ran/2025, order dated 31.07.2026 — followed on the validity of reassessment notices issued in March 2021 where the reasons were founded on physical information received before 04.03.2021 rather than qualifying Insight Portal information.
- National Thermal Power Co. Ltd. Vs CIT, [1998] 229 ITR 383 (SC) — relied upon for the Tribunal’s jurisdiction to entertain an additional question of law where the relevant facts are already on record and no fresh factual investigation is required.
- CIT Vs Durga Prasad More, (1971) 82 ITR 540 (SC) — relied upon by the CIT(A) concerning examination of transactions in light of surrounding circumstances and human probabilities; the Tribunal did not agree with the CIT(A)’s application of that approach on the facts.
- Sumati Dayal Vs CIT, (1995) 214 ITR 801 (SC) — relied upon by the CIT(A) on the test of human probabilities; the Tribunal ultimately accepted the assessee’s source-wise explanation.
- CIT Vs Agile Properties (P.) Ltd., [2014] 225 Taxman 107 (Delhi) — cited by the assessee for the proposition that positive material is required before rejecting a reasonable explanation.
- Ram Kishan Vs ITO (ITAT Delhi), ITA No. 1909/Del/2020, dated 22.05.2022 — cited by the assessee in support of deletion of an addition under section 69A where the source stands adequately explained.
- Narender Kumar Vs ITO (ITAT Delhi), ITA No. 4006/Del/2019, dated 19.10.2022 — cited by the assessee against an addition founded on doubt and suspicion rather than evidence.
- CIT Vs Shri Jawahar Lal Oswal & Others (Punjab & Haryana High Court) — cited by the assessee against invoking deeming provisions merely on suspicion and doubt.
- H.M. Kashi Parekh & Co. Ltd. Vs CIT, 39 ITR 706 (MUM) — cited by the assessee in support of the real-income principle.
FULL TEXT OF THE ORDER OF ITAT RANCHI
1. This appeal by the assessee is directed against the order of the National Faceless Appeal Centre (NFAC), Delhi [in short, the ld. CIT(A)] dated 31/07/2025 for the Assessment Year (AY) 2014-15, wherein the assessee has raised following grounds of appeal:
“1. The order of the Commissioner of Income Tax (Appeals), NFAC, Delhi is bad in law and facts.
2. The Learned Commissioner of Income Tax (Appeals), NFAC, Delhi erred in confirming proceeding u/s 147 of the Income Tax Act, 1961.
3. The Learned Commissioner of Income Tax (Appeals), NFAC, Delhi erred in not considering the submission made and confirming addition of total credits in the bank account as unexplained u/s 69A of the Income Tax Act in spite of the sources of the credits well explained.
4. For that, other grounds if any would be urged at the time of the hearing.”
2. Facts of the case, in brief, are that during the financial year under consideration, the assessee has shown income from share dealings, commodity trading, earned interest income and received petty gifts. In the impugned assessment order dated 29/02/2022, the AO has stated that as per the information received from the Investigation Wing of the department vide F.No. DDIT-1/RAN/10058370/19-20/712m dated 17/03/2020 and on perusal of the documents available on the system, it has been gathered that the assessee has deposited a sum of ₹ 1,35,48,160/- (Cash of ₹ 26,200/- and ₹ 1,35,21,960/-) in the bank but the source of the investment has not been disclosed by the assessee and the assessee has also not filed his ITR for the A.Y. 2014-15 relevant to the F.Y. 2013-14. Thus, after analyzing the available information, the Assessing Officer recorded reasons for escapement of income for the A.Y. 2014-15 amounting to ₹ 1,35,48,160/- as under:
“Reason for issue of Notice u/s 148 for the A.Y.2013-14 in the case of Mr.SHYAM SUNDAR MURARKA
“As per the information received from investigation wing of the department and on perusal of the documents available on system, it has been gathered that the assessee has deposited Rs.1,35,48,160/- (Cash of Rs.26,200/- and Rs.1,35,21,960/- shows as income from others) in the bank but the source of investment has not been disclosed by the assessee. So, the said amount may be treated as unexplained money u/s 69A. The assessee has also not filed his ITR for the A. Yr. 2014-15 relevant to the F.Y. 2013-14.
I, therefore, have reason to believe that the amount of bank deposit to the tune of Rs.1,35,48,160/- has escaped assessment within the meaning of section 148 of the Income tax Act, 1961. Necessary approval may kindly be accorded to issue the notice under section 148 of the I. T. Act, 1961, if found fit.”
The Assessing Officer, thereafter, issued notice under Section 148 of the Income Tax Act, 1961 (in short, the Act) after obtaining the necessary approval from the specified authority i.e. ld. PCIT under Section 151 of the Act in the prescribed proforma. Notice under Section 148 of the Act dated 31/03/2021 was issued and duly served on the assessee. Subsequently, notice under Section 143(2) of the Act dated 08/02/2022 was also issued. Further notice under Section 142(1) of the Act dated 12/07/2021 and 17/12/2021 were also issued to the assessee calling for the information.
3. In response to the notice under Section 148 of the Act, the assessee filed return of income on 23/07/2021 declaring income at ₹2,55,730/- and furnished its submission on 21/12/2021 and 18/02/2022. The Assessing Officer did consider the reply of the assessee that he was engaged in share dealings, commodity trading, earned interest and received petty gifts during the assessment year under consideration and was not maintaining any books of account. It was further noted by the AO that regarding the specific query relating to cash deposit of ₹ 26,200/- and ₹ 1,35,21,960/-, the assessee failed to give satisfactory explanation and merely stated that the cash deposit was out of opening cash in hand and current year’s withdrawal and no deposits were made on account of taxable income apart from savings bank interest.
4. The Assessing Officer, however, did not accept the explanations offered by the assessee on the ground that the assessee did not produce any documentary evidence to support its claim made in the return. It was further stated by the Assessing Officer that the bank statement of ICICI bank, as produced by the assessee, was examined and it was observed that on 28/11/2013, a sum of ₹1,00,00,000/- was credited to his account No. 623501511031 of ICICI bank by one Shri Mayur D. Chavda and on the same day i.e. 28.11.2013, this amount of Rs.1,00,00,000/-was transferred to Shri Suchit Chandrakant Patel. When the assessee was asked to explain the said transaction, the assessee failed to provide any explanation or the requisite documents to substantiate the source of income for the cash deposit made in the bank. The assessee also kept quiet on the nature of transaction and failed to offer a reasonable cause to give such a big amount to Shri Mayur D. Chavda and Shri Suchit Chandrakant Patel and that too without charging any interest. Further, perusal of information revealed that the assessee stated before the DDIT(Inv.), Unit-1, Ranchi as under:
“…. amount as unsecured to Shri Mayur D Chavda on the same day. He received this amount back from Shri Mayur D Chavda on 28.11.2013 and again gave this amount to Shri Suchit Chandrakant Patel as unsecured Loan. He also claimed that he had no business dealings with Shri Ketan M Shroff, Shri Mayur D Chavda and Shri Suchit Chandrakant Patel at any period of time. He also claimed that he had received no interest from Ketan M Shroff and Mayur D Chavda”.
5. The Assessing Officer, therefore, concluded that “it is evident from the reply of the assessee that admittedly he has no business dealings with Shri Mayur D Chavda and Shri Suchit Chandrakant Patel and no interest was also charged to them for such an unsecured loan and therefore, the source remained unexplained. The assessee was further given a final opportunity alongwith show cause notice dated 21/03/2022 alongwith draft assessment order. In response to which, the assessee furnished a reply dated 23/03/2022 which is given as under”
“In reply to the same I have already submitted as under:
I have given advance of Rs. 1,00,00,000/- to Ketan Madhusadan Shroff in the FY 2011-2012 by RTGS from my ICICI Bank Account No. 623501511031. Copy of Bank statement and confirmation of Party has already been enclosed in Income Tax Portal in my previous reply to ITBA/AST/F/142(1)/2021-22/1037885981(1) dated 17.12.2021. The same has been advanced from amount received from my married daughter and my Son.
The above amount was returned by Ketan Madhusadan Shroff on 22.12.2012 in my Account No. 623501511031. Copy of Bank statement has already been submitted.
The amount received from Ketan Madhusadan Shroff, has been given as advance to Mayur D Chavda on 22.12.2012 through RTGS from ICICI Bank Ltd.
Mayur D Chavda returned the advance on 28.11.2013 in my ICICI Bank Account No. 623501511031. Copy of Bank statement has already been submitted.
The amount received from Mayur D Chavda, has been given as advance to Suchit Chandrakant Patel on 28.11.2013 through RTGS from ICICI Bank Ltd.
As per my above submission, I have already given the source of first credit in my bank account in the assessment year 2012-13. It cannot be judged that the amount advance is unexplained due to non-charging of interest or business dealings with the party.”
6. The above reply given by the assessee, however, was not accepted by the Assessing Officer on the ground that it is devoid of any merit without any documentary evidence as the assessee did not provide any documentary evidence or any explanation that what is the source of such income. It is mentioned in the assessment order that the assessee also claimed that a manual return of income was filed by him on 30/07/2014, however, the assessee failed to produce the copy of the same and also did not disclose the returned income and details of income under the various heads. The assessee claimed that interest income earned during the year under consideration was shown in the ITR. The Assessing Officer, therefore, added a sum of ₹ 1,35,48,160/- under Section 69A of the Act.
7. Aggrieved by the order of the Assessing Officer, the assessee filed appeal before the ld. CIT(A), who vide the impugned order dated 31/07/2025, dismissed the appeal of the assessee confirming the addition made by the Assessing Officer under Section 69A of the Act on the ground that the assessee has failed to prove the identity, genuineness and creditworthiness of all parties involved and has not filed legally admissible or corroborative evidence to prove the nature and source of ₹ 1,35,48,160/-. Explanation provided by the assessee is general in nature and not substantiated with any documentary evidence. Further, no loan agreements, promissory notes, receipts or notarized confirmation from alleged transacting parties were provided in respect of the parties with whom the transactions were made. All credit entries claimed to be loans or refunds, yet no interest charged, no contractual terms, nor any business rationale has been disclosed.
8. Further aggrieved by the order of the ld. CIT(A), the assessee is in appeal before this Tribunal.
9. Before us, the assessee has raised additional legal grounds during the appellate proceedings as under:
“1) For that the notice issued U/s 148 on 31/03/021 is bad in law since the same is based on the information received from the Investigation Unit vide letter dated 17/0/2020 and is not in terms with the CBDT Circular/Instructions dated 04/03/2021 read with clarification instructions dated 12/03/2021 specifying the potential cases for which proceedings U/s 148 could have been initiated from 04/03/2021 to 31/03/2021.
2) For that though the AO in the order of assessment records that the assessee did not file its ITR for the year under consideration, the same is factually incorrect as the original ITR U/s 139 was filed by the assessee on 30/07/2014 copy of which is annexed herewith for ready reference. (Linked to the 1st Additional Legal Ground).
We humbly pray that the above grounds may kindly be admitted as fresh legal ground since the same goes to the very root of assessment proceedings and no fresh document or evidence is required to be called for. We pray that the ground be kindly admitted for adjudication as a fresh legal ground being raised before your honour in the light of decision of Hon’ble Apex Court in case of NTPC VS CIT 229 ITR 383 (SC).”
10. The above legal grounds raised by the appellant was vehemently opposed by the ld. Sr. DR stating that these legal issues were not raised before the lower authorities and that since the assessee has complied before the lower authorities such legal issues cannot be raised at this stage.
11. The assessee, on the other hand, in support of its contention for admission of the legal grounds, placed reliance on para-No. 17 of the decision of the Coordinate Bench in the case of Pawan Kumar Khandelwal Vs ITO 189 taxmann.com 84 (Ranchi-Trib) which reads as under:
“17. We have considered the rival submissions. The ground raised by the assessee in the additional ground are clearly legal grounds and this ground goes to the root of the assessment. It must be reiterated here that the Income tax laws being fiscal laws are substantially complicated. It is not a subject which is easily grasped by the common man. The fact that various views get explained by various Hon’ble High Courts and matters reached the Hon’ble Supreme Court for consideration itself shows the intricacy and complexity of the tax laws. A plain reading of the tax laws would give one meaning but the reading of this law with the facts of each case can give a different interpretation. The Hon’ble Supreme Court in the case of National Thermal Power Co. Ltd. v. Commissioner of Income-tax [1999] 157 CTR 249/[1998] 229 ITR 383/97 Taxman 358 (SC) has categorically held that an appellate Tribunal has jurisdiction to entertain an additional ground of law not raised earlier, provided the relevant facts are already on record and do not require fresh investigation. The circular/instructions issued by CBDT dated 4.3.2021 and further clarificatory circular/instruction issued on 12.3.2021 prima facie shows that the reopening is invalid.”
We have considered the additional legal grounds raised by the appellant. Thus, following the above decision of the Coordinate Bench, the legal ground raised by the assessee stands admitted for adjudication.
12. Further, in support of the additional legal ground raised as well as the on merits of the case, the appellant’s counsel made a written submission as under: –
“1. That the assessee vide its additional legal grounds have challenged the validity of the proceedings initiated U/s 148 to the extent that notice issued U/s 148 dated 31/03/2021 is not in terms with the CBDT Instructions dated 04/03/2021 read with 12/03/2021 and further that the AO has erroneously stated that no ITR U/s 139(1) was filed.
2. That the undisputed fact is that the assessee for the year under consideration had filed the ITR on 30/07/2014 acknowledgment receipt of which is attached herewith to show that the original ITR U/s 139(1) has been filed and that the Ld AO erroneously and in a casual manner has stated that no ITR was filed by the assessee. This fact is incorrect and thus the very foundation of the reasons recorded for reopening being false/incorrect, such reasons cannot be sustained and the proceedings initiated there on is ab-initio void.
3. That with respect to the ground challenging the validity of the notice issued U/s 148 dated 31/03/2021, we would like to state that the same is based upon the reasons recorded specifically referring to the information received from the Investigation Wing dated 17/03/2020. Although the reasons further in a casual manner states – and on perusal of the documents available on system, however no specific details of the same has been mentioned.
4. That though the revenue in its reply has stated that as per the Insight Portal, the information has been uploaded on 08/03/2021, however nowhere from the reasons recorded nor the order of assessment there is any whisper about any information uploaded in the Insight Portal.
5. That on perusal of the printout of the Insight Portal which the revenue department has submitted, it has been seen that the document which was uploaded online was nothing but only the copy of the information which was supplied vide letter dated 17/03/2020. The same can be verified under the document name which has been uploaded. No new or extra material was uploaded in the Insight Portal to support the reopening and it is definitely not the case of the revenue that despite manual information has been received from the Investigation Unit, no action U/s 148 would have been initiated in absence on the same being flagged online in the Insight Portal.
6. That the intent behind flagging of the information in the Insight Portal is nothing but to merely communicate the information to the concerned officer in a digital format in view of moving towards Digital India & Viksit Bharat. However, the undisputed fact is that the Ld AO has acted upon the information which was received manually vide letter dated 17/03/2020 and not only after the same has been uploaded on 08/03/2021 as submitted by the revenue department.
7. That the CBDT vide circular/ instructions dated 04/03/2021 and 12/03/2021, has categorically stated the potential cases in which proceedings U/s 148 could have been initiated by the JAO for the period between 04/03/2021 to 31/03/2021. Vide the said instructions, it has been mentioned that only in those cases where the information has been flagged on or after 04/03/2021 by the Investigation Unit, can the proceedings U/s 148 be initiated.
8. That once the information has been passed on manually and the reasons recorded refers to such manual information, uploading the same on the Insight Portal becomes a mere procedural formality and not a condition precedent for initiation of proceedings U/s 148.
9. That as stated above and the documents available on record, it can be seen that the Ld AO has only formed the reasons on basis of the information received from the Investigation Unit vide letter dated 17/03/2020. This was the only letter which was uploaded in the Insight Portal on 08/03/2021 and there was no other additional/ fresh material which could have formed the basis for reasons to reopen. As such, ideally the proceedings U/s 148 has been initiated on basis of the information received by the Ld AO vide letter dated 17/03/2020 i.e. much before 04/03/2021 and thus, the notice issued U/s 148 dated 31/03/2021 is bad in law and assessment framed thereby is fit to be quashed.
10. That on this issue we rely upon the decision of the Co-ordinated Bench in the case of Pawan Kumar Khandelwal vs. ITO [2026] 189 taxmann.com 84 (Ranchi – Trib.) [31-07-2026] wherein on similar facts, the Hon’ble Bench taking cognizance of the CBDT Instructions dated 04/03/2021 and 12/03/2021 has held the initiation of proceedings to be ab-initio void and quashed the assessment. A copy of the said order is placed on record for ready reference.
11. That further on merits of the case, it is submitted that the addition made for Rs. 1,35,48,160/- as alleged unexplained money U/s 69A, we would like to submit that complete details of the same was furnished before the lower authorities, a brief table for which is as below:-
| Name of Person | Amount | Details |
|---|---|---|
| Sangeeta Murarka (Wife) | Rs. 18,39,500/- | ICICI Bank Statement of Wife to show corresponding Cash withdrawals |
| Harsh Murarka (Son) | Rs. 5,5,400/- | ICICI Bank statement of Son as well as his Proprietorship concern to show corresponding Cash withdrawals |
| LIC Maturity | Rs. 1,45,000/- | LIC Certificate and maturity receipt |
| M/s Rachit Developers | Rs. 9,00,000/- | Refundable advance for land – Confirmation letter with supporting documents |
| Manohar Lal Agarwal | Rs. 1,00,000/- | Return of advance – confirmation letter |
| Mayur D Chavda | Rs. 1,00,00,000/- | Return of Advance/ loan given on 22/12/2012 source of which stands accepted in the previous year i.e. AY 2013-14 wherein AO made accepted the principle amount and made the addition of notional/ accrual interest which was subsequently deleted by the Hon’ble ITAT vide order dated 05/03/2026 in ITA No. 286/Ran/2025. A copy of the assessment order and ITAT order for AY 2013-14 is placed on record. |
| Bank Interest | Rs. 20,000/- | Copy of Bank Statement |
| Cash Deposit | Rs. 26,200/- | Past saving and drawings – bank statement. |
12. That all the relevant documents for the above said credit transactions were furnished before the lower authorities who have failed to conduct any sort of further enquiry and has dismissed the contentions of the assessee in a hasty manner. Once when the assessee has duly explained the source of the deposits and no specific adverse comments have been made no addition U/s 69A is called for.
We shall be obliged for your kind consideration and necessary orders.”
13. To examine the veracity of the submissions made by the appellant’s counsel stated as above, we asked the Revenue to submit the print out of the Insight portal which was produced by the Sr. DR as under: –
Verification Details
Personal Details
| Particulars | Details | Particulars | Details |
|---|---|---|---|
| PAN | ACNPM4222F | DoB/ Incorporation | |
| Name | SHYAM SUNDAR MURARKA | ||
| Address | MURARKA HOUSE, MAIN ROAD (ALBERT EKKA HOWK), RANCHI | ||
| State | Jharkhand | Pincode | 834001 |
| – | Mobile | – | |
| Jurisdictional PCIT | – |
Information Details
| Information FY | Information Source Type | Information Source Description | Information Type | Information Description | Information Value |
| 2012-13 | Suspicious Transaction Report | STR | Others | UNEXPLAINED MONEY | – |
| 2013-14 | Suspicious Transaction Report | STR | Others | UNEXPLAINED MONEY | – |
| 2014-15 | Suspicious Transaction Report | STR | Others | UNEXPLAINED MONEY | – |
| 2016-17 | Suspicious Transaction Report | STR | Others | UNEXPLAINED MONEY | – |
| 2017-18 | Suspicious Transaction Report | STR | Others | UNEXPLAINED MONEY | – |
Verification Details
| Nature of Verification | Enquiry |
Verification Result
| Actionable AY | Result Type | Result Description | Result Value | Remarks |
|---|---|---|---|---|
| 2013-14 | Unexplained Investment/Payment | UNEXPLAINED MONEY | 1,15,61,157 | – |
| 2014-15 | Unexplained Investment/Payment | UNEXPLAINED MONEY | 1,35,48,160 | – |
| 2015-16 | Unexplained Investment/Payment | UNEXPLAINED MONEY | 8,40,613 | – |
Verification Result (Continued)
| Actionable AY | Result Type | Result Description | Result Value | Remarks |
|---|---|---|---|---|
| 2017-18 | Unexplained Investment/Payment | UNEXPLAINED MONEY | 2,96,247 | – |
| 2018-19 | Unexplained Investment/Payment | UNEXPLAINED MONEY | 6,79,046 | – |
Documents
| S.No. | Document Type | Document Description | Remarks | Document Name | Size (KB) |
|---|---|---|---|---|---|
| 1 | OTHER | SHARE INFORMATION | – | Shri Shyam Sundar Murarka 3(1), Ran 17032020 712.PDF | 317 |
Upload Details
| Particulars | Details | Particulars | Details |
|---|---|---|---|
| Upload ID | 1000006021 | Uploaded On | 08-03-2021 |
| VSN | 1 | Reference Number | |
| Uploaded By | ATUL KUMAR, DDIT INV Unit-1,Ranchi | ||
| Parent ID | – | Updated On | – |
| Updated By |
The Ld. Sr. DR also made a submission to rebut the claim of the appellant’s counsel as under: –
“A 2-page print-out of the Insight Portal depicting the verification result of the appellant’s case is submitted herewith. It inter alia contains the information w.r.t the relevant AY and the date – 08-03-2021 to be exact – on which the information had been uploaded by the DDIT(Inv) Unit-1 Ranchi.
It shows the Result Value of unexplained money is Rs 1,35,48,160/-.
This submission is suo motu made in response to the additional grounds sought to be taken by the appellant before the Ld ITAT. The allegations that the AO did not follow the Board’s Instruction were based on surmises without bringing on record any material facts.
This opportunity is craved to pray before your Honours to dismiss the frivolous appeal, of the assessee seeking to avoid to face the merits head-on, with costs as your Honours may deem fit.”
14. On going through the rival submissions, we find that the very foundation of the reasons recorded by the AO that the assessee did not file original return under Section 139 is factually incorrect as the return was duly filed by the assessee on 30/07/2014, a copy of which has been reproduced as below:
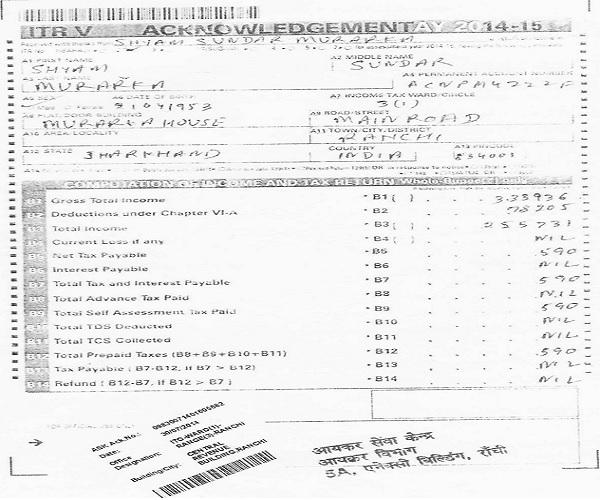
Thus, the allegation of the Assessing Officer that no return has been filed by the assessee which led to escapement of income is not correct.
15. Further, with respect of the validity of the notice under Section 148 of the Act dated 31/03/2021, the ld. AR of the assessee stated that the same is not in terms with CBDT Instruction dated 04/03/2021 read with 12/03/2021. The Circular dated 04/03/2021 and 12/03/2021 is reproduced as below:
F. No. 225/40/2021/ITA-II
Government of India
Ministry of Finance
Department of Revenue
Central Board of Direct Taxes
New Delhi, the 4th March, 2021
To
All Pr. Chief-Commissioners of Income-tax/ Chief-Commissioners of Income-Tax
Madam/Sir,
Subject: Instructions regarding selection of cases for issue of notice u/s 148 of the Income-tax Act, 1961 – regarding.
The Central Board of Direct Taxes (Board), in exercise of its powers u/s 119 of the Income-tax Act, 1961 (Act), with an objective of streamlining the process of selection of cases for issue of notices u/s 148 of the Act, hereby directs that the following categories of cases be considered as “potential cases” for taking action u/s 148 of the Act by 31.03.2021 for the A.Y. 2013-14 to A.Y. 2017-18 by the Jurisdictional Assessing Officer (JAO):
i. Cases where there was an Audit Objection (Revenue/Internal) which requires action u/s 148 of the Act;
ii. Cases of information from any other Government Agency/Law Enforcement Agency which require action u/s 148 of the Act;
iii. Potential cases including:-
(a) Reports of Directorate of Income-tax (Investigation),
(b) Reports of Directorate of Intelligence & Criminal Investigation,
(c) Cases from Non-Filer Management System (NMS) & other cases as flagged by the Directorate of Income-tax (Systems) as per risk profiling;
iv. Cases where information arising out of field survey action, requiring action u/s 148 of the Act;
v. Cases of information received from any Income-tax authority requiring action u/s 148 of the Act with the approval of Chief Commissioner of Income Tax concerned.
2. No other category of cases, except the above, shall be considered for taking action u/s 148 of the Act by the JAO.
3. It is clarified that action u/s 148 of the Act shall be taken by the Assessing Officer in respect of the above categories of cases after forming a reasonable belief that income chargeable to tax has escaped assessment and ‘reasons to believe’ shall be recorded and required sanction as per section 151 of the Act shall be obtained before issuing notice u/s 148 of the Act.
4. These instructions shall not be applicable to the Central charges and International Taxation charges for which separate instructions are being issued.
5. Issues with the approval of the Chairman, CBDT.
(Rajarajeswari R.)
Under Secretary-ITA-II, CBDT
F. No. 225/40/2021/ITA-II
Government of India
Ministry of Finance
Department of Revenue
Central Board of Direct Taxes
New Delhi, the March, 2021
To
All Principal Chief Commissioners of Income-tax
Madam/Sir,
Subject: Instructions regarding selection of cases for issue of notice u/s 148 of the Income-tax Act, 1961—clarification to CBDT’s letter dated 04.03.2021-reg
1. With reference to CBDT’s Instruction dated 04.03.2021 on the above-mentioned subject, it has been decided to clarify as under:
(a) The ‘potential cases’ at Point no.1(iii) mean the cases flagged by the Directorate of Income-tax (Systems) subsequent to 04.03.2021. It is further clarified that the NMS cases flagged earlier will get subsumed in the new list.
(b) With respect to criterion at Point no.1(v), it is clarified that ‘any other Income-tax Authority’ includes the Assessing Officer (A.O.) herself/himself. Further, the information received as per Point no.1(v) shall not include information received from Directorate of Income-tax (Investigation), Central Charges and Directorate of Income-tax (Intelligence and Criminal Investigation) after 01.04.2019.
(c) With respect to the condition at Point no.1(v), that cases are to be considered as potential cases for issue of notice u/s 148 of the Act ‘with the approval of CCIT concerned’, it is clarified that the CCIT shall call for the list of the potential cases along with details and evidences from the Subordinate Authorities and shall, after careful examination, suggest to the A.O., the potential cases to be taken for consideration for action u/s 148 of the Act.
2. Subsequent to the issuance of notice u/s 148 of the Act, the A.O. shall upload all the underlying documents relied upon and satisfaction recorded, in the ITBA Module for all category of cases in Para no.1 of CBDT’s Instruction dated 04.03.2021.
3. This issues with the approval of Chairman, CBDT.
(Ravinder Maini)
Director (ITA-II), CBDT
Copy to:
i. PS to FM/PS to MoS(F)
ii. PS to Revenue Secretary
iii. Chairman, CBDT & All Members, CBDT
iv. All Pr.DGsIT/DGsIT
v. All Joint Secretaries/CsIT, CBDT
vi. JCIT, Data-Base Cell for uploading on irsofficersonline website
(Ravinder Maini)
Director (ITA-II), CBDT
16. It was submitted by the appellant’s counsel that on bare perusal of the above said instructions issued by the CBDT and considering the facts of the case, it is understood that notice under Section 148 of the Act could only have been issued by the Assessing Officer wherein information has been flagged by the Director of Income Tax subsequent to 04/03/2021. However, in case of the assessee, it is observed that the Assessing Officer had received the information manually vide letter report of the Investigation Unit dated 17/03/2020 which was the same piece of information uploaded on the insight portal on 08/03/2021. The crux of the arguments of the ld. AR of the assessee is that the reasons recorded is based upon the manual information received vide Investigation Unit report dated 17/03/2020 whereas the ld. Sr. DR has vehemently argued that since the information has been uploaded on the insight portal on 08/03/2021 i.e. subsequent to 04/03/2021, there is no irregularity in the notice issued under Section 148 of the Act dated 31/03/2021.
17. We find, on examination of the documents available on record and the reasons recorded, that the Assessing Officer has specifically referred to the manual information/report of the Investigation Unit dated 17/03/2020 and that there is no discussion or mention about any information uploaded/flagged on the insight portal. Further, the revenue has failed to bring on record any other additional evidence or information uploaded on the insight portal except the said report of the Investigation Unit dated 17/03/2020 which undoubtedly had been received manually prior to 04/03/2021 and that formed the basis of reopening. We further find force in the argument of the ld. AR contending that once the information has been passed on manually to the Assessing Officer of the assessee, uploading the same on the insight portal becomes a mere formality and not a condition precedent for initiation of proceedings under Section 148 of the Act.
Obviously it is not the case of the revenue that no proceedings U/s 148 would have been initiated if the information was not uploaded on the Insight Portal irrespective of the date. The information sent manually to the Jurisdictional Assessing Officer suffice the communication of the same for the purposes of examination and reassessment. Thus, the information sent by the Investigation Unit letter dated 17/03/2020 forms the basis for reopening U/s 148 and since the same is done prior to 04/0/2021, abiding by the CBDT circulars as above, we hold that the initiation of proceedings is itself ab-initio void.
18. We also find that on the same issue, the Coordinate Bench of this Tribunal has already decided this issue in Pawan Kumar Khandelwal vs. ITO in ITA No.59, 60 & 61/Ran/2025 order dated 31/07/2026 wherein it has been held as under:
“Admittedly, the reasons recorded do not refer to Insight portal information. The figures had not been tallied with the Insight Portal information. There is no way to link the said information on the basis of which the Assessing Officer has issued notice under section 148 or recorded the reasons for the purpose of reopening the assessment with Insight Portal information. However, it is noted that the figures mentioned in the reasons recorded tallies with those mentioned in the physical information provided by the DDIT/ADIT(Inv) Dhanbad on 29-1-2021 in the physical form. This being so, the Tribunal is left with no other option but to hold that the reopening has been done on the basis of the physical information made available to the Assessing Officer vide letter dated 29-1-2021 and received on 2-2-2021, which is prior to 4-3-2021. Consequently, in view of the circular issued by CBDT dated 4-3-2021 read with clarificatory circular issued on 12-3-2021, the notices issued on 26-3-2021 and 27-3-2021 are in violation of circular/instructions issued by CBDT referred to supra.
Consequently, the notices under section 148 stand quashed and consequential assessments also stand quashed. Hence, additional ground raised by the assessee stands allowed. The other grounds as raised by the assessee are not being adjudicated insofar as the additional ground has been allowed and assessments have been quashed. [Para 20]
In the result, appeals of the assessee stand allowed. [Para 21)”
19. Thus, respectfully following the order of the Coordinate Bench of this Tribunal in the above case we quash the notice issued by the AO under Section 148 of the Act and consequentially the assessment order passed in this case. Hence, additional legal grounds raised by the assessee stands allowed.
20. We have also considered this case on merit. The assessee has contended that even on the merit of the case, his case is very strong. In support of this contention, the assessee has also made a written submission as under:
“During the financial year under consideration, the assessee was engaged in share dealings, commodity trading, earned interest income, and received petty gifts. As per the information received by the Assessing Officer from the investigation wing of the department vide F.NO. DDIT-1/RAN/10058370/19-20/712 dated 17.03.2020 and on perusal of the documents available on the system, it was gathered by him that the assessee has deposited Rs.1,35,48,160/- (Cash of Rs.26,200/- and Rs.1,35,21,960/-) in the bank but the source of investment has not been disclosed by the assessee and the assessee has also not filed his ITR for the A.Y. 2014-15 relevant to the F.Y. 2013-14. The case was re-opened u/s 147 and notice u/s 148 of the Income Tax Act, dated 31.03.2021 was issued. In response to the notice u/s 148 of the Income Tax Act, I have filed a return of income on 23.07.2021 declaring income of Rs. 2,55,730/- and furnished the same along with my submission on 21.12.2021 and 18.02.2022. All the details and explanations to the various notices received have been filed but the assessing officer has ignored the same.
The final assessment order u/s 147 r.w.s 144 was passed on 29.03.2022 with the addition of Rs. 1,35,48,160/-i.e., total credit in ICICI bank account as unexplained money u/s 69A of the Income Tax Act without considering the replies/submission filed against the same and hence the appeal filed.
show cause notice issued by the assessing officer claimed that assessee has not filed a return u/s 139 is wrong as assessee has filed a manual return u/s 139 on 30.07.2014 vide ASK Ack. No. 09830071401605682.
In response to Point No. 5 of notice ITBA/AST/F/142(1)/2021-22/1037886032(1) dated 17.12.2021 I have replied as under:-
“Details of Various Deposit in my Bank accounts is enclosed, Cash has been deposited out of my opening Cash in Hand and Current Year withdrawals. It can be seen from our explanation that no deposits are on account of taxable income apart from Saving Bank Interest.”
As per the above details Cash of Rs. 26,200/- only has been deposited in whole financial year. Copy of bank statement has already been submitted. Extracts of other credits are as under:-
| Particulars | Amount Credited (In Rs.) |
|---|---|
| Receipt from my wife Sangeeta Murarka | 18,39,500 |
| Receipt from LIC Maturity | 1,45,000 |
| Receipt from my son Harsh Murarka | 5,35,400 |
| Receipt from Rachit Developers as a refundable advance against Land | 9,00,000 |
| Bank Interest | 2,060 |
| Refund of Advance given to Mayur D Chavda | 1,00,00,000 |
| Refund of Advance given to Manohar Lal Agarwal | 1,00,000 |
| Cash Deposit | 26,200 |
| Total Credit in Bank Accounts | 1,35,48,160 |
Section 69A Unexplained Money, etc
Where in any financial year the assessee is found to be the owner of any money, bullion, jewellery, or other valuable article and such money, bullion, jewellery or valuable article is not recorded in the books of account, if any, maintained by him for any source of income, and the assessee offers no explanation about the nature and source of acquisition of the money, bullion, jewellery or other valuable article, or the explanation offered by him is not, in the opinion of the Assessing Officer, satisfactory, the money and the value of the bullion, jewellery or other valuable article may be deemed to be the income of the assessee for such financial year.
Conditions to be satisfied for applicability of section 69A
From the reading of section 69A, the following conditions can be stated to attract the applicability of section 69A:
-
- The assessee is found to be the owner of any money, bullion, jewellery or other valuable articles; and
- Such money, bullion, jewellery or other valuable articles when not recorded in the books of account, if any maintained by the assessee for any source of income: and
- The assessee offers no explanation about the nature and source of acquisition of the money, bullion, jewellery or other valuable article, or the explanation offered by him is not, in the opinion of the Assessing Officer, satisfactory
As such some positive evidence is needed and subjective opinion would be inadequate material for the Assessing Officer to constitute evidence before rejecting a reasonable explanation furnished by the assessee as held in CIT v. Agile Properties (P.) Ltd. [2014] 225 Taxman 107 (Delhi)
In the case of Ram Kishan Vs ITO (ITAT Delhi) ITA No. 1909/Del/2020 Date of Judgement 22.05.2022 the tribunal held that if the source of income is adequately explained during the assessment, there should be no addition under Section 69A.
In the case of Narender Kumar Vs ITO (ITAT Delhi) ITA No. 4006/Del/2019 Date of Judgement 19.10.2022 the Tribunal held that the disputed addition has been made more on doubt and suspicion rather than based on evidence and thereby deleted the addition
CIT Vs Shri Jawahar Lal Oswal & others (Punjab & Haryana High Court) Deeming provision cannot be initiated on the basis of suspicion and doubt.
Only the real income of the assessee is liable to tax as held in H.M. Kashi Parekh & Co. Ltd vs. CIT 39 ITR 706 (MUM).
Various courts have held that presumption, however, strong, cannot be a substitute, nor can it take the place of evidence, and the rule of estimation is no substitute for evidence.”
21. The ld. Sr. DR, on the other hand, relied on the orders of the lower authorities.
22. We have considered the facts of the case and the impugned order passed by the ld. CIT(A) who has confirmed the order of the Assessing Officer by holding that the assessee has failed to prove the identity, genuineness and creditworthiness of all the parties involved and has not filed legally admissible or corroborative evidence to prove the nature and source of ₹ 1,35,48,160/. The explanation provided by the assessee is general in nature and not substantiated with any documentary evidence. No loan agreements, promissory notes, receipts, or notarized confirmations from alleged transacting parties were provided. All credits were claimed to be loans or refunds, yet no interest charged, contractual terms, or business rational has been disclosed. It was further held by the ld. CIT(A) that the case also finds strong support from the two landmark judgments of Hon’ble Supreme Court of India wherein the vital principle of test of human probabilities was propounded and followed in the case of CIT vs. Durga Prasad More (1971) 82 ITR 540 (SC) and Sumati Dayal vs. Commissioner of Income tax (1995) 214 ITR 801 (SC) wherein the Hon’ble Supreme Court has held that even if a transaction or entry prima facie appeared to be legal and duly supported by documentary evidence, the tax authorities not only have right but also an obligation to make better enquiries and examination, the transaction in the light of surrounding circumstances and test of human probabilities to uncover its real nature.
23. We have considered the findings of the ld. CIT(A) given on the facts of the case. However, we do not agree with his findings. In the present case, the assessee has never denied that it has not received a sum of ₹ 1,35,48,160/- and the same has been disclosed by the assessee in his return of income and all the transactions have been made through banking channels and none of the transaction was doubted by the Assessing Officer. It was further submitted by the appellant’s counsel that the Assessing Officer has wrongly mentioned in the assessment order that the assessee has not filed his return of income for the A.Y. 2014-15 which is contrary to the fact that the return of income was filed by the assessee, being the original return of income, on 30.07.2014. Further, the source of various deposits in the bank accounts is also explained by showing that it has come up from its opening cash in hand and current year withdrawals. Simply because it has not charged interest, it cannot be said that the source of the said deposit is not explained. The appellant’s counsel has also submitted the extracts of other credits, the total of which comes to ₹ 1,35,48,160/- and claimed that it sufficiently explained before the Assessing Officer. The table explaining the source of deposit is as under, contents of which could not be rebutted by the revenue:-
| Name of Person | Amount | Details |
|---|---|---|
| Sangeeta Murarka (Wife) | Rs. 18,39,500/- | ICICI Bank Statement of Wife to show corresponding Cash withdrawals |
| Harsh Murarka (Son) | Rs. 5,5,400/- | ICICI Bank statement of Son as well as his Proprietorship concern to show corresponding Cash withdrawals |
| LIC Maturity | Rs. 1,45,000/- | LIC Certificate and maturity receipt |
| M/s Rachit Developers | Rs. 9,00,000/- | Refundable advance for land – Confirmation letter with supporting documents |
| Manohar Lal Agarwal | Rs. 1,00,000/- | Return of advance – confirmation letter |
| Mayur D Chavda | Rs. 1,00,00,000/- | Return of Advance/ loan given on 22/12/2012 source of which stands accepted in the previous year i.e. AY 2013-14 wherein AO made accepted the principle amount and made the addition of notional/ accrual interest which was subsequently deleted by the Hon’ble ITAT vide order dated 05/03/2026 in ITA No. 286/Ran/2025. A copy of the assessment order and ITAT order for AY 2013-14 is placed on record. |
| Bank Interest | Rs. 20,000/- | Copy of Bank Statement |
| Cash Deposit | Rs. 26,200/- | Past saving and drawings – bank statement. |
24. Regarding the decisions of the Hon’ble Supreme Court on which the ld. CIT(A) placed reliance, the appellant’s counsel submitted that when the hard evidence was available before the Assessing Officer, there is no question of human probabilities and thus, it is wrong on the part of the Assessing Officer and the ld. CIT(A) to conclude that the said deposits remained unexplained. The appellant’s counsel also placed reliance on the various case laws i.e. CIT v. Agile Properties (P.) Ltd. [2014] 225 Taxman 107 (Delhi), Ram Kishan Vs ITO (ITAT Delhi) ITA No. 1909/Del/2020 dated 22.05.2022, Narender Kumar Vs ITO (ITAT Delhi) ITA No. 4006/Del/2019 dated 19.10.2022, CIT Vs Shri Jawahar Lal Oswal & others (Punjab & Haryana High Court) and H.M. Kashi Parekh & Co. Ltd vs. CIT 39 ITR 706 (MUM) in support of its claim wherein Hon’ble ITATs have held that if the source of income is adequately explained, no addition can be made under Section 69A of the Act.
25. We have carefully considered the entire facts of the case, the judicial decisions and the rival submissions and it is found that the assessee has fully explained the source of deposits of Rs. 1,35,48,160/- by giving sufficient explanations. The Assessing Officer, on the other hand, did not bring out any discrepancy in that explanation. The ld. CIT(A) also not pointed out any discrepancy in the explanation given by the assessee. Thus, no addition is called for under Section 69A of the Act and the same is deleted.
26. In the result, this appeal of the assessee stands allowed.
Order pronounced in open court on 30/09/2026.







