
Aadi Sristhi Manglam Samiti Vs CIT (Exemption) (ITAT Jaipur)
Wrong Clause in Form 10AB Cannot Defeat Trust Registration — Jaipur ITAT Orders Fresh Consideration
Summary: The Jaipur ITAT held that a trust should be allowed to correct a bona fide error in selecting the statutory clause in Form 10AB. The Commissioner of Income Tax (Exemption) had cancelled the trust’s earlier registration and refused final registration under section 12AB. The Tribunal set aside both orders and directed the CIT(E) to consider the rectified application under section 12A(1)(ac)(iii) after giving the trust an opportunity of hearing.
Trust formed before 1 April 2021 selected the clause for previously registered trusts
Shri Aadi Sristhi Manglam Samiti was registered as a trust on 15 February 2016. It filed Form 10A on 28 March 2022, selecting section 12A(1)(ac)(i). The Department issued a registration order on 5 April 2022, valid through AY 2026–27. The Tribunal recorded that the trust filed its returns for AYs 2022–23 to 2025–26, with no adverse findings recorded by the assessing authority.
The trust subsequently filed Form 10AB on 30 September 2025 and again selected sub-clause (i). The CIT(E) issued a show-cause notice questioning the earlier grant because the trust had held no income-tax registration under the pre-amendment provisions. Sub-clause (i) was the transition route for trusts already registered under the earlier income-tax regime. The trust’s establishment in 2016 was the fact that had led it to select that clause.
CIT(E) cancelled the earlier registration and rejected Form 10AB
The trust explained that it had misunderstood the provision because it came into existence before 1 April 2021. It submitted that selecting sub-clause (i) gave it no advantage and requested the CIT(E) to treat the application as one under sub-clause (iii), the route for a provisionally registered trust seeking regular registration.
The CIT(E) took the view that he had no power to consider an application under a clause different from the one selected in the form. He therefore cancelled the earlier registration. He also rejected the subsequent Form 10AB application on the ground that the trust was ineligible once the earlier registration had been cancelled. The trust challenged both orders before the Tribunal.
ITAT treats the wrong selection as a curable error
The Tribunal noted the difficulties that trusts, professionals and tax authorities had faced in applying the registration provisions introduced from 1 April 2021. It also referred to the clarifications issued by the CBDT and the extensions granted from time to time. In this case, the relevant facts were already before the CIT(E), and the Tribunal found that the incorrect clause was the obstacle to consideration of the application.
The Bench followed Aatman Foundation v. CIT(E) [174 taxmann.com 1109 (Ahmedabad–Trib.)], Gandhinagar Ayyapa Pooja Samiti v. CIT(E) [174 taxmann.com 901 (Ahmedabad–Trib.)] and Rotary Charity Trust v. CIT(E) [170 taxmann.com 797 (Mumbai–Trib.)]. These decisions treated an inadvertent reference to the wrong clause as a curable defect and remitted the applications for consideration under the correct provision.
The Tribunal accordingly set aside both orders and directed the CIT(E) to consider the rectified application under section 12A(1)(ac)(iii), give the trust a hearing and grant registration in accordance with law. Both appeals were allowed for statistical purposes. The application now falls to be decided by the CIT(E) on remand.
Author’s Comments
A trust’s date of formation and its prior income-tax registration status answer different questions. In this case, the trust’s existence before 1 April 2021 explained the choice of sub-clause (i). Eligibility for that transition route depended on whether it already held registration under the earlier income-tax provisions. The Tribunal allowed the trust to correct the selection so that its application could be examined under the provision applicable to its registration status.
The filing deadline is a separate issue. Under sub-clause (iii), the timing generally depends on the expiry of provisional registration and the commencement of activities, with the earlier statutory deadline governing. The Jaipur ruling is useful where the facts supporting the correct route are already on record and a bona fide error in the form has prevented consideration. The remand gives the trust a hearing and a decision under the correct clause, subject to the statutory conditions.
Cases Discussed
- Aatman Foundation Vs CIT(E) (ITAT Ahmedabad); 174 taxmann.com 1109.
- Gandhinagar Ayyapa Pooja Samiti Vs CIT(E) (ITAT Ahmedabad); 174 taxmann.com 901.
- Rotary Charity Trust Vs CIT(E) (ITAT Mumbai); 170 taxmann.com 797.
FULL TEXT OF THE ORDER OF ITAT JAIPUR
These two appeals are filed by the assessee as against two separate orders both dated 23.03.2025 passed by the Commissioner of Income Tax (Exemption), Jaipur canceling the provisional registration already granted and also denying final registration u/s 12AB of the Income Tax Act, 1961 (hereinafter referred to as ‘the Act’). Shri Aadi Sristhi Manglam Samiti
2. Brief facts of the case are, the assessee is a trust incorporated vide registration dated 15.02.2016. The assessee filed Form 10A on 28.03.2022 u/s 12(1)(ac)(i) which was granted registration vide order dated 05.04.2022 upto Assessment Year 2026-27. Thereafter, the assessee filed its Return of Income from the Assessment Years 2022-23 to 2025-26 where no adverse findings recorded by the assessing authority. The assessee filed application in Form 10AB on 30.09.2025 under section 12(1)(ac)(i) of the Act for renewal registration i.e. within time, i.e. six months before expiry of the provisional registration. Ld. CIT(E) issued a show cause notice to withdrawal the provisional registration granted on 05.04.2022 on the ground that the assessee trust did not hold a registration in the pre-amended provision and was therefore not entitled to apply under sub-clause (i) of section 12A(1)(ac) of the Act. The assessee vide reply letter dated 29.12.2025 explained that the trust under bona fide error of understanding that the society came into existence prior to 01.04.2021 i.e. from 15.02. 2016. Thus, the assessee stood to gain nothing whatever apply under sub-clause(i) rather than under other sub-clauses, therefore, requested to treat the application under sub-clause (iii) of section 12A(1)(ac) of the Act. Considering the above reply, ld. CIT(E) has held that he has no power to consider the application filed in incorrect clause, therefore, the registration granted on 05.04.2022 was cancelled following the same. Ld. CIT(E) also denied final registration filed by the assessee as not eligible for registration.
3. Aggrieved against the same, the assessee is in appeal before us raising the following grounds of appeal:-
ITA No. 891/JPR/2026
“1. The Ld CIT(E) has erred in concealing the registration granted on form 10AC for A.Y, 2022-23 to A.Y. 2026-27 wef 5.4.2022 on filing of application under wrong sub clause (i) of sec. 12A(1)(ac) instead of clause (iii) and rejecting the explanation furnished and also refused to consider the application filed under clause (i) to be considered as filed under clause (iii).
2. The Ld. CIT(E) has also not considered that the this error was neither pointed out before granting the registration nor in the span of five years thereafter.
3. The Ld. CIT(E) not found any adverse information or comments on the working and compliances made by the appellant before cancelling the registration.
4. The order of the Ld. CIT(E) is against law and facts of the case.
5. The appellant craves the right to add, amend or withdrew any grounds of appeal at the time of hearing.
ITA No. 894/JPR/2026
“1. The Ld CIT(E) has erred in rejecting the renewal of application on Form 10AB dated 30.9.2025 for the registration granted on form 10AC for A.Υ. 2022-23 to A.Y. 2026-27 wef 5.4.2022 on the ground that the certificate of registration on form 10AC has been concealed wef 5.4.2022. Hence the present application is deficient /not eligible.
2. The Ld. CIT(E) not found any adverse information or comments on the working and compliances made by the appellant before cancelling the registration.
3. The order of the Ld. CIT(E) is against law and facts of the case.
4. The appellant craves the right to add, amend or withdrew any grounds of appeal at the time of hearing
4. We have considered rival submissions and perused the materials available on record. Section 12A(1)(ac) was introduced by the Finance Act, 2020, and became effective from 1st April 2021. It provides for mandatory re-registration or fresh registration for trusts and institutions under certain conditions. This provision replaced the earlier system of permanent registration with a renewable registration regime for every five years. It mandates a Trust to apply in prescribed circumstances for:
- New registration (first-time applicant),
- Provisional registration (for new entities),
- Re-registration (due to modification or expiry),
- Fresh registration (due to missed deadlines, etc.).
4.1 For better understanding the clauses (i) to (vi) of section 12A(1)(ac) of the Act, which are applicable to various categories of Trust are tabulated as follows:-
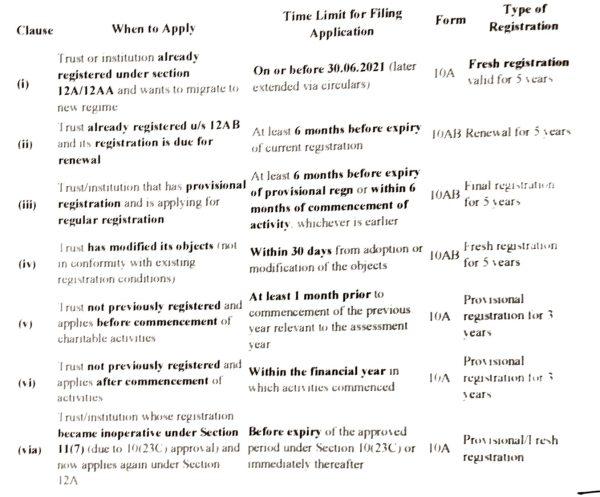
5. It is observed here that after the amendment to the relevant provisions w.e.f. 01.04.2021, there were many misunderstandings and confusions about the correct interpretation of the same, not only among the assessees/Income Tax professionals, but also with the Income Tax Authorities. Even the CBDT had to issue circulars and clarifications regarding correct interpretation of the relevant provisions from time to time. Even the time/limitation for making the applications has also been extended from time to time taking note of such confusions in properly understanding relevant provisions. The Co-ordinate Benches of the Tribunal have held time and again that due to the complex provisions and even there being certain discrepancies in prescribed forms for issuing certificates, the assessees should not be punished for any mistake in mentioning the relevant clause in the application form. In the case in hand, the entire facts were before the Ld. CIT(E) and he was very much aware that the case of the assessee was otherwise eligible for granting final/regular registration, however, he found himself helpless only because the assessee had not mentioned correct clause. It has been held time and again that the litigants should not be punished for their bona fide mistakes.
6. This issue of wrong mentioning of the provisions for registration is no more res integra since various decisions passed by the Co-ordinate Benches, namely, Aatman Foundation vs. CIT(E) 174 taxmann.com 1109 (Ahmedabad-Trib.), Gandhinagar Ayyapa Pooja Samiti vs. CIT(E) 174 taxmann.com 901 (Ahmedabad-Trib.) and Rotary Charity Trust vs. CIT(E) 170 taxmann.com 797 (Mumbai-Trib.) held that wrong quoting of the clause in the Application for registration of a trust is not fatal and set aside the rejection order to the file of CIT(E) to Shri Aadi Sristhi Manglam Samiti consider under the registration under correct provision by accepting in fresh Form 10AB and pass order in accordance with the provisions of law.
7. Following the above decisions, we are of the considered view that there is merit in the grounds raised by the assessee-trust which had selected wrong clause inadvertently while filing Form No. 10AB. Therefore, we deem it fit to set aside the impugned orders and remit the issue back to the file of Ld.CIT(E) with a direction to consider the rectified application of the assessee under clause (iii) of section 12A(1)(ac) of the Act and by giving opportunity of hearing to the assessee-trust and grant provisional/regular registration well within the provisions of the law.
8. In the result, the appeals filed by the assessee are allowed for statistical purposes.
Order pronounced in the open court on 16-11-2026



