
Deepak Seth Vs ITO (ITAT Kolkata)
ITAT Quashes Reassessment for Premature Faceless Proceedings and Failure to Follow New Reopening Procedure
Introduction
The Income Tax Appellate Tribunal, Kolkata Bench, quashed the reassessment framed against Deepak Seth on two legal grounds. First, it held that the National Faceless Assessment Centre had framed the reassessment before the notification making the relevant faceless reassessment scheme applicable. Second, it found that the Assessing Officer had continued proceedings under the old reassessment regime without following the mandatory procedure applicable from 1 April 2021.
The dispute involved assessed income of ₹2,18,81,152 against returned income of ₹3,36,580. Allowing the assessee’s appeal, the Tribunal quashed both the reopening notice and the consequential assessment.
Facts of the Case
The assessee had not filed an original return of income for Assessment Year 2013-14. The Department reopened his case under Section 147 based on information concerning cash deposits in bank accounts maintained with HDFC Bank and ICICI Bank Limited.
The information also included credit card payments of ₹2,01,646, brokerage income of ₹3,77,477 on which tax had been deducted under Section 194H, and term deposits of ₹7,20,000.
A notice under Section 148 bore the date 31 March 2021. In response, the assessee filed a return on 9 May 2021, declaring total income of ₹3,36,580.
Subsequent notices under Sections 143(2) and 142(1), together with a questionnaire, were not complied with. The assessment was consequently completed on 21 March 2022 under Section 147 read with Section 144, with the order also referring to Section 144B, determining total income at ₹2,18,81,152.
The CIT(A), National Faceless Appeal Centre, dismissed the assessee’s appeal by an order dated 15 October 2025.
Delay in Filing Appeal Condoned
The appeal before the Tribunal was delayed by 154 days. The assessee’s representative explained that the delay arose from bona fide and genuine reasons.
The Departmental Representative did not object to condonation. After considering the explanation and material available on record, the Tribunal accepted the reasons, condoned the delay and proceeded to adjudicate the appeal.
At the hearing, the assessee pressed grounds 4 and 5, both challenging the validity of the reassessment proceedings.
Faceless Reassessment Before Scheme Notification
Under ground 4, the assessee challenged the jurisdiction of the National Faceless Assessment Centre to conduct the reassessment before the relevant notification.
The Tribunal noted that Section 151A, dealing with faceless assessment of income escaping assessment, had been introduced with effect from 1 November 2020. However, the relevant scheme was notified on 29 March 2022 through Notification No. 18/2022.
The reassessment under challenge had already been completed on 21 March 2022.
On this basis, the Tribunal held that the issuance of notices and subsequent framing of the assessment by the National Faceless Assessment Centre were without jurisdiction.
It relied on the coordinate Bench decision in MD Mahimud SK Vs. ITO, ITA Nos. 2230 and 2229/KOL/2024, dated 4 March 2025. That decision had similarly held that faceless reassessment proceedings undertaken before the notification could not be sustained.
Following the coordinate Bench ruling, the Tribunal quashed the assessment and allowed ground 4.
Notice Dated March 2021 but Served in April 2021
Ground 5 challenged the validity of the Section 148 notice. The assessee pointed out that although the notice was dated 31 March 2021, it was digitally signed on 16 April 2021, after the new reassessment regime came into force.
In its findings, the Tribunal recorded that the notice dated 31 March 2021 was served on 16 April 2021. It examined the subsequent proceedings against the requirements of the new regime applicable from 1 April 2021.
The Bench found that the Assessing Officer had neither treated the notice as a show-cause notice nor called upon the assessee to furnish details in that process. It further noted that no order under Section 148A(d) had been passed.
Instead, the assessment had been completed under the old regime.
The Tribunal held that the mandatory procedure under the new regime had not been followed. Consequently, the notice served on 16 April 2021 and the assessment framed pursuant to it were invalid and could not be sustained. Ground 5 was therefore also allowed.
Conclusion
The Tribunal allowed the assessee’s appeal and quashed the reassessment on both grounds advanced before it.
The ruling concerns the legal validity of the proceedings rather than the merits of the underlying transactions or additions. The Bench found defects both in the timing of the faceless reassessment and in compliance with the procedure governing the reopening notice.
Unlike a remand for further examination, the operative relief was annulment of the notice and consequential assessment.
Cases Discussed
- MD Mahimud SK Vs ITO (ITAT Kolkata); ITA Nos. 2230 and 2229/KOL/2024; 04/03/2025 — followed on the pre-notification faceless reassessment issue.
- Nabiul Industrial Metal Pvt. Ltd. Vs ITO (ITAT Kolkata); ITA No. 1328/KOL/2024; 15/10/2024; AY 2017-18 — discussed in the reproduced coordinate Bench ruling.
FULL TEXT OF THE ORIGINAL ORDER OF ITAT KOLKATA
This is an appeal preferred by the assessee against the order of the National Faceless Appeal Centre, Delhi [hereinafter referred to as the “Ld. CIT(A)”] dated 15.10.2025 for the AY 15.10.2025.
2.At the outset, we note that the appeal of the assessee is barred by limitation by 154 days. At the time of hearing the counsel of the assessee explained the reasons for delay in filing the appeal which is for bonafide and genuine reasons. The Ld. D.R did not raise any objection in condoning the delay. After hearing the rival contentions and perusing the materials available on record, we find that the delay is for bonafide and genuine reasons and, hence, we condone the delay and adjudicate the appeal in the following paras.
3. At the time of hearing, the assessee pressed down number 4 and 5 which are extracted below:
“4. For that the National Faceless Assessment Centre erred in having assumed Jurisdiction u/s 151A r.w.s 144B of the Act from 17.01.2022 when they were not empowered under any notification about the applicability of the faceless scheme for making assessment in faceless manner prior to 29.03.2022.
5. For that the Ld. CIT(Appeals) erred in upholding the validity of the notice dated 31.03.2021 issued u/s 148 of the Income Tax Act, 1961, despite the same being digitally signed on 16.04.2021, i.e., after the new regime u/s 147-151 came into force w.e.f. 01.04.2021”
4. The issue raised in ground number 4 which is against the assessment framed by the National Faceless Assessment Centre vide order dated 21-3-2022, which is prior to the notification issued by the competent authority and therefore order is without jurisdiction and same is prayed to be quashed.
5. The facts in brief are that the assessee did not file return of income for the impugned assessment year. The case of the assessee was re-opened u/s 147 of the Act. Thereafter, notice u/s 148 of the Act was issued on 31.03.2021 which was complied with by filing the return of income on 09.05.2021,declaring total income at ₹3,36,580/-.Accordingly, notices u/s 143(2) and 142(1) along with questionnaire were issued and served upon the assessee which was not complied with. Thus, view the facts of the case and also the materials available on record, the ld. AO assessed the total income at₹2,18,81,152/- u/s 147 read with section 144 of the Act vide order dated 21.03.2022.
6. In the appellate proceedings, the ld. CIT (A) dismissed the appeal of the assessee.
7. After hearing the rival contentions and perusing the materials available on record, we find that the section 151A of the Act deals with the faceless assessment of income escaping assessment and was brought on the statue book by Taxation and Other Law (Relaxation and Amendment of Certain Provisions) Act, 2020, with effect from 01.11.2020 which was notified on 29.03.2022 vide notification no.18/2022/F. No. 370142/16/2022-TPL(Part)]. Considering these facts, we are of the considered view that the issuance of notices and thereafter framing of assessment by the NFAC, dated 21.03.2022 were without jurisdiction as the Provisions of Section 151A of the Act were effective from 29.03.2022.Consequently, the assessment order passed by the AO cannot be sustained. The case of the assessee is squarely covered by the decision of the co-ordinate in case of MD Mahimud SK Vs. ITO in ITA no. 2230 & 2229/KOL/2024 vide order dated 04.03.2025, wherein the co-ordinate Bench has decided the issue by observing and holding as under: –
“11. We have perused the section of Section 151A of the Act, which deals with the faceless assessment of income escaping assessment and was amendment of certain provisions) Act, 2020, with effect from 01.11.2020 which was notified on 29.03.2022 vide notification no.18/2022/F. No. 370142/16/2022-TPL(Part)]. Therefore, the assessment proceedings were taken by the National Faceless Assessment Centre, Delhi by issuing notice u/s 142(1) dated 09.02.2022 and thereafter the assessment was framed accordingly after issuing show cause notice which in our opinion is without jurisdiction. The provisions of Section 151A of the Act were brought on the statute book with effect from 01.11.2020. However, the same were made effective and applicable with effect from 29.03.2022 vide notification no. when the CBDT notified the new scheme for assessment of income escaping assessment scheme, 2022. In our considered view the assessment framed is without jurisdiction and cannot be sustained. The case of the assessee find force from the decision of Nabiul Industrial Metal Pvt. Ltd., Paschim Medinipur VS. I.T.O., in ITA no. 1328/KOL/2024 for A.Y. 2017-18, the order dated 15.10.2024, wherein a similar issue has been decided in favor of the assessee. For the sake of ready reference, the notice issued u/s 142(1) dated 09.02.2022 and show cause notice dated 17.03.2022, are extracted below:-
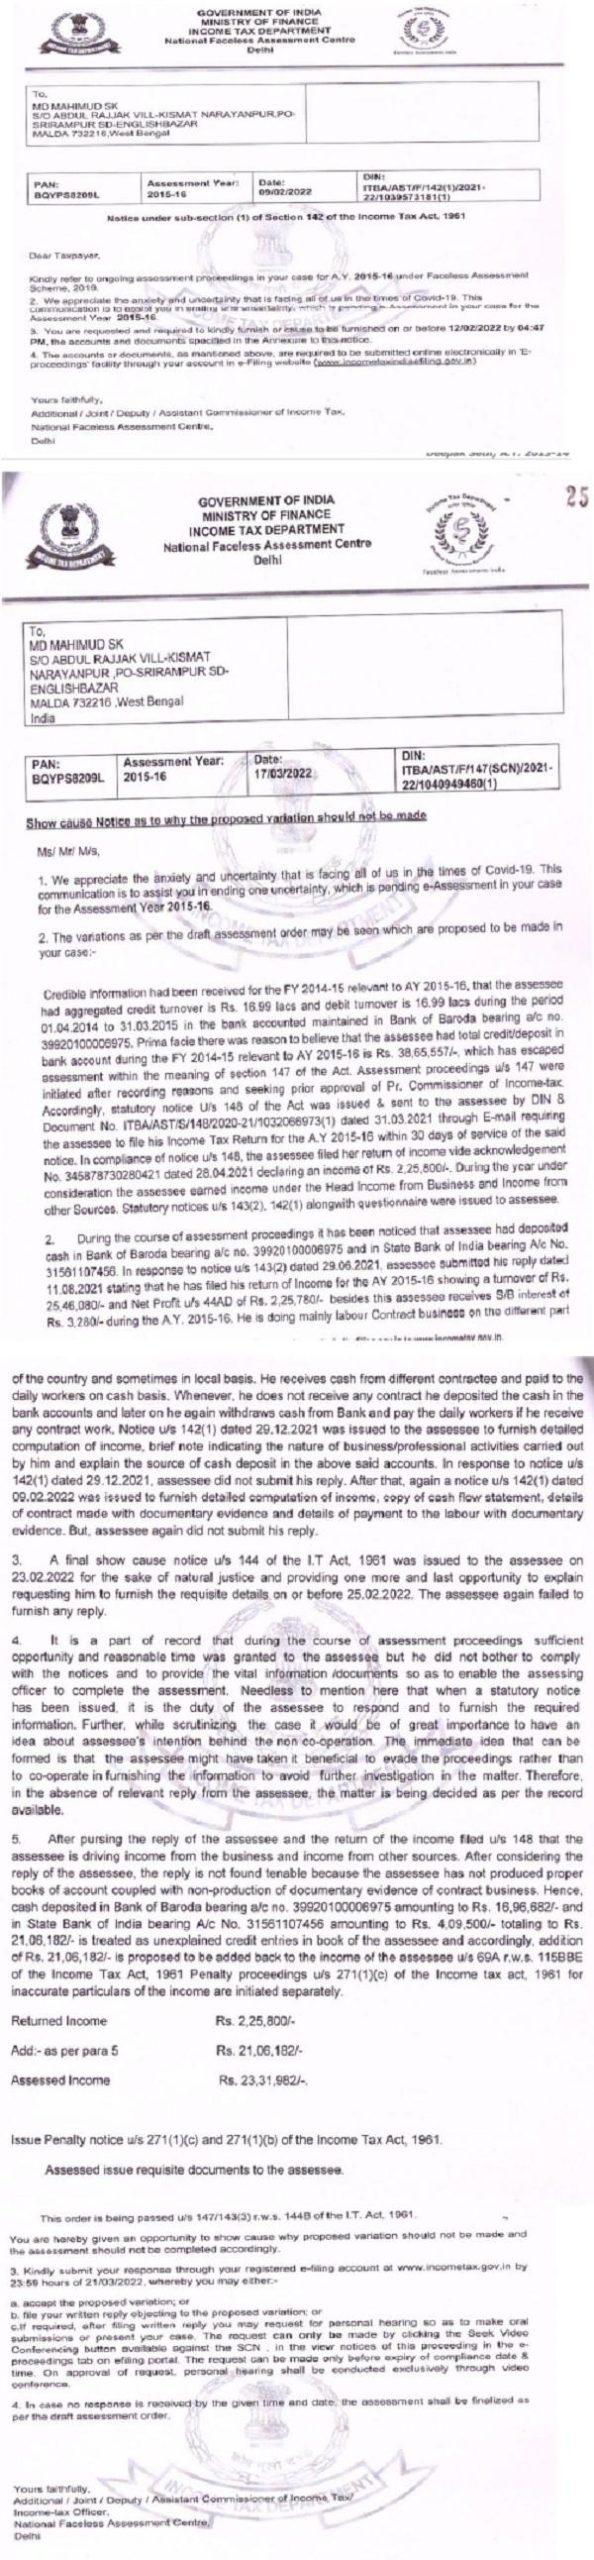
12. Considering the above facts and legal position, we are of the considered opinion that the order passed by the NFAC, Delhi is without jurisdiction and is hereby quashed. The appeal of the assessee is allowed.
13. The additional ground raised in ITA No. 2230/Kol/2024 A.Y.2017-18 is similar to one as decided by us in ITA No. 2229/Kol/2024 A.Y. 2015-16. Therefore, our decision would, mutatis mutandis, apply to this appeal as well. The appeal of the assessee is allowed.
14. In the result, the appeal of the assessee is allowed.”
8. In view of the above facts and the decision of the coordinate bench, we are inclined to quash the assessment framed by the ld. AO/ NFAC. The ground no. 4 of the appeal of the assessee is allowed.
9. The issue raised in ground number 5 is against the validity of notice issued under section 148 of the Act on 31st March 2021 which was a digital signed on 16-4-2021, after a new regime of assessment came into operation u/s 147 of the Act, which was effective from 1-4-2021.
10. The facts in brief are that the assessee did not file the original return of income for the impugned assessment year.Thereafter case of the assessee was reopened under section 147 read with section 148 of the Act for large cash deposits into the bank accounts with HDFC Bank and ICICI Bank Limited.It was also noted that assessee during the yearhas made credit card payments amounting to₹2,01,646/-a ndalso earned brokerage amounting to rupees ₹3,77,477/- on which TDS under section 194H was deducted.The AO also noted that besides the above transactions the assessee hasalso gone into making of term deposits of ₹7,20,000/ -.Accordingly, notice under section 148 of the Act was issuedon 31st March 2021 by ITO, ward 47(2), Kolkata, which was served on 16-4-2021.Consequently the assessment framed under section 147 read with section 144 read with section144B of the Act, vide order dated 21st March 2022 by making various additions.
11. The learned CIT(A) dismissed the appeal of the assessee reframing the assessment.
12. After hearing the rival contention and perusing the materials available on record, we find that with effect from 1-4-2021 new regime of assessment under section 147 to 151 of the Act has come into force. However, the AO has issued notice under section 148 of the Act, which was dated 31st but served on 16th April 2021.We also note that thereafter the AO neither did treat the said notice as show cause notice nor did he call upon the assessee to furnish the details. We also note that no order under section 148(A)(d) of the Act was passed and the assessment was framed under the old regime. In our considered view the assessment framed by the AO and the notice issued and served to the assessee on 16-4- 2021 as well as the assessment framed consequently are invalid and cannot be sustained as the AO has not followed the mandatory procedure under the new regime. Therefore, the notice as well as the assessment framed are hereby quashed. The ground no. 5 is allowed.
13. In the result, the appeal of the assessee is allowed.
Order pronounced on 26.10.2026.




