
Kanauj Kanti Chaudhuri Vs ITO (ITAT Guwahati)
Summary: ITAT Guwahati allowed a batch of 47 appeals involving BSNL employees and held that the assessees should not be denied the benefit of exemption under Section 10(10B) merely because their appeals were filed belatedly. In the lead appeal of Kanauj Kanti Chaudhuri for AY 2021-22, the assessee, originally employed with the Department of Telecommunications and subsequently absorbed in BSNL, had opted for the BSNL Voluntary Retirement Scheme, 2019.
The compensation was paid over two financial years. After subsequently becoming aware of the Chandigarh ITAT ruling in Harish Kumar Vs ITO, the assessee filed an appeal with a delay of 1,459 days seeking Section 10(10B) exemption. The CIT(A) declined to condone the delay and dismissed the appeal without examining its merits.
The Tribunal observed that similarly situated BSNL employees had already obtained relief from various Coordinate Benches and that the Department should not collect tax on income which is otherwise exempt. It particularly followed Jayeshkumar Tulsidas Sutaria Vs ITO, where a fresh Section 10(10B) claim concerning the same BSNL VRS-2019 scheme had been entertained. The Tribunal accordingly condoned the delay and allowed the appeal. Since the remaining appeals involved the same issue, subject only to differences in quantum, all 47 appeals were allowed in the same terms. The common order was pronounced on 30 June 2026.
Cases Discussed
- Jayeshkumar Tulsidas Sutaria Vs ITO, [2026] 183 taxmann.com 587 (ITAT Ahmedabad), ITA Nos. 2387 & 2388/Ahd/2025, order dated 17.02.2026 — Followed by the Tribunal on materially similar facts; the Ahmedabad Bench condoned the delay and entertained the BSNL VRS-2019 exemption claim under Section 10(10B) notwithstanding that it had not been claimed in the original return.
- Renuka Narasimha Prabhu Vs ITO, ITA No. 992/BANG/2026 (ITAT Bangalore) — Cited by the assessee as part of the series of Coordinate Bench decisions concerning Section 10(10B) exemption for compensation received under BSNL VRS-2019.
- Shri Sekar Gnanaprakasam Vs DCIT, ITA Nos. 1608 & 1609/CHNY/2026 (ITAT Chennai) — Cited amongst the decisions supporting the assessee’s claim relating to BSNL VRS compensation.
- Shivnandan Narendra Sanvordekar Vs ITO, ITA Nos. 141 & 142/PAN/2026 (ITAT Panaji) — Cited as another Coordinate Bench decision concerning the same BSNL VRS-2019 exemption controversy.
- Ramesh Bhimshankar Budwatrao Vs ITO, ITA No. 1890/PUN/2026 (ITAT Pune) — Cited by the assessee in the line of Tribunal decisions granting relief in BSNL VRS cases.
- Bajirao Shankar Jagdale Vs ITO, [2026] 185 taxmann.com 451 (ITAT Mumbai) — Cited in support of the proposition that BSNL VRS-2019 compensation is in the nature of retrenchment compensation eligible for Section 10(10B) relief.
- Prathibha Jgadish Unawane Vs ITO, ITA Nos. 1117 & 1118/PUN/2026 (ITAT Pune) — Relied upon among the decisions involving the same BSNL VRS-2019 controversy.
- Sameer Yadram Sharma Vs ITO, ITA Nos. 864 & 865/PUN/2026 (ITAT Pune) — Cited by the assessee as a Coordinate Bench ruling on the same issue.
- Rajendra Himmatrao Patil Vs ITO, ITA Nos. 302 & 303/PUN/2026 (ITAT Pune) — Cited as part of the consistent line of Pune Bench decisions granting Section 10(10B) relief to BSNL VRS employees.
- Meghmala Sudhir Pathak Vs ITO, ITA Nos. 290 & 293/PUN/2026 (ITAT Pune) — Cited on the identical BSNL VRS-2019 issue.
- Shraddha Pralhad Arote Vs ITO, ITA Nos. 262 & 261/PUN/2026 (ITAT Pune) — Relied upon as a Coordinate Bench decision concerning Section 10(10B) exemption for BSNL VRS-2019 compensation.
- Suman Nandlal Raval Vs ITO, ITA Nos. 2389 & 2390/Ahd/2025 (ITAT Ahmedabad) — Cited by the assessee among the Coordinate Bench decisions supporting the BSNL VRS exemption claim.
- Harish Kumar Vs ITO, [2025] 175 taxmann.com 379 (ITAT Chandigarh), ITA No. 42/CHD/2025, order dated 30.05.2025 — The principal precedent which prompted the assessee to make the delayed claim; the Chandigarh Bench held compensation under BSNL VRS-2019 eligible for exemption under Section 10(10B).
- Delhi Development Authority Vs Others, 2024 INSC 456 (Supreme Court) — Relied upon by the Revenue, but distinguished by the Guwahati Bench as inapplicable in the circumstances, particularly considering parity among employees of the same organisation.
- Jute Corporation of India Ltd. Vs CIT (1991) 57 ELT 176 (SC) — Referred to in the reproduced Jayeshkumar Tulsidas Sutaria decision for the appellate authority’s power to entertain a fresh claim even where it was not made in the return.
- NTPC Ltd. Vs CIT (1998) 229 ITR 383 (SC) — Referred to in the reproduced Coordinate Bench order on the power of appellate authorities to entertain a fresh legal claim.
- CIT Vs Pruthvi Brokers & Shareholders Pvt. Ltd. (Bombay High Court) — Referred to for the proposition that a fresh claim may be considered by an appellate authority even if no revised return was filed.
FULL TEXT OF THE ORDER OF ITAT GUWAHATI
All these 47 appeals filed by the different assessee against the orders passed u/s 250 of the Income Tax Act, 1961 by the Ld. Addl./Joint Commissioner of Income Tax (Appeals) (hereinafter referred to as “the Act”). On going through the grounds of all the assessees, we noticed that the issues raised by the different assessees are common in nature except the quantum involved in all the appeals and heard together. Therefore, we are passing a common order for all the appeals. For the sake of convenience, we are first taking up appeal ITA No. 258/GTY/2026 for AY 2021-22 by the Ld. Addl./Joint Commissioner of Income Tax (Appeals), Thiruvanantpuram [hereinafter referred to as “the Ld. CIT(A)] dated 12.02.2026, DIN & order No. ITBA/APL/S/250/2025- 26/1085940331(1) on the following grounds of appeal:
“1. For that the learned CIT (Appeals) has failed to appreciate the facts and refused to condone the delay and passed the order without getting into the facts of the case, which is not in concurrence with the spirit of the law.
2. For that the learned CIT (Appeals) has failed to appreciate the facts of the present case and refused to take into cognizance the fresh evidence, leading to a denial of justice to the assessee, which is not sustainable in the eye of law.
3. For that the learned CIT (Appeals) has not applied his mind by not extending the benefit of the Board’s Circular No. 14 (XL-35) dated 11.04.1955 paras 3 and 6 of the said Circular and taking the benefit of the assessee’s ignorance passed the Order, which is not in concurrence with the spirit of law.
4. The assessee craves leave to add or alter any of the grounds before or at the time of the hearing.
2. Since we are taking to the ITA No. 258/GTY/2026 first as lead case and the decisions for Assessment Year 2021-22 will apply mutatis mutandis in others appeals except the quantum involved therein.
ITA No. 258/GTY/2026 (AY 2021-22)
3. Briefly stated the facts of the case are that the assessee is a Telecom Office Assistant under the Central Government DoT on 18.12.1989 based on the successful qualification on the basis of merit, filed his return of income on 19.12.2021 declaring at income of Rs. 38,00,810/-. The return was processed u/s 143(1) of the Act on 03.01.2022 accepting the return of income filed by the assessee. Upon formation of Bharat Sanchar Nigam Limited called as BSNL henceforth a PSU effective 1st Oct 2000 after carving out some of the functions of Department of Telecom DoT the employees and officers of DOT were faced to work in
BSNL on a deemed deputation basis. Thereafter the appellant was absorbed in BSNL as per Presidential Order of DOT dated 28th Nov 2005 with retrospective effect from 1st Oct 2000. In the meantime, dated 23rd Oct 2019 BSNL Voluntary Retirement Scheme VRS 2019was approved by the Union Cabinet. Following the Cabinet’s decision, the Scheme was officially notified on 4th Nov 2019 and was open for the employees from that date till 3rd Dec 2019. BSNL launched this Scheme to right size its workforce by offering a golden handshake package including Pension Ex Gratia and others before their normal superannuation. Ex gratia was given calculating 60 days salary being basic and DA for each completed years of service or remaining months’ salary whichever is less as per DPE guidelines. The appellant availed this Scheme and was compensated accordingly some of the payments in relation to Leave Encashment was from DoT. Like the appellant approximately 80000 or more employees and officers of BSNL were under this mass scale restructuring process of the Company to achieve significant workforce reduction with ongoing process for pay revision and benefit finalizations for the retirees. The entire payment was discharged in two phases one in the financial year 2019-20 and the balance in the financial year 2020- 21. The appellant received the compensations in the forms of Ex Gratia and Leave Encashment spread over two financial years and filed the Income Tax Returns of those years in the befitting manner within the due date. The assessee instituted the appeal before the Ld. CIT(A) on 01.02.2026 with a delay of 4 years equivalent to 1459 days with a condonation petition stating the reasons for delay in filing the appeal which is as under:
“The appeal is filed pursuant to landmark decision given by the ITAT Chandigarh Bench dated 30th May 2025 on the BSNL VRS 2019 case clarifying that amount received in the VRS 2019 Scheme by way of Ex Gratia shall be fully exempt from tax considering it as a compensation received due to loss of employment being capital receipt in nature and falling under section 10 sub sec 10B of the Income Tax Act 1961 and not under section 10 sub sec 10C of the same Act. Since this order came so lately in the mid of the year 2025, I am filing my appeal before the Commissioner Appeals praying for the relief by way of excess Tax Deducted at the time of my retirement considering it as VRS and not Retrenchment. This is a legitimate ground of praying through the appeals since a higher Bench ITAT Chandigarh gave its decision in the favour of the retiree and also decisions came in same matter in the Addl. JCIT Udaipur case dated 31st October 2025. Again Addl. JCIT Appeals 10 Mumbai in the case of Mr. Shyamal Kumar Dutta relating to the AY 2021-22 vide the DIN and Order No. ITBA. APL. S. 250. 2025-26. 1084844826 and in bracket 1, dated 16th January 2026 against the appeal made by the Appellant under section 143 subsection 1 which was 1497 days delay. The Appellant requested for the condonation of delay in filing the appeal showing the justifiable reasons in the application for such condonation. Hence, I am filing this appeal now praying for rightful condonation of delay. This has been granted by the Commissioner and the appeal was approved as well. Therefore, the delay in submission of the appeal is due to ignorance of the legal position and reliance on the government action which was in true sense illegitimate and unconstitutional. From the appellant’s side there is no question of any deliberate evasion of tax as the entire amount of tax either was deducted at source in higher value or paid by way of self- assessment or advance tax. This matter involves pure question of law and other appellate authorities have respectfully and rightfully accepted the appeal instituted by the appellant and condoned the same on legitimate judicial position considering the ground of natural justice. Hence I am filing this appeal now praying for rightful condonation of delay.”
4. The Ld. CIT(A) noted that the reasons given by the assessee is not reasonable cause and dismissed the appeal of the assessee for 0 not condoning the delay without going into merits of the case.
5. Aggrieved from the order of Ld. CIT(A), the assessee filed appeal before the ITAT. The Ld. Counsel has filed written synopsis supporting the case of the assessee and relying on the following judgments:
1. Harish Kumar V. Income-tax Officer – [2025] 175 taxmann.com 379 (Chandigarh – Trib.)
2. Jayeshkumar Tulsidas Sutaria V. Income-tax Officer – [2026] 183 taxmann.com 587 (Ahmedabad – Trib.)
3. Suman Nandlal Raval V. The Income Tax Officer, Ward 1, Gandhinagar. [ITA Nos.2389 & 2390/Ahd/2025]
5. Meghmala Sudhir Pathak V. Income-tax Officer Ward 2(1), Nashik – [290 and 293/PUN/2026] 20-21, 21-22
7. Bajirao Shankar Jagdale V. Income-tax Officer – [2026] 185 taxmann.com 451 (Mumbai – Trib.)
8. Prathibha Jgadish Unawane V. ITO, Ward 1 (1), Kolhapur – [1117 and 1118/PUN/2026] 20-21, 21-22
10. Renuka Narasimha Prabhu V. ITO Ward 1(1), Karnataka – [ITA 992/BANG/2026] 2020-21
13. Ramesh Bhimshankar Budwatrao V. ITO, Ward 2(1), Solapur – [1890/PUN/2026] 21-22
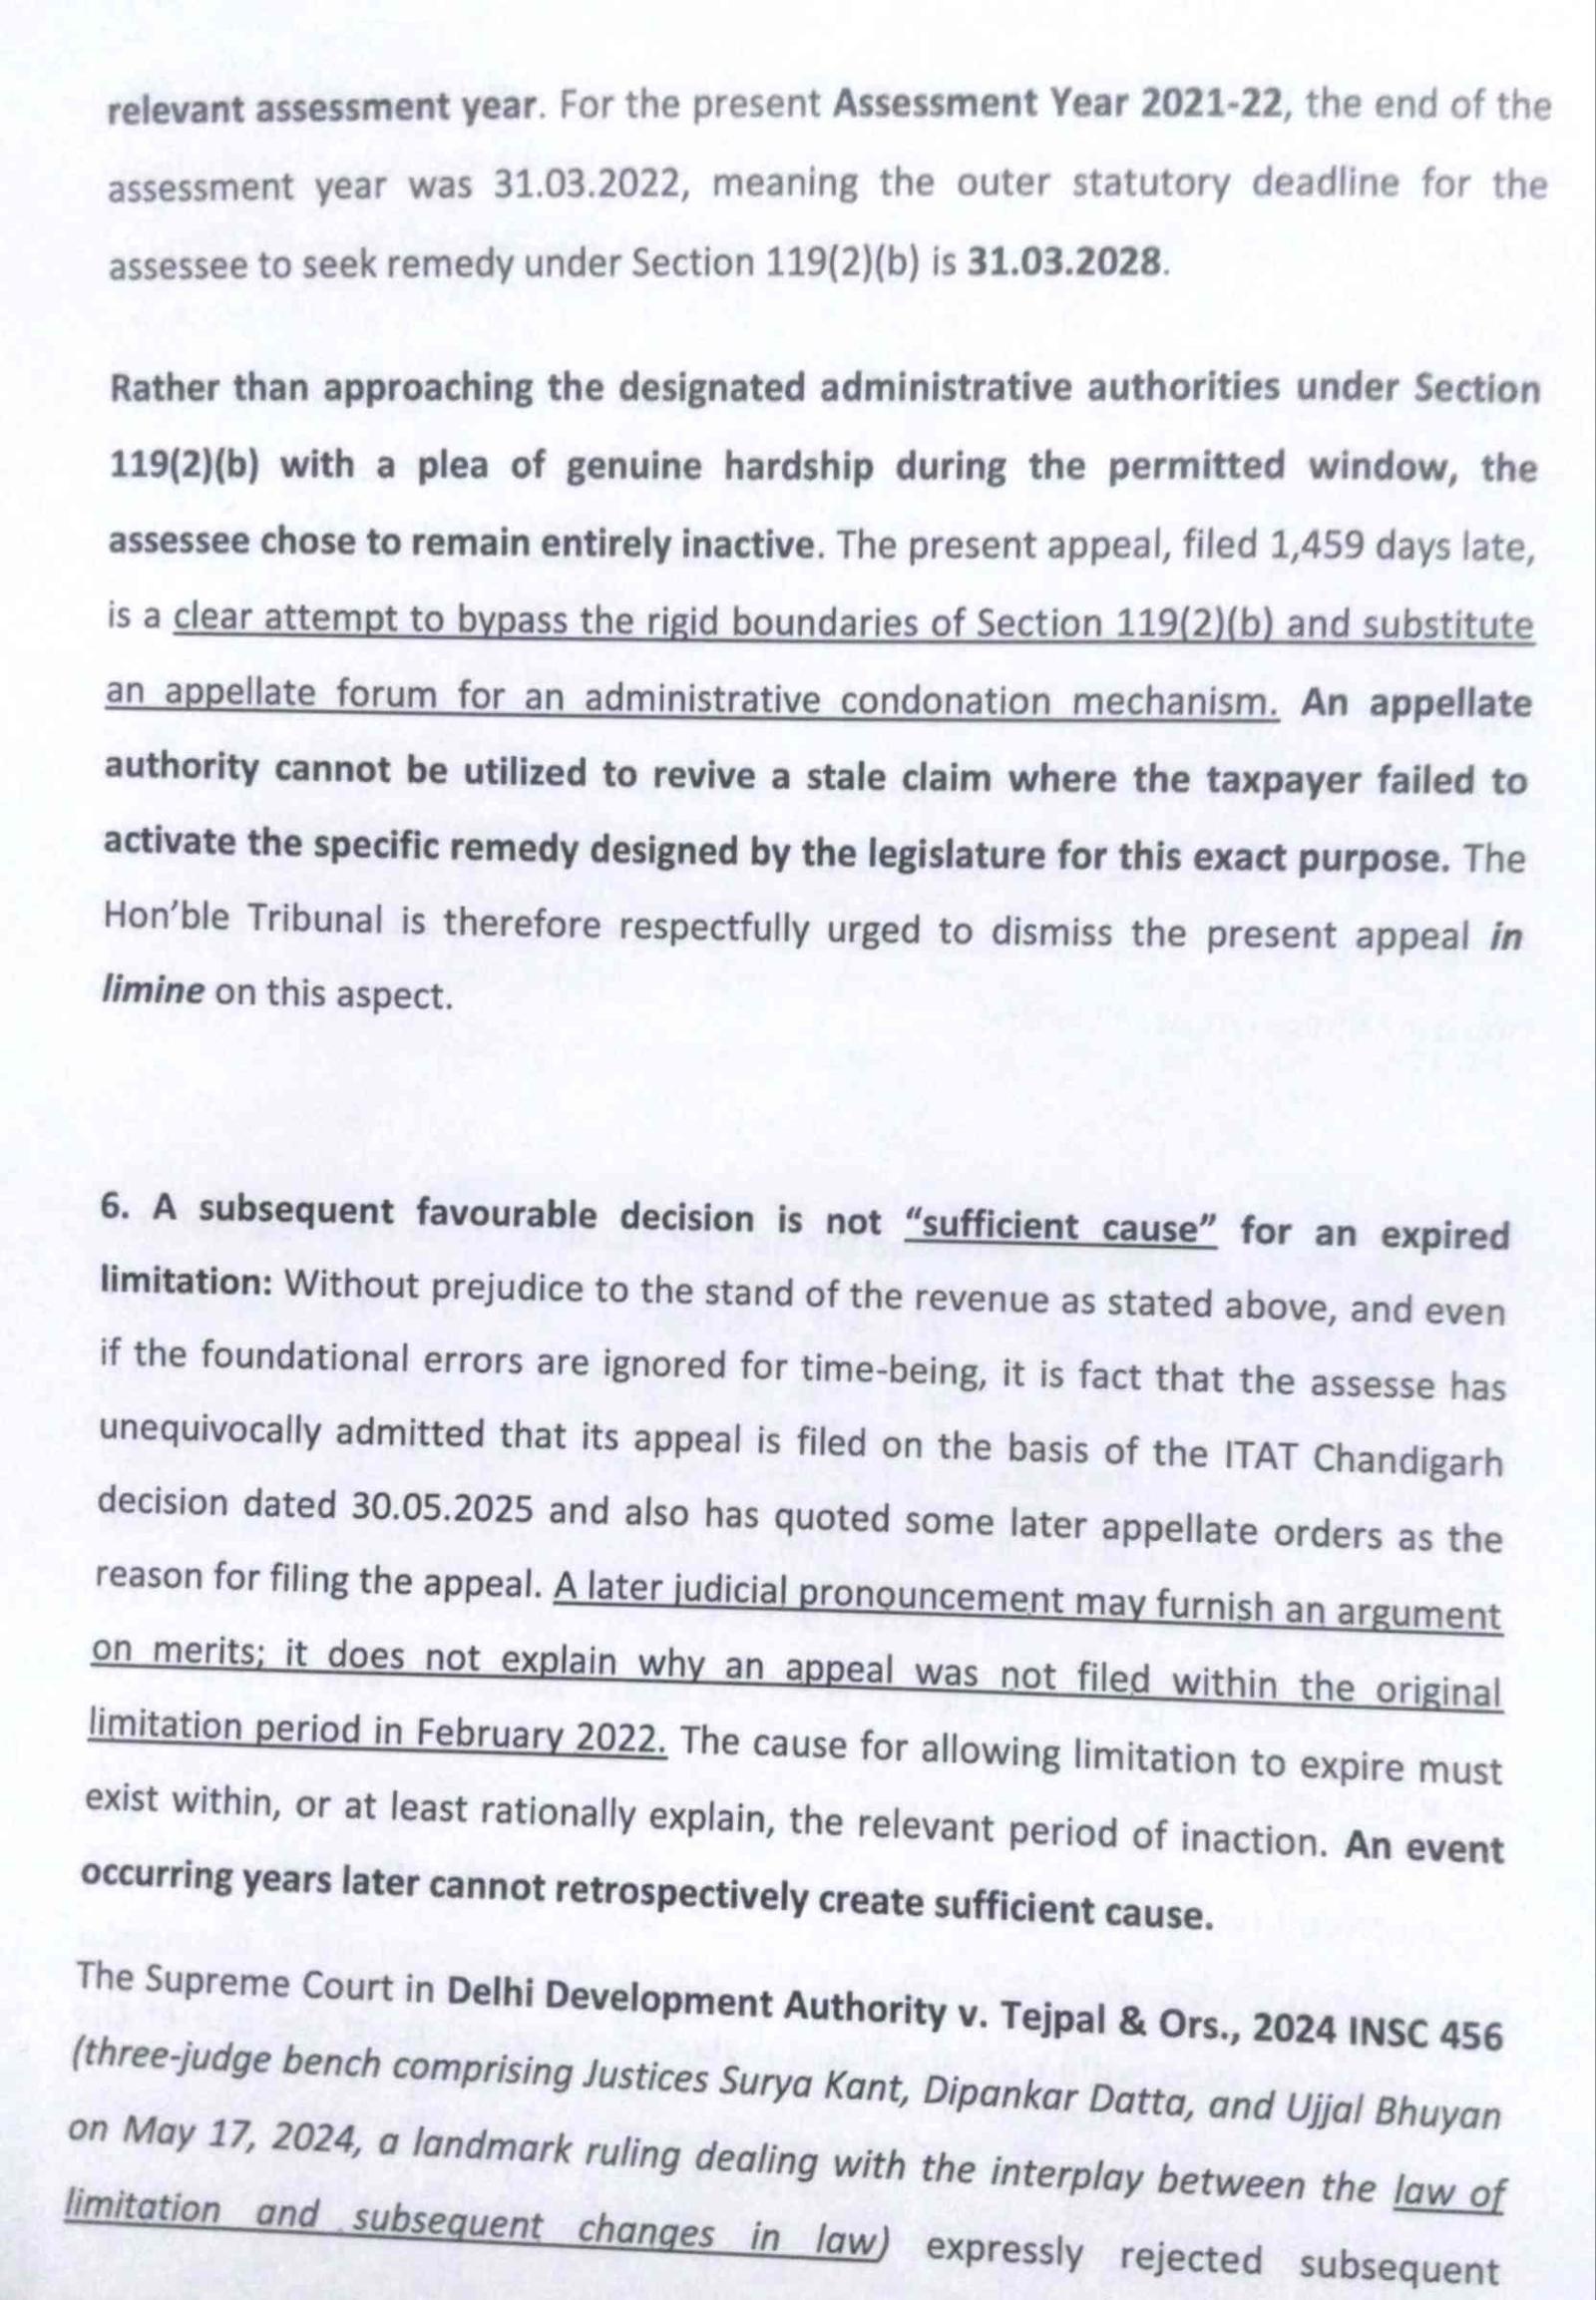
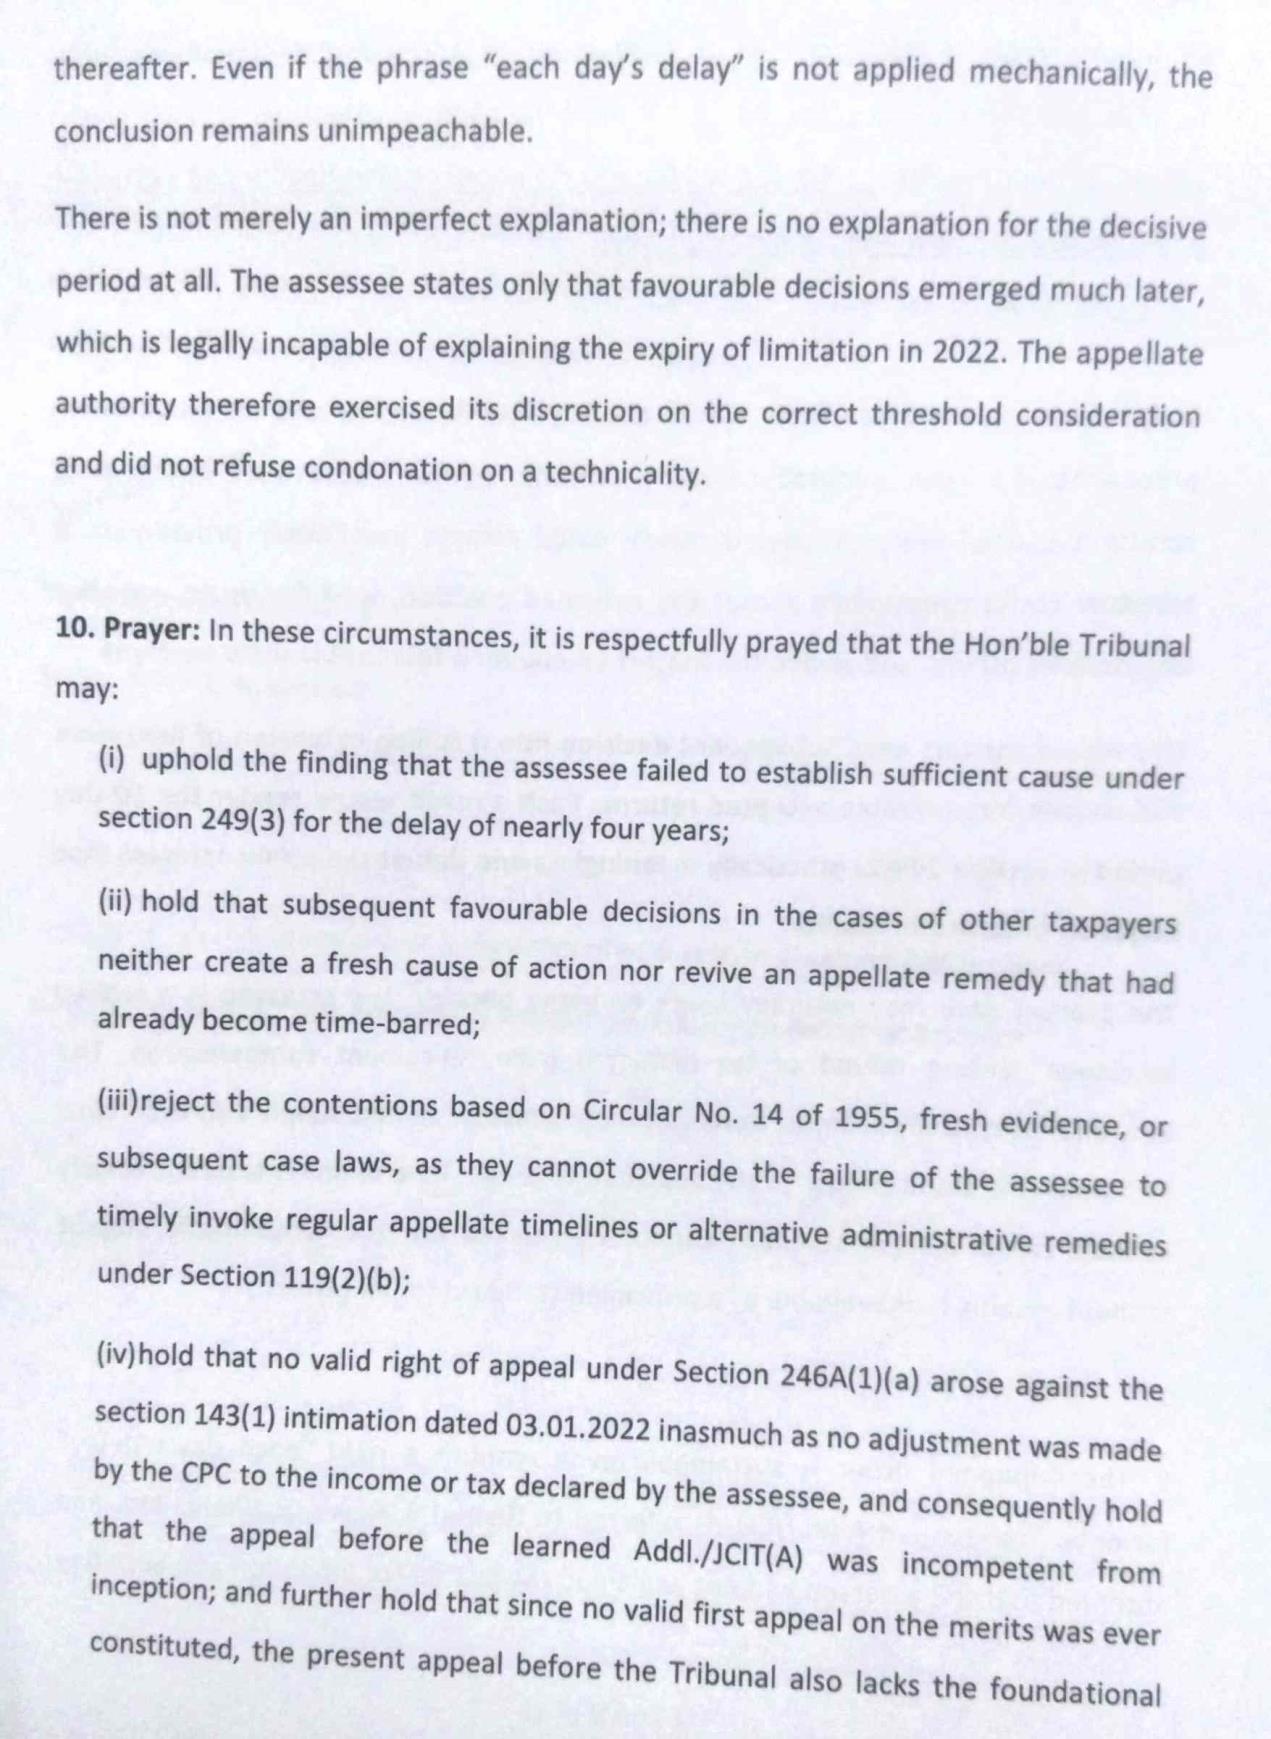
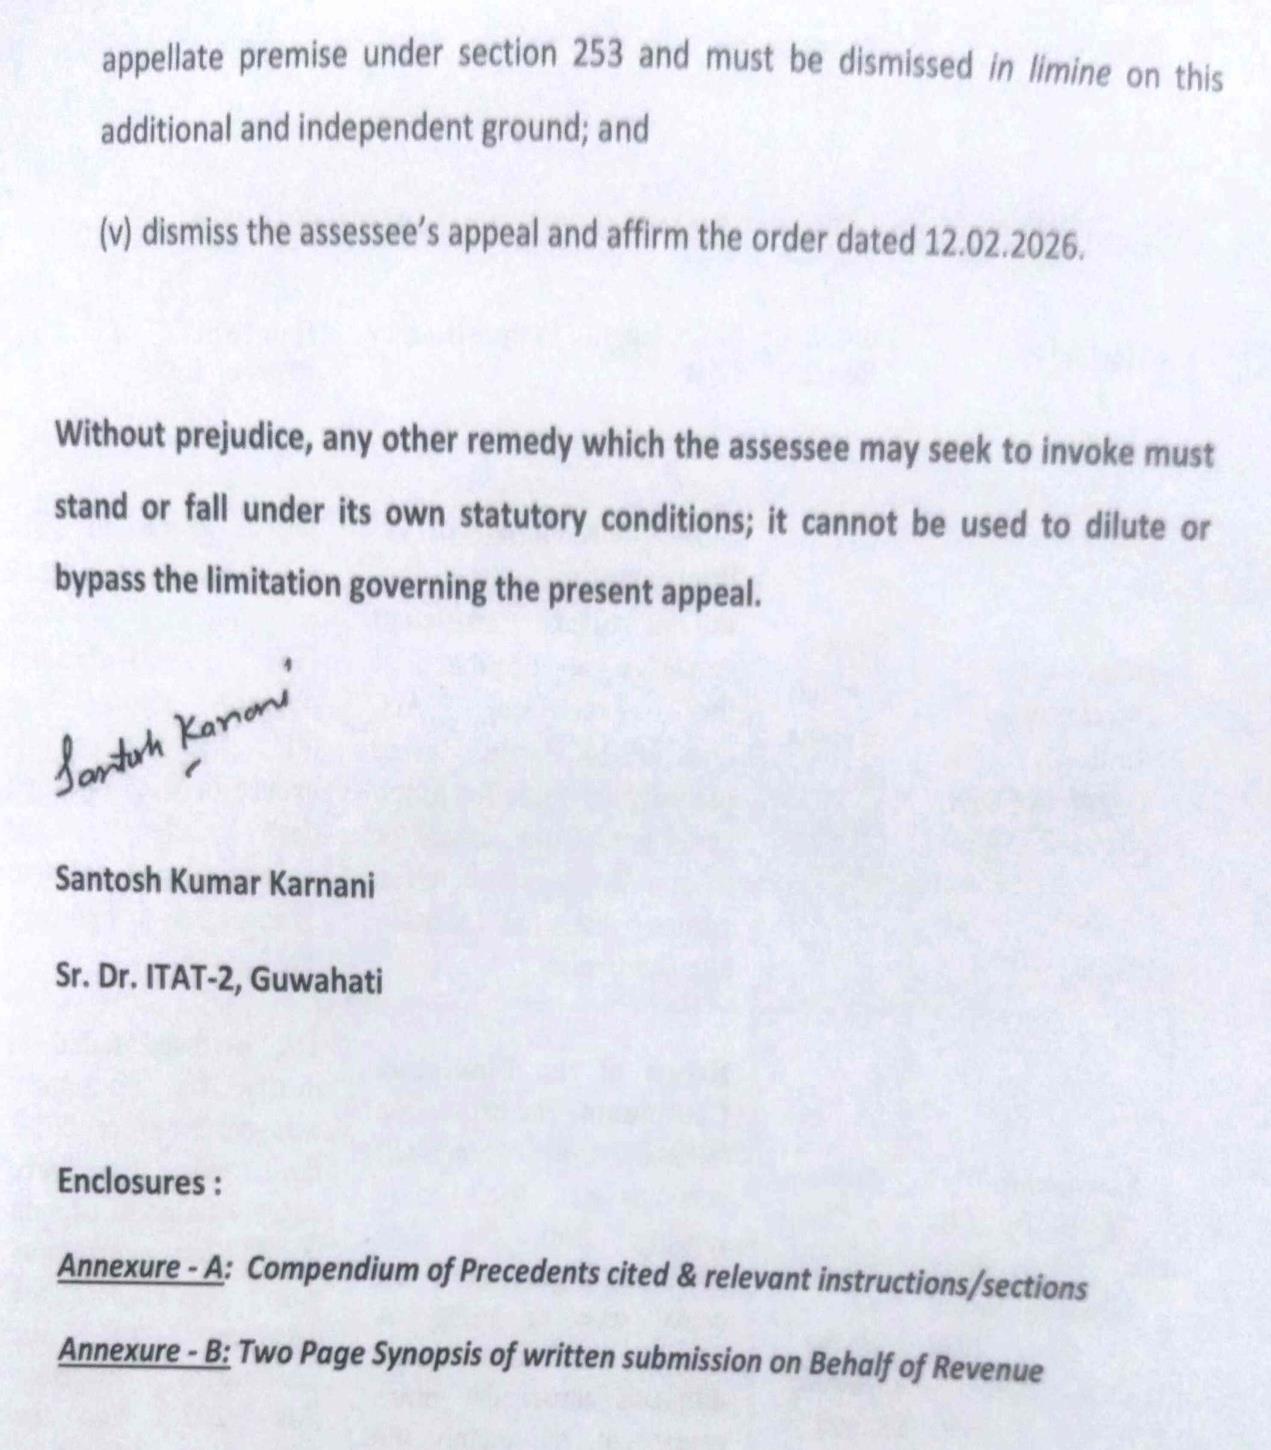
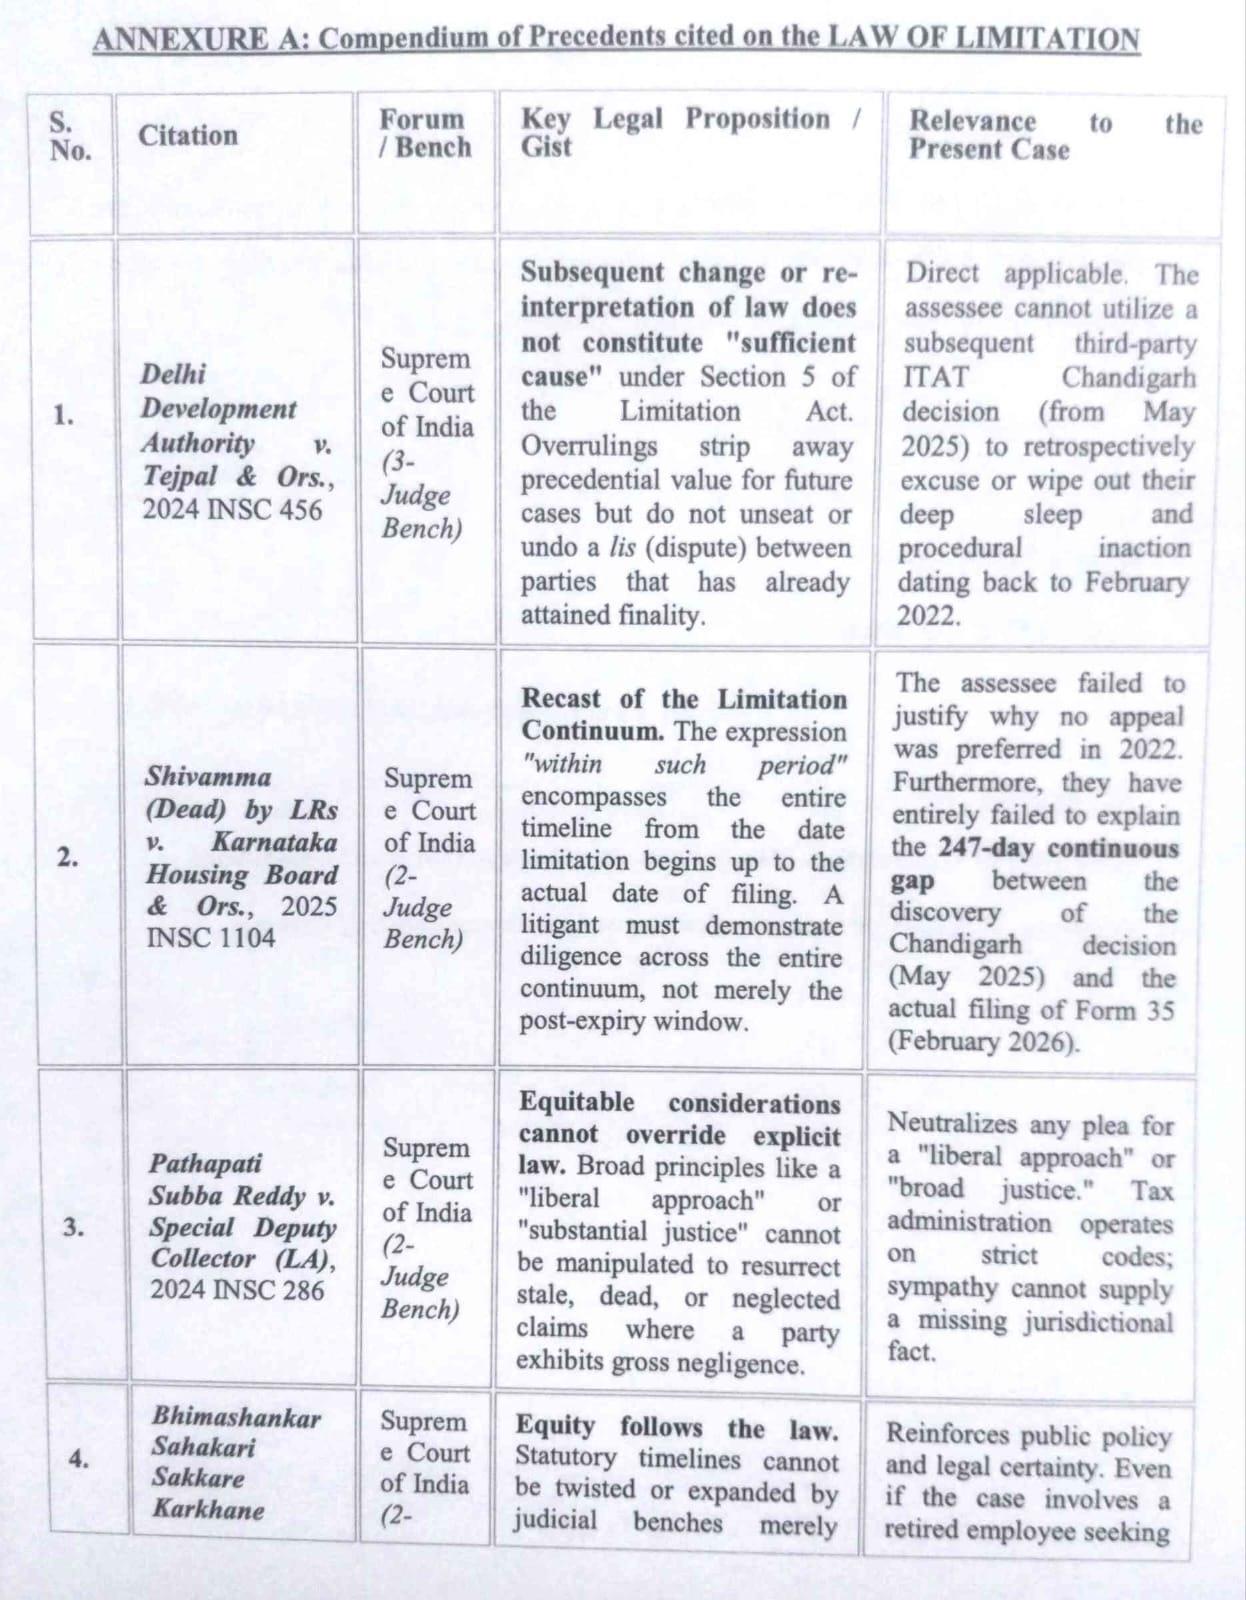
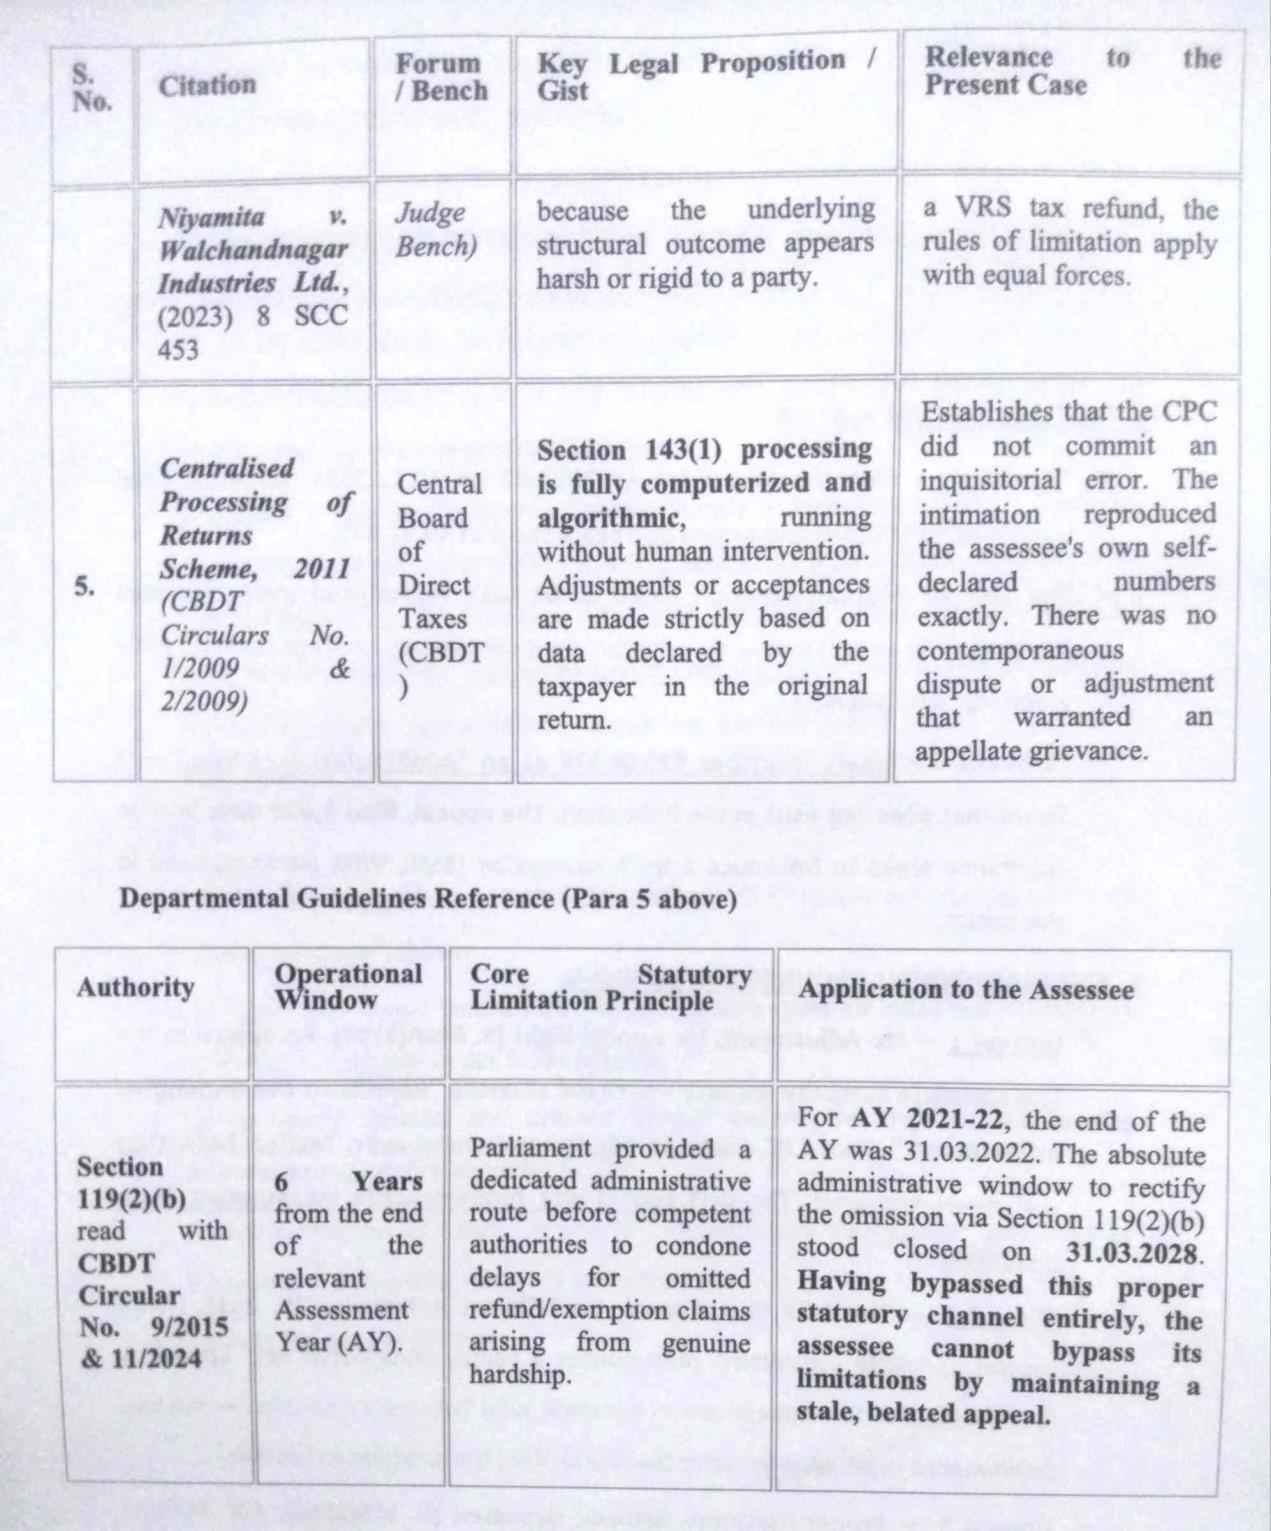
6. On the other hand, the Ld. DR has also filed his written synopsis which is as under:
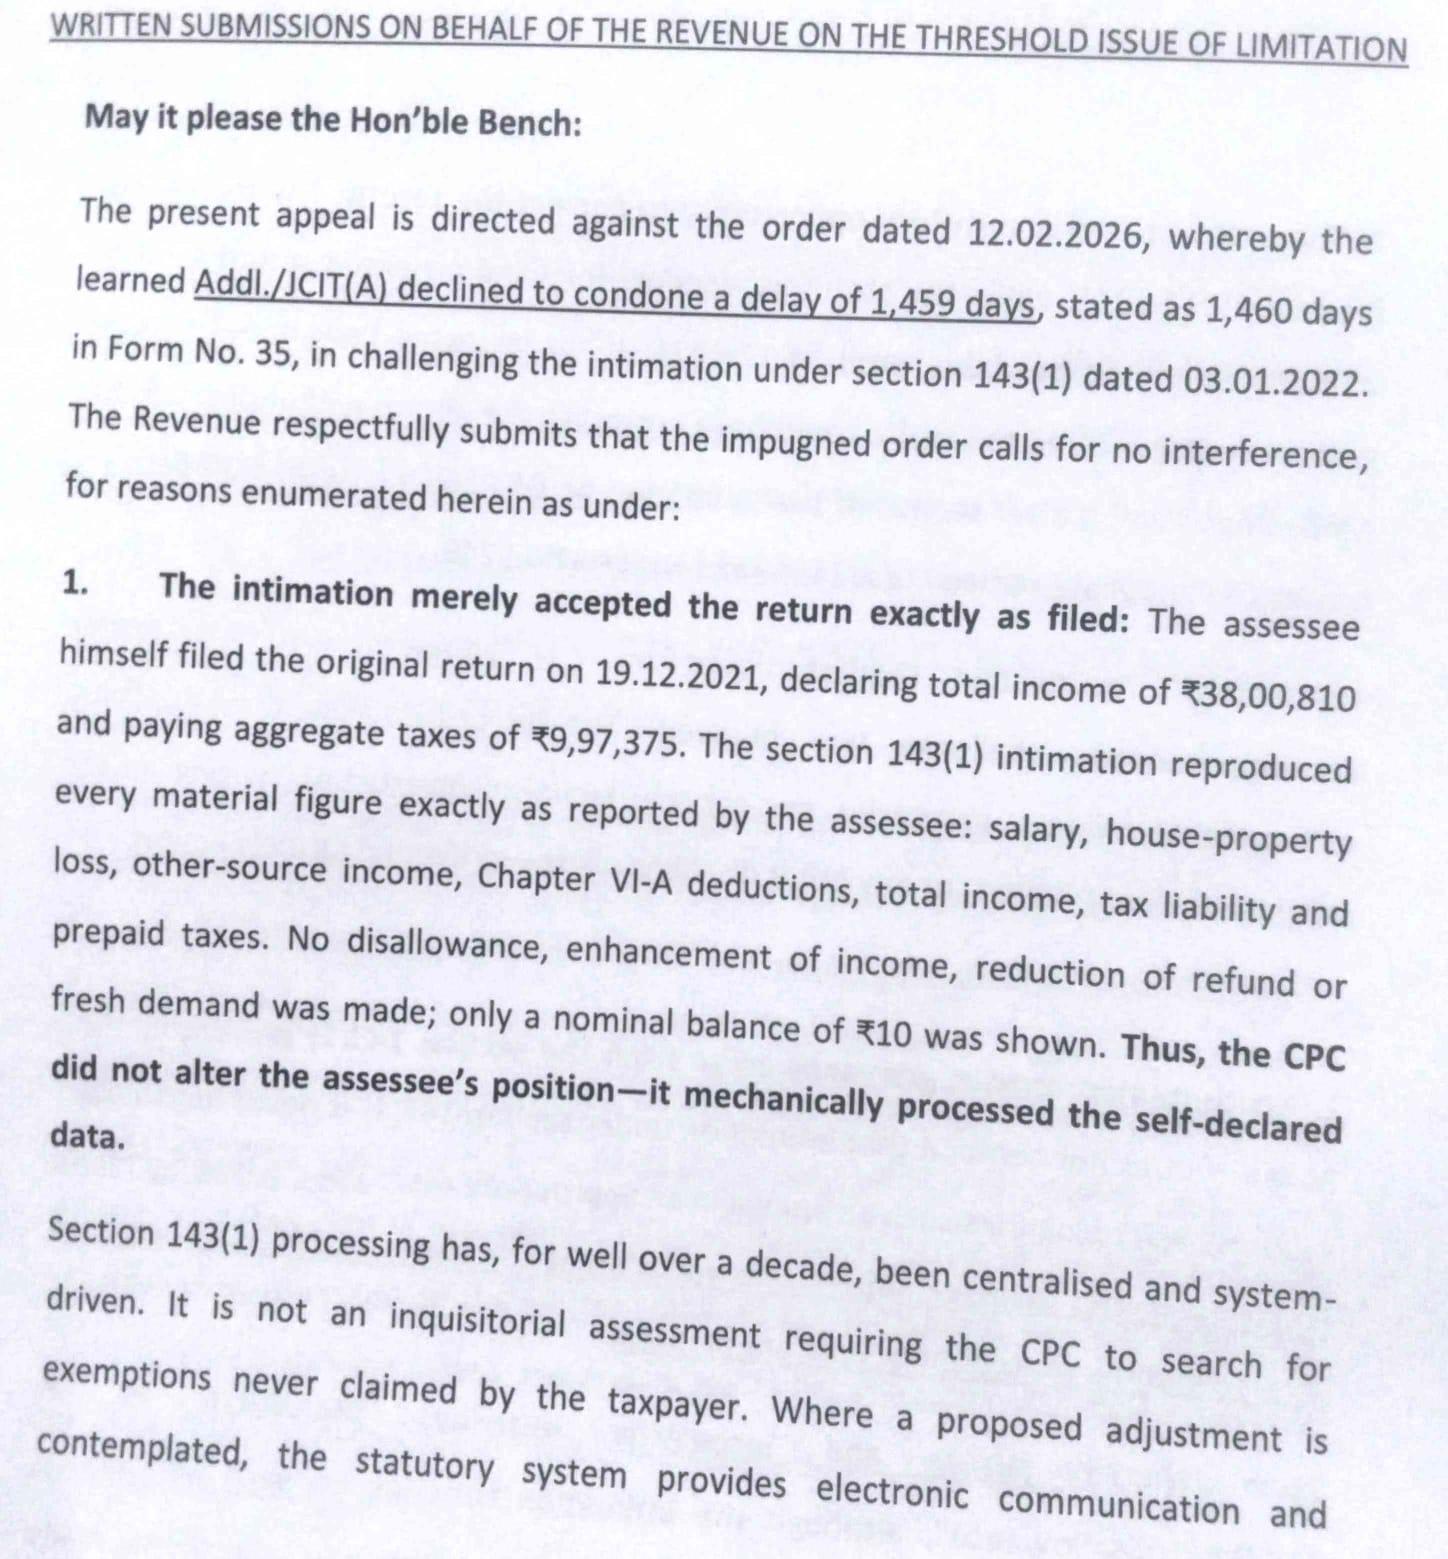
–
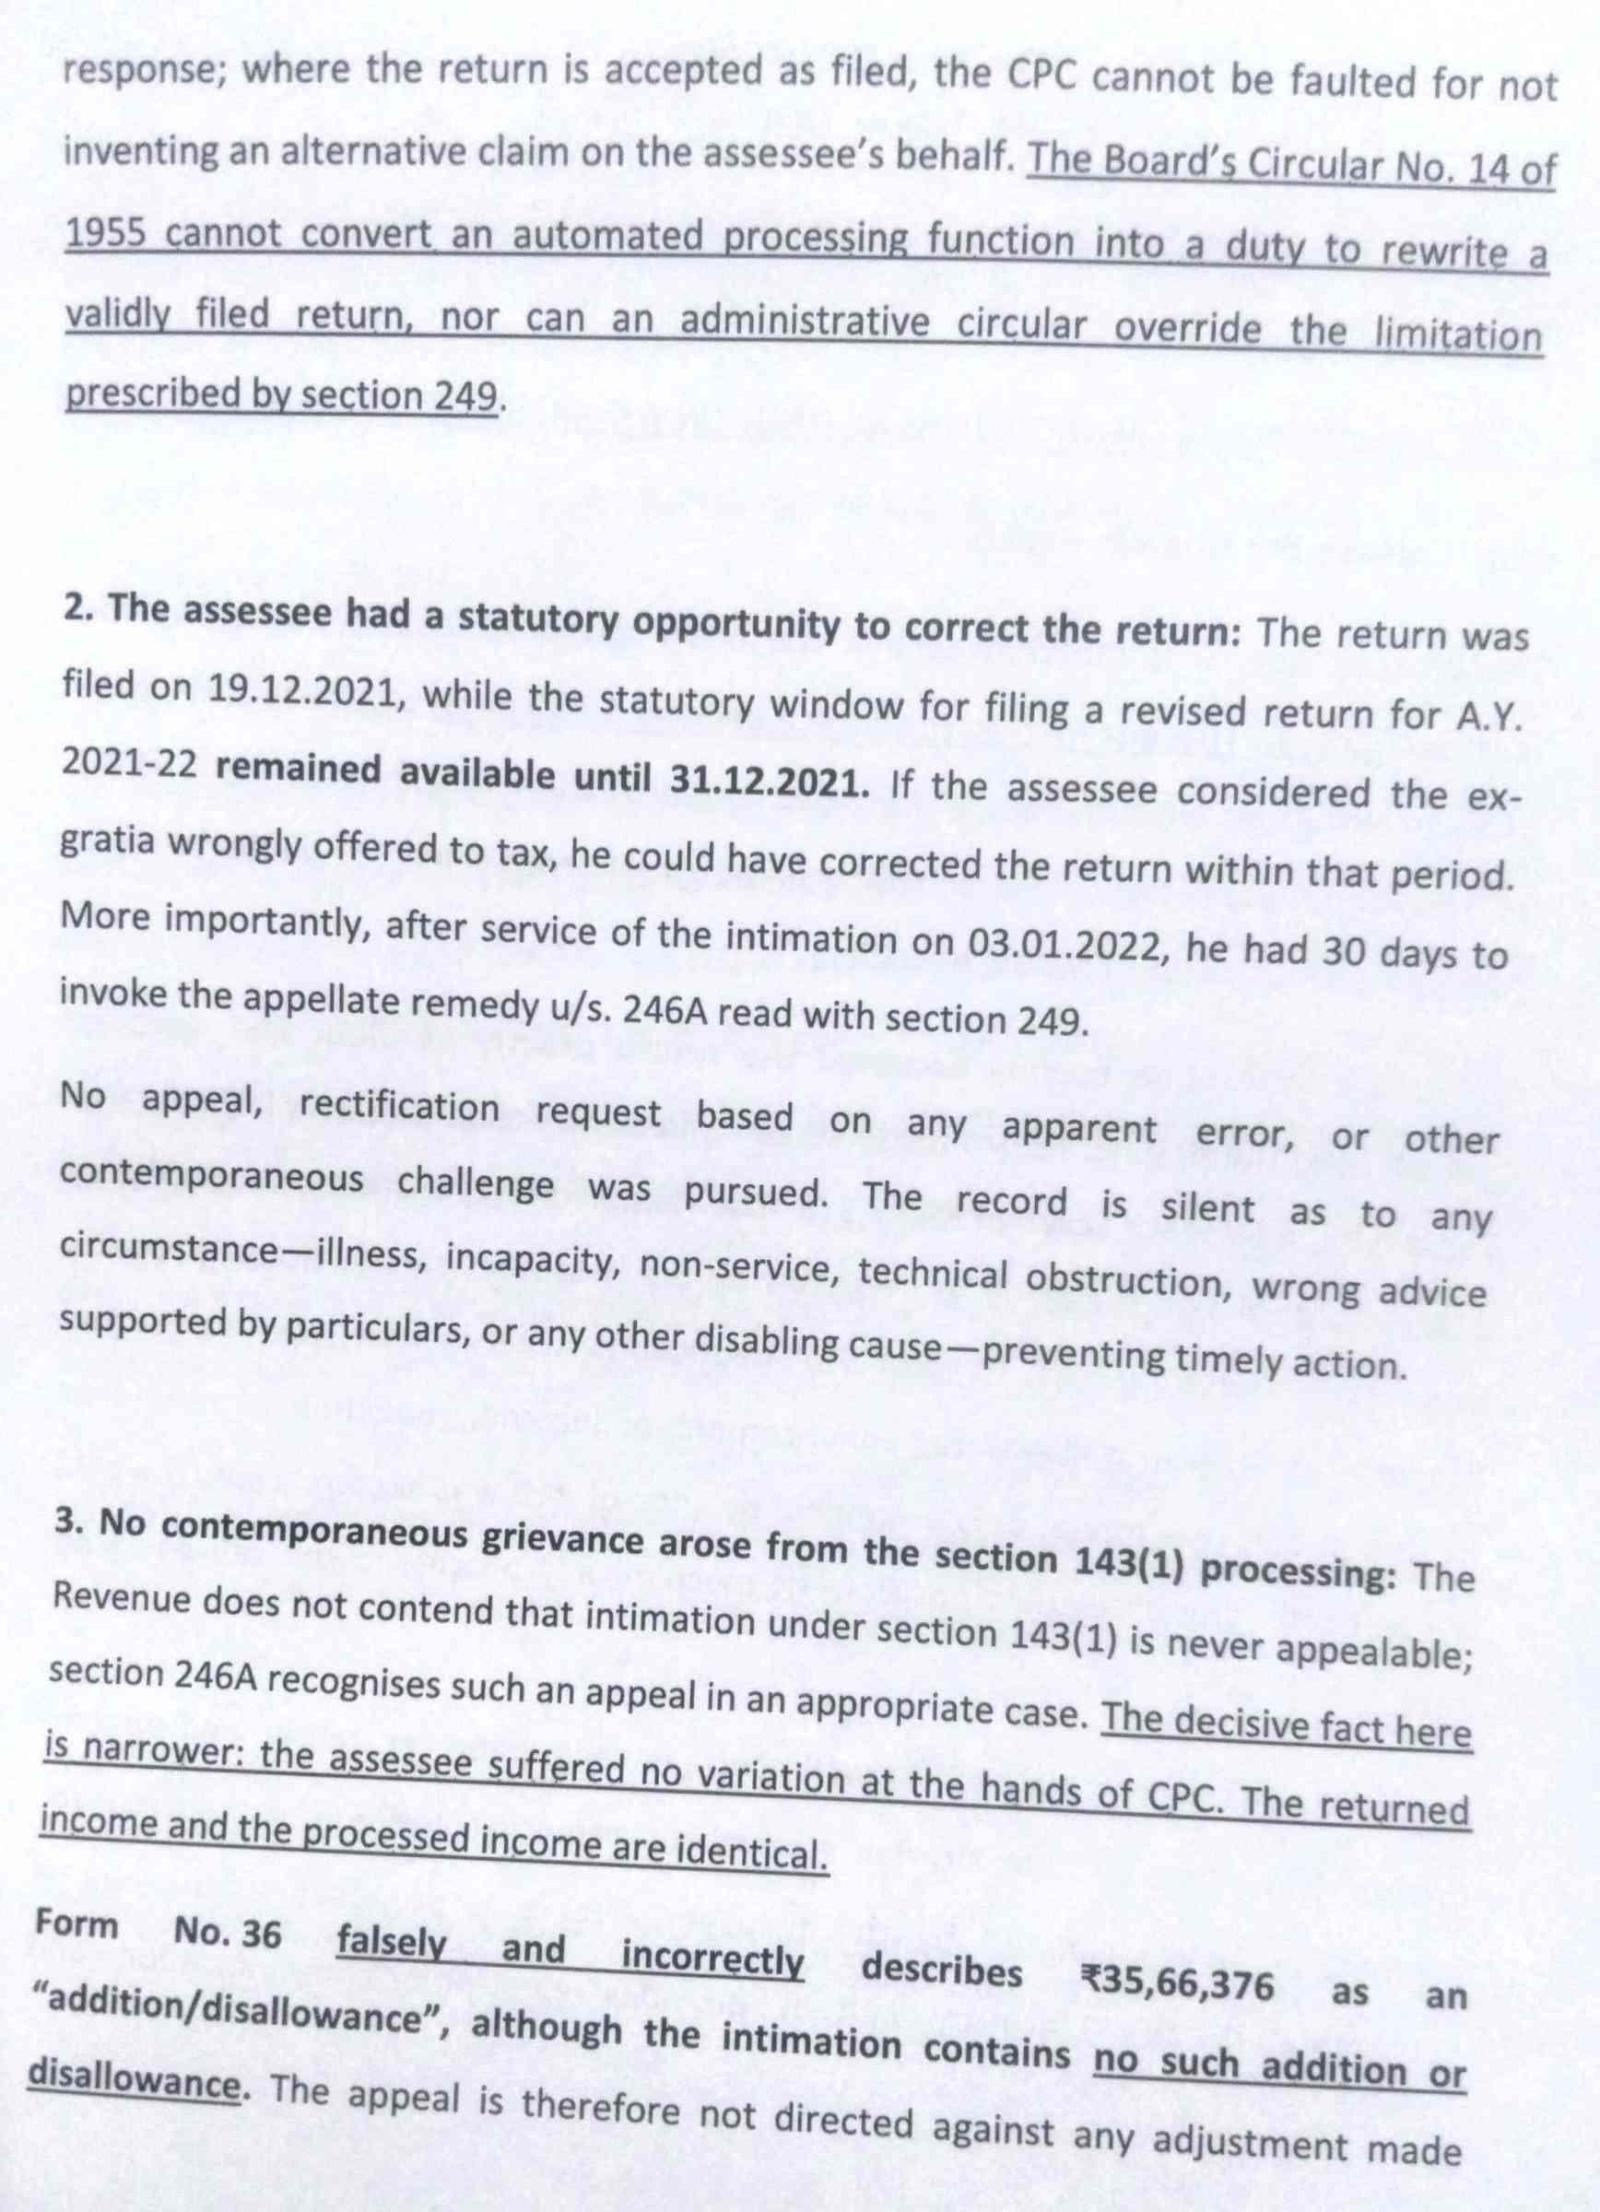
–
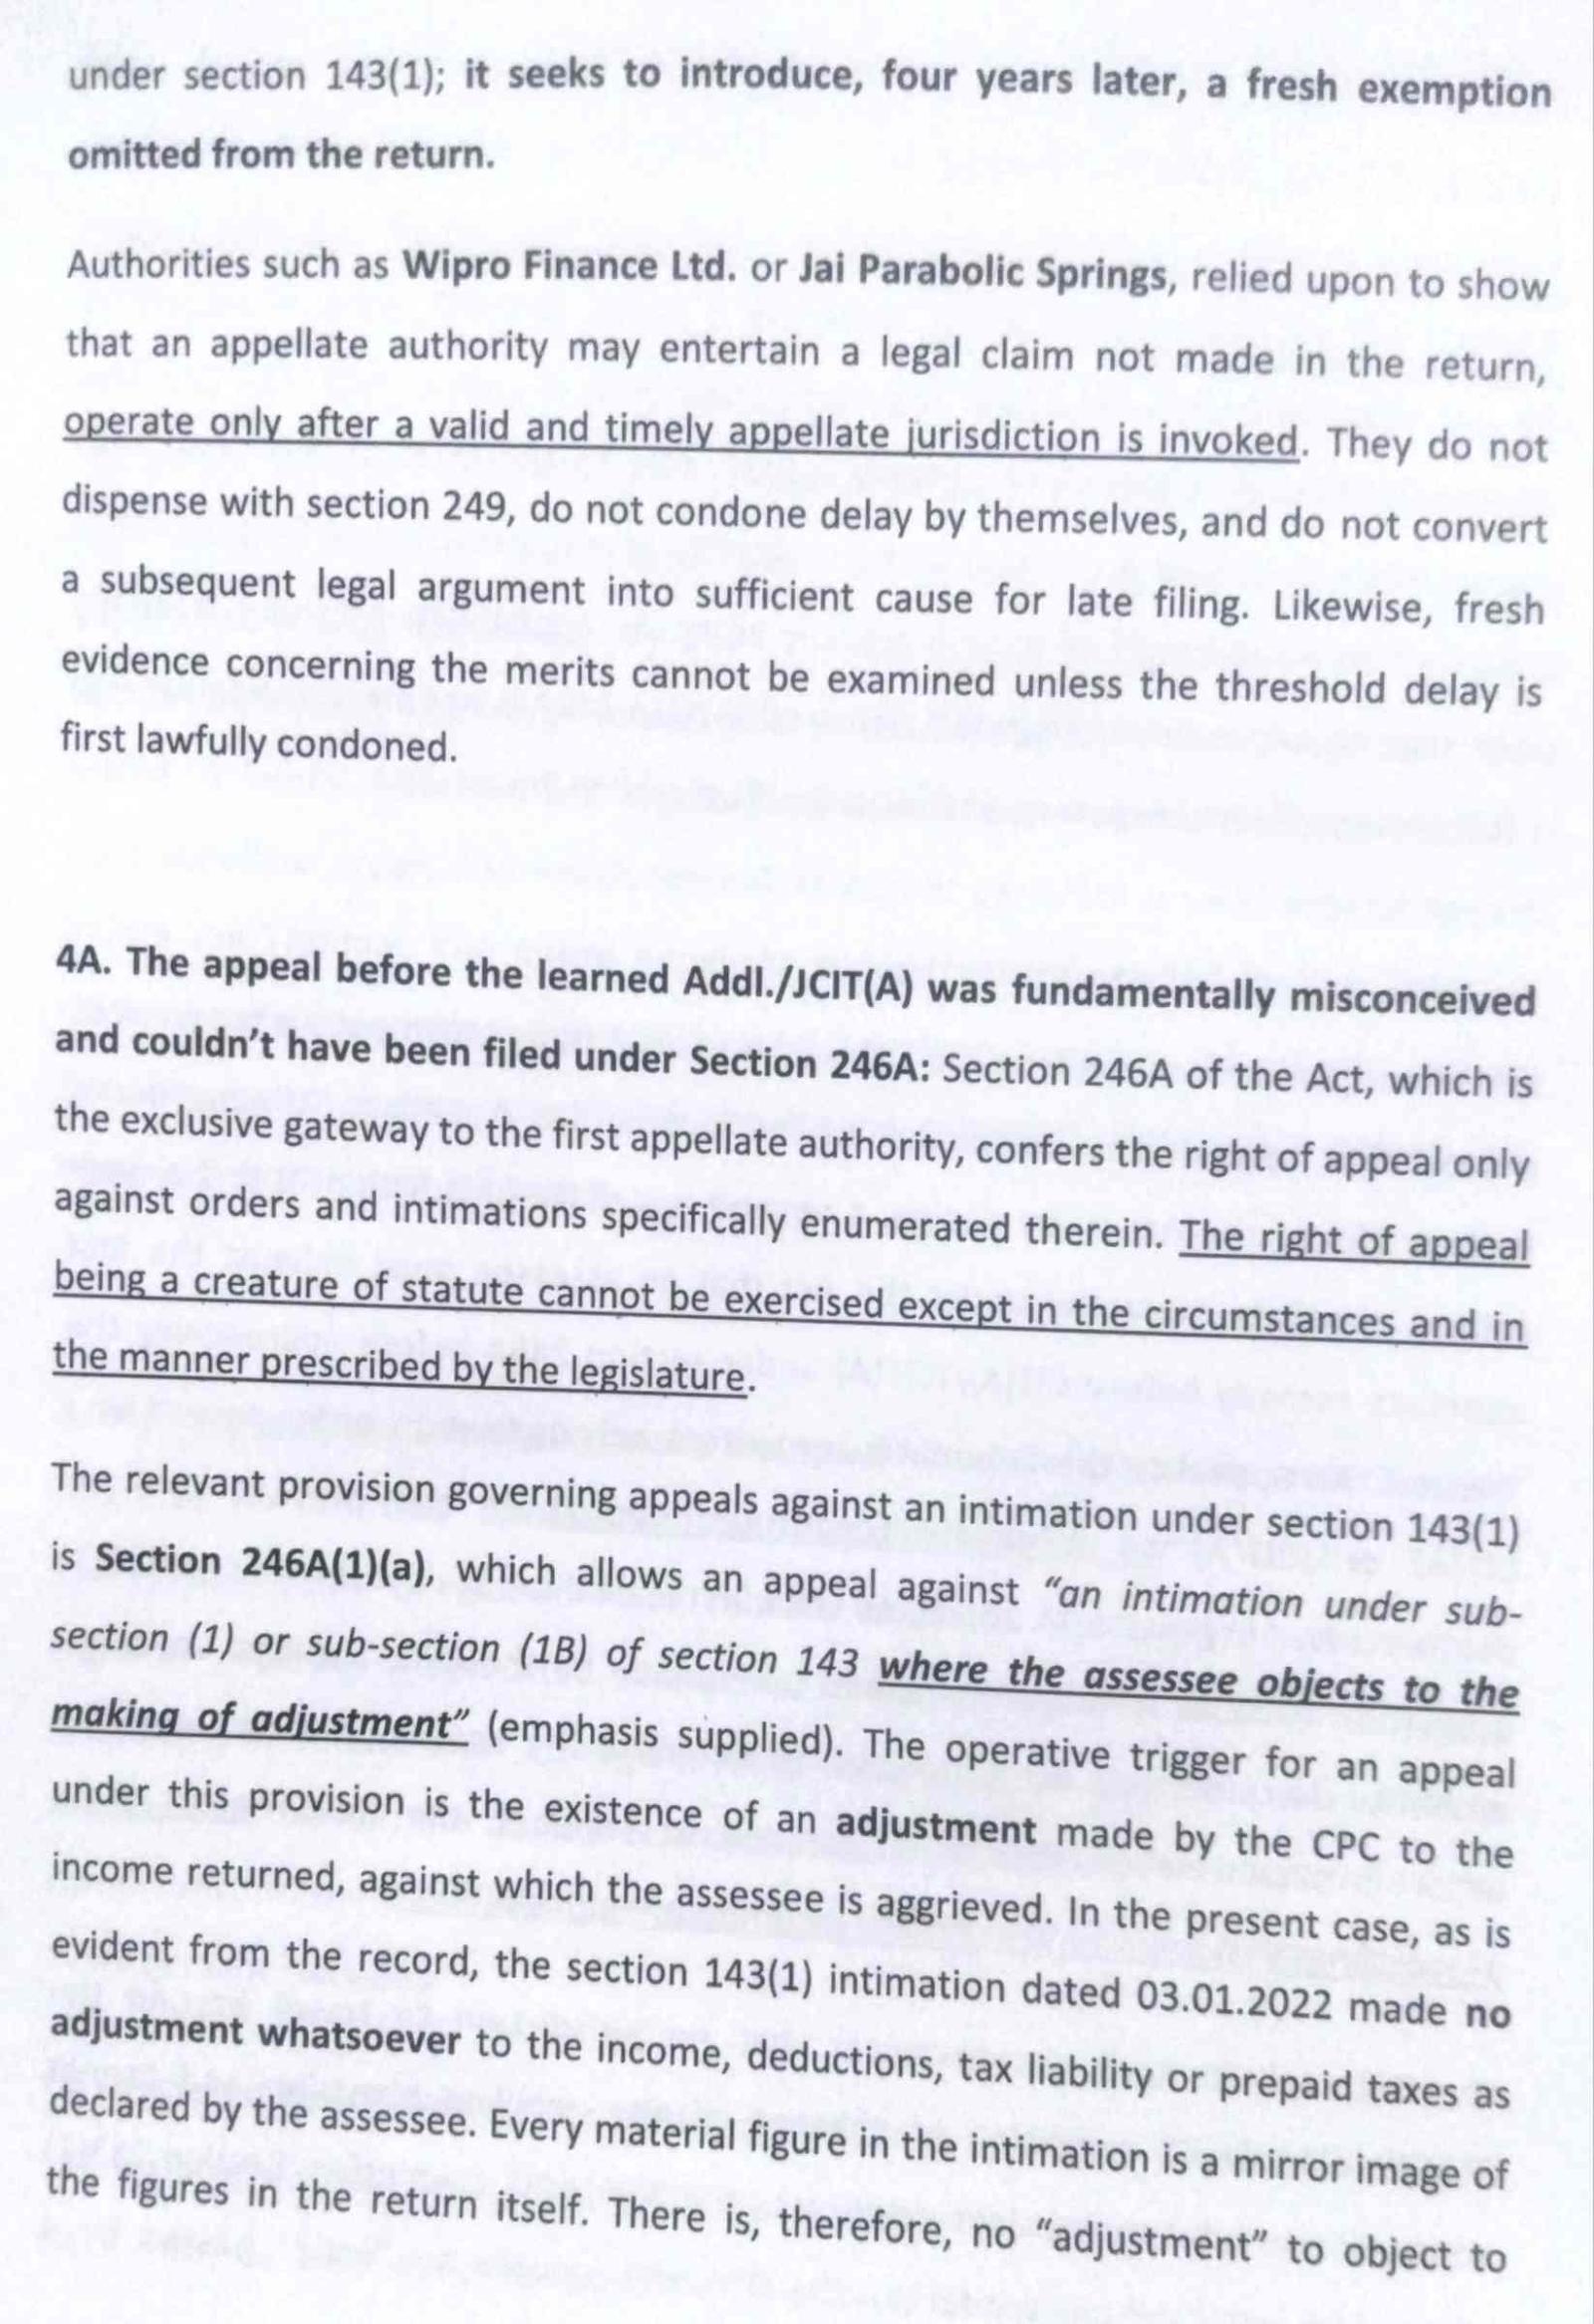
–
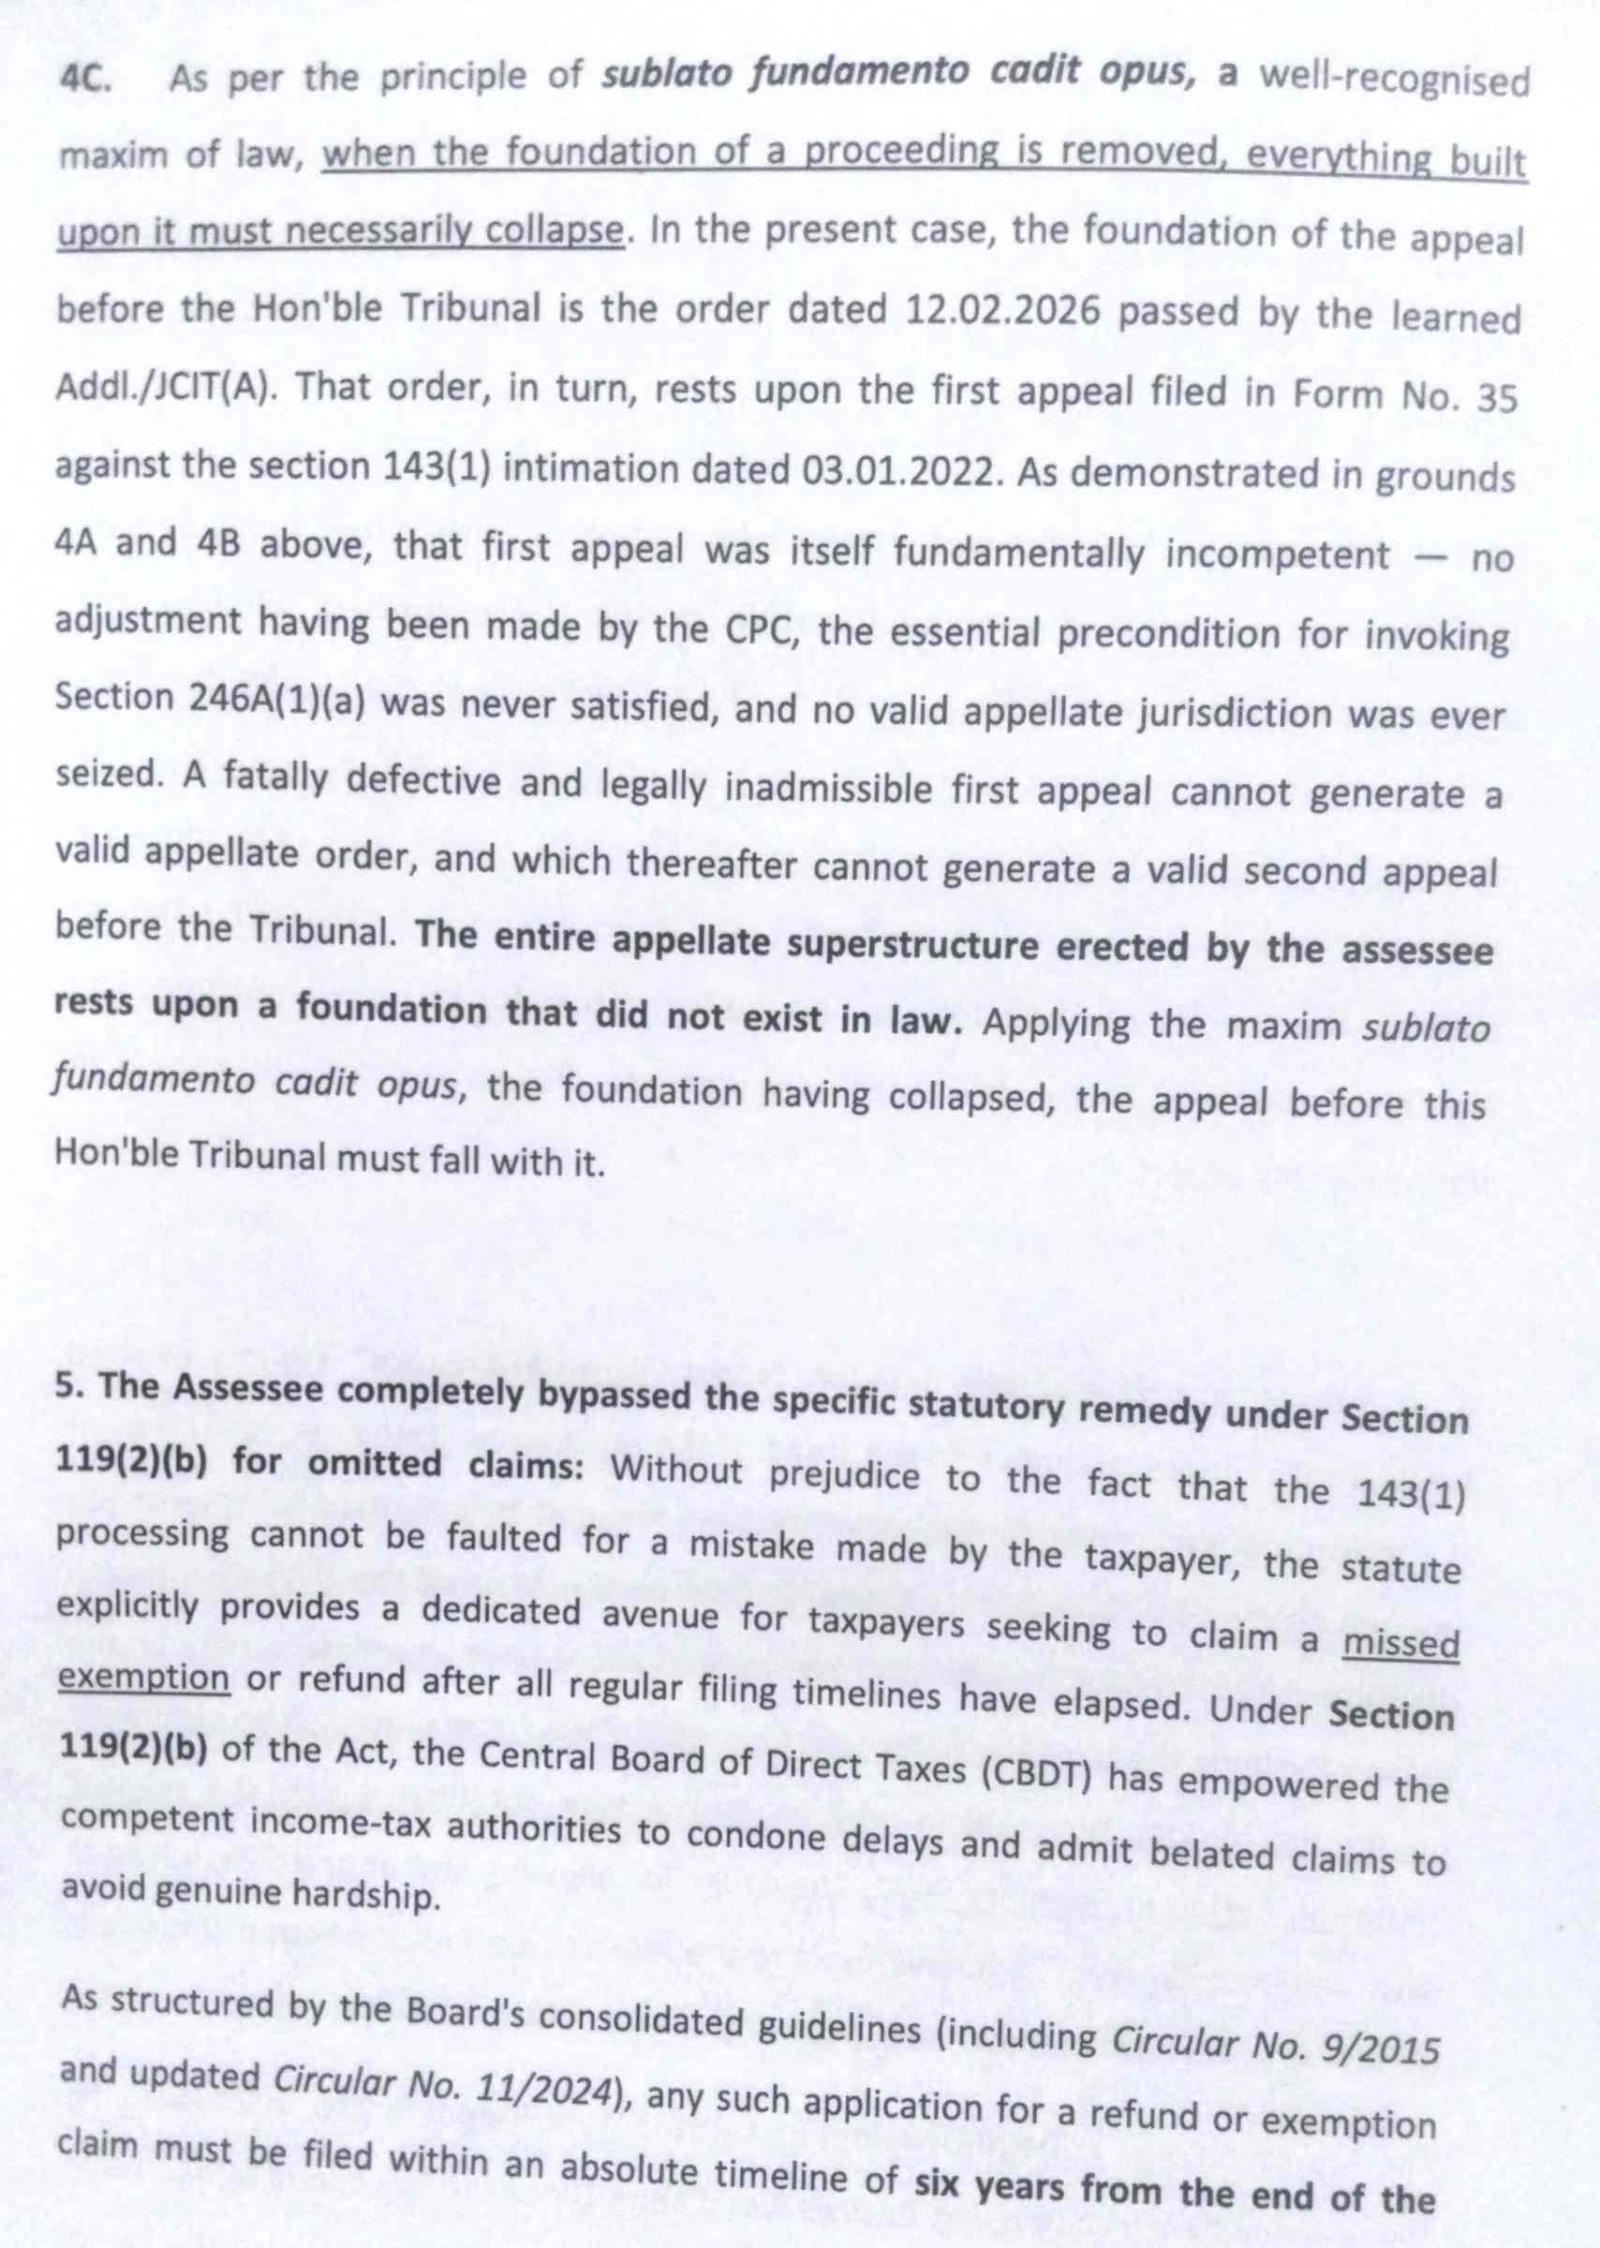
–
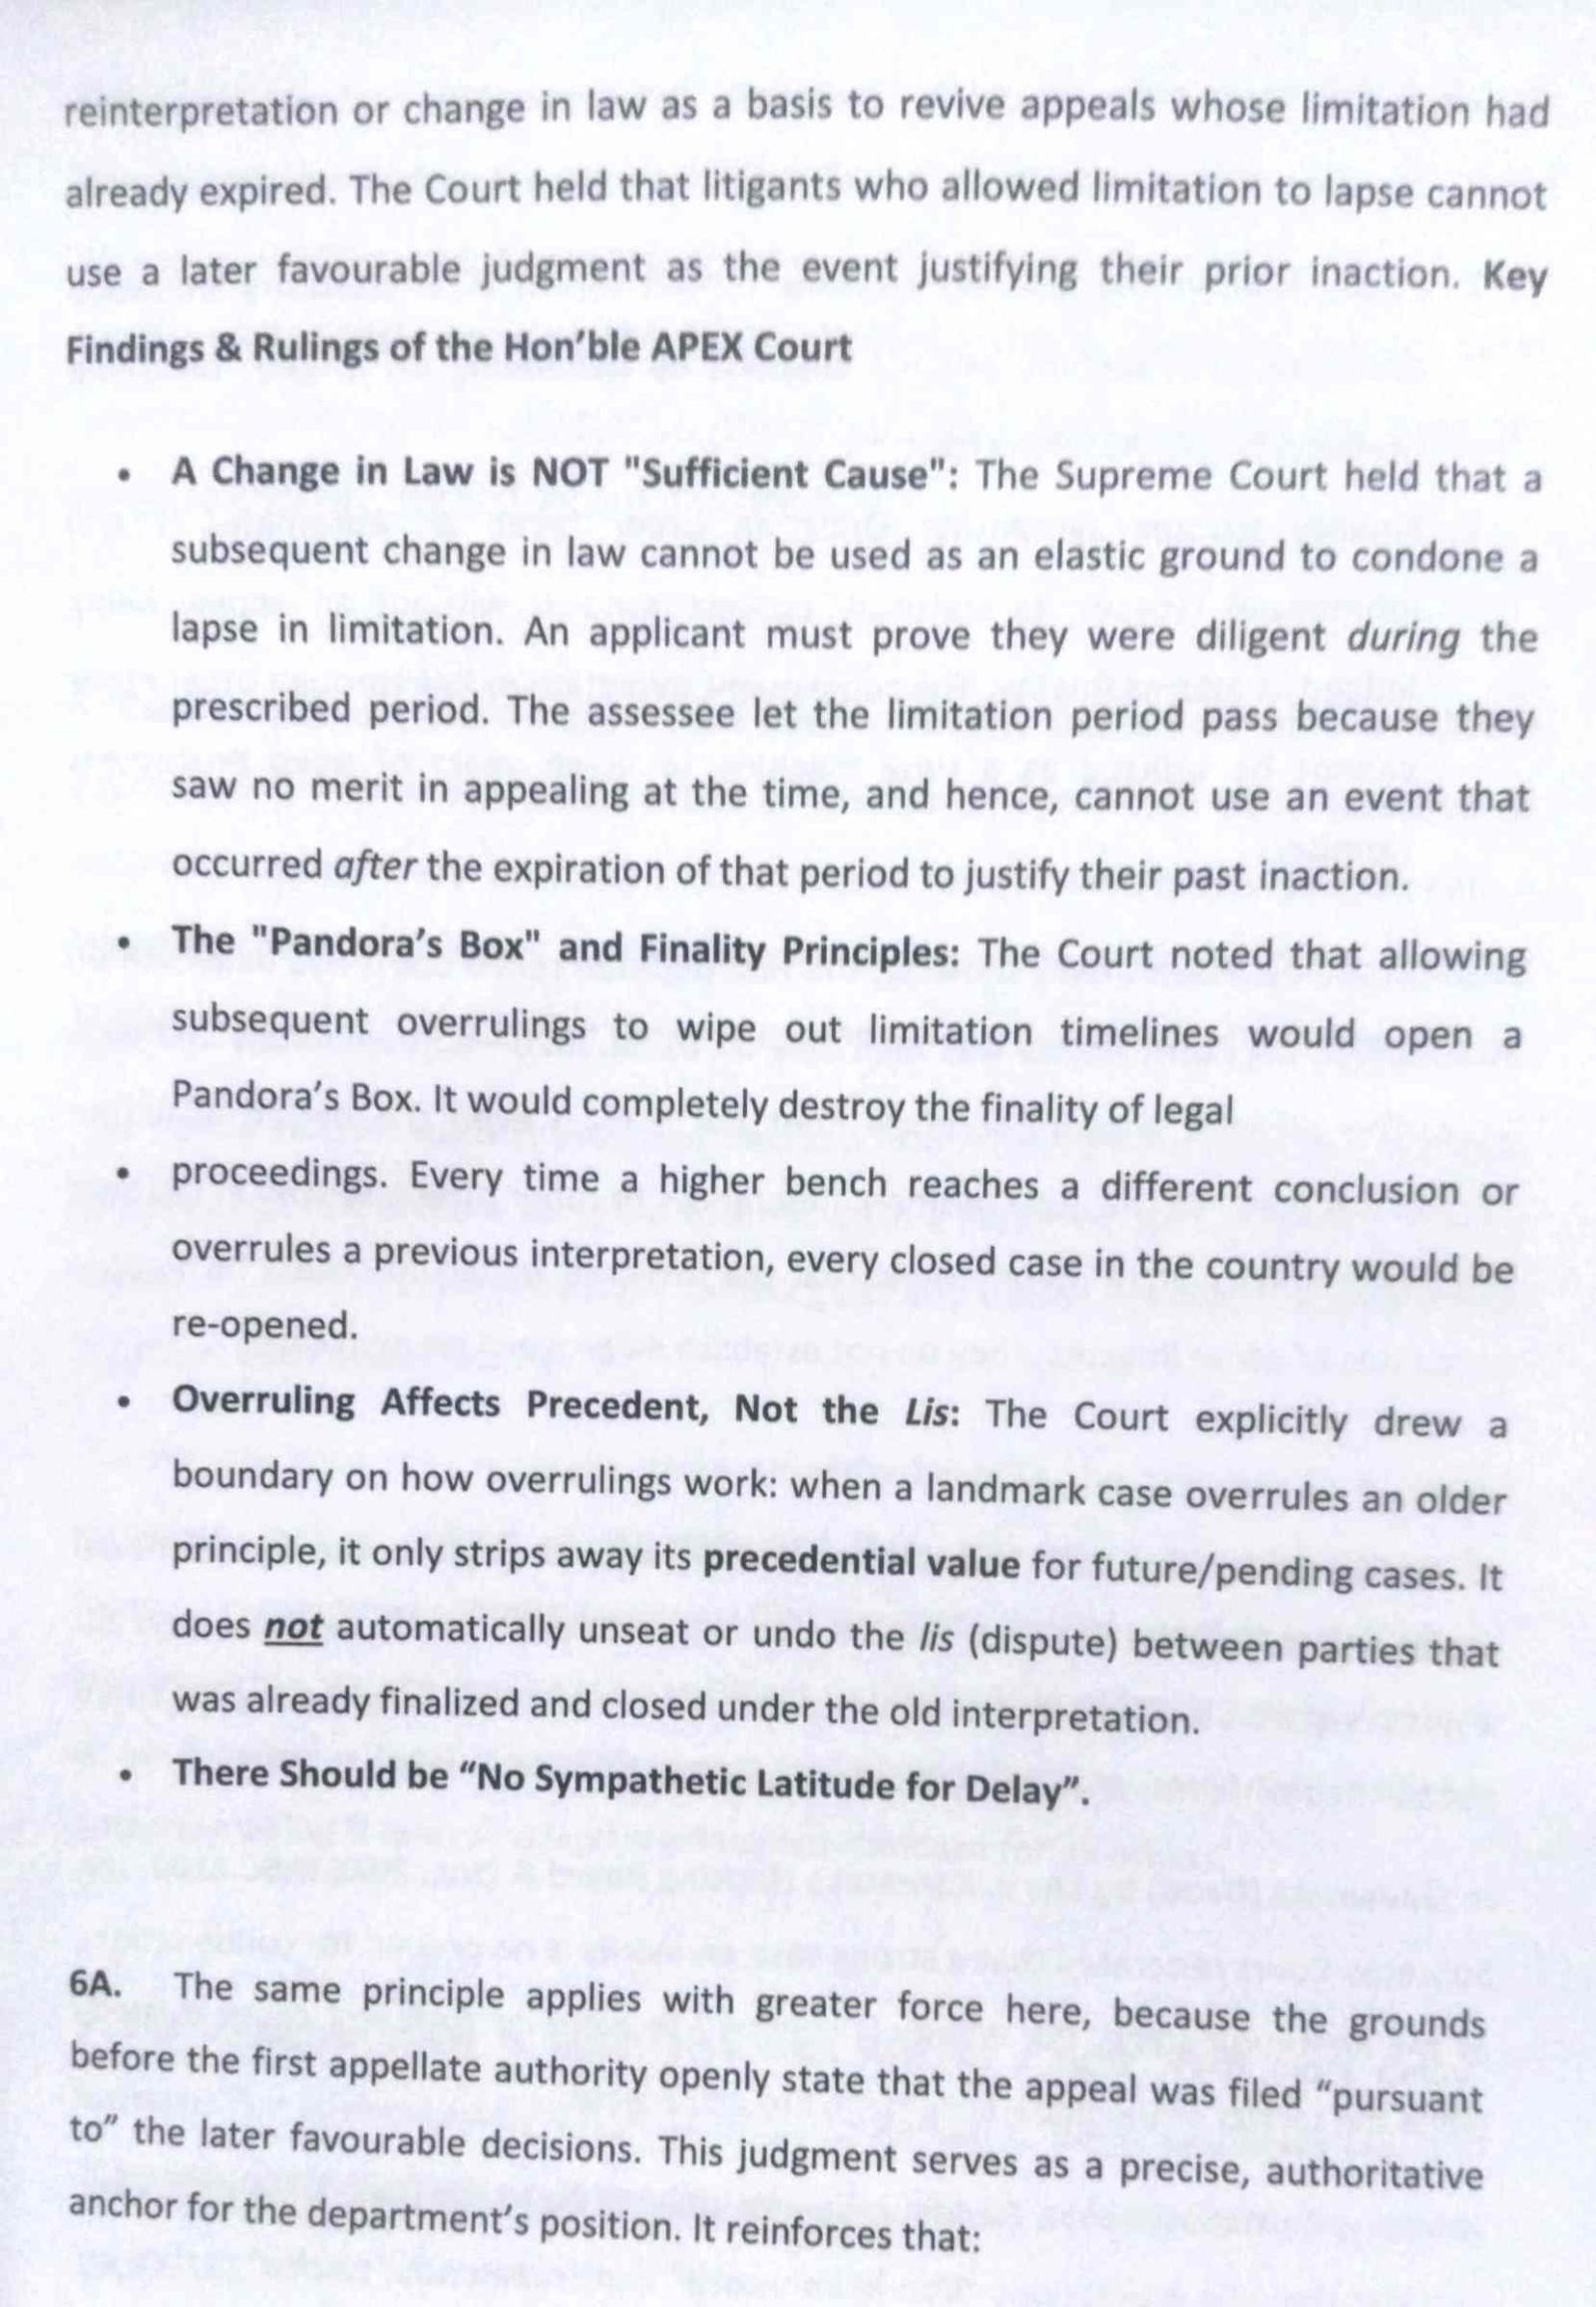
–
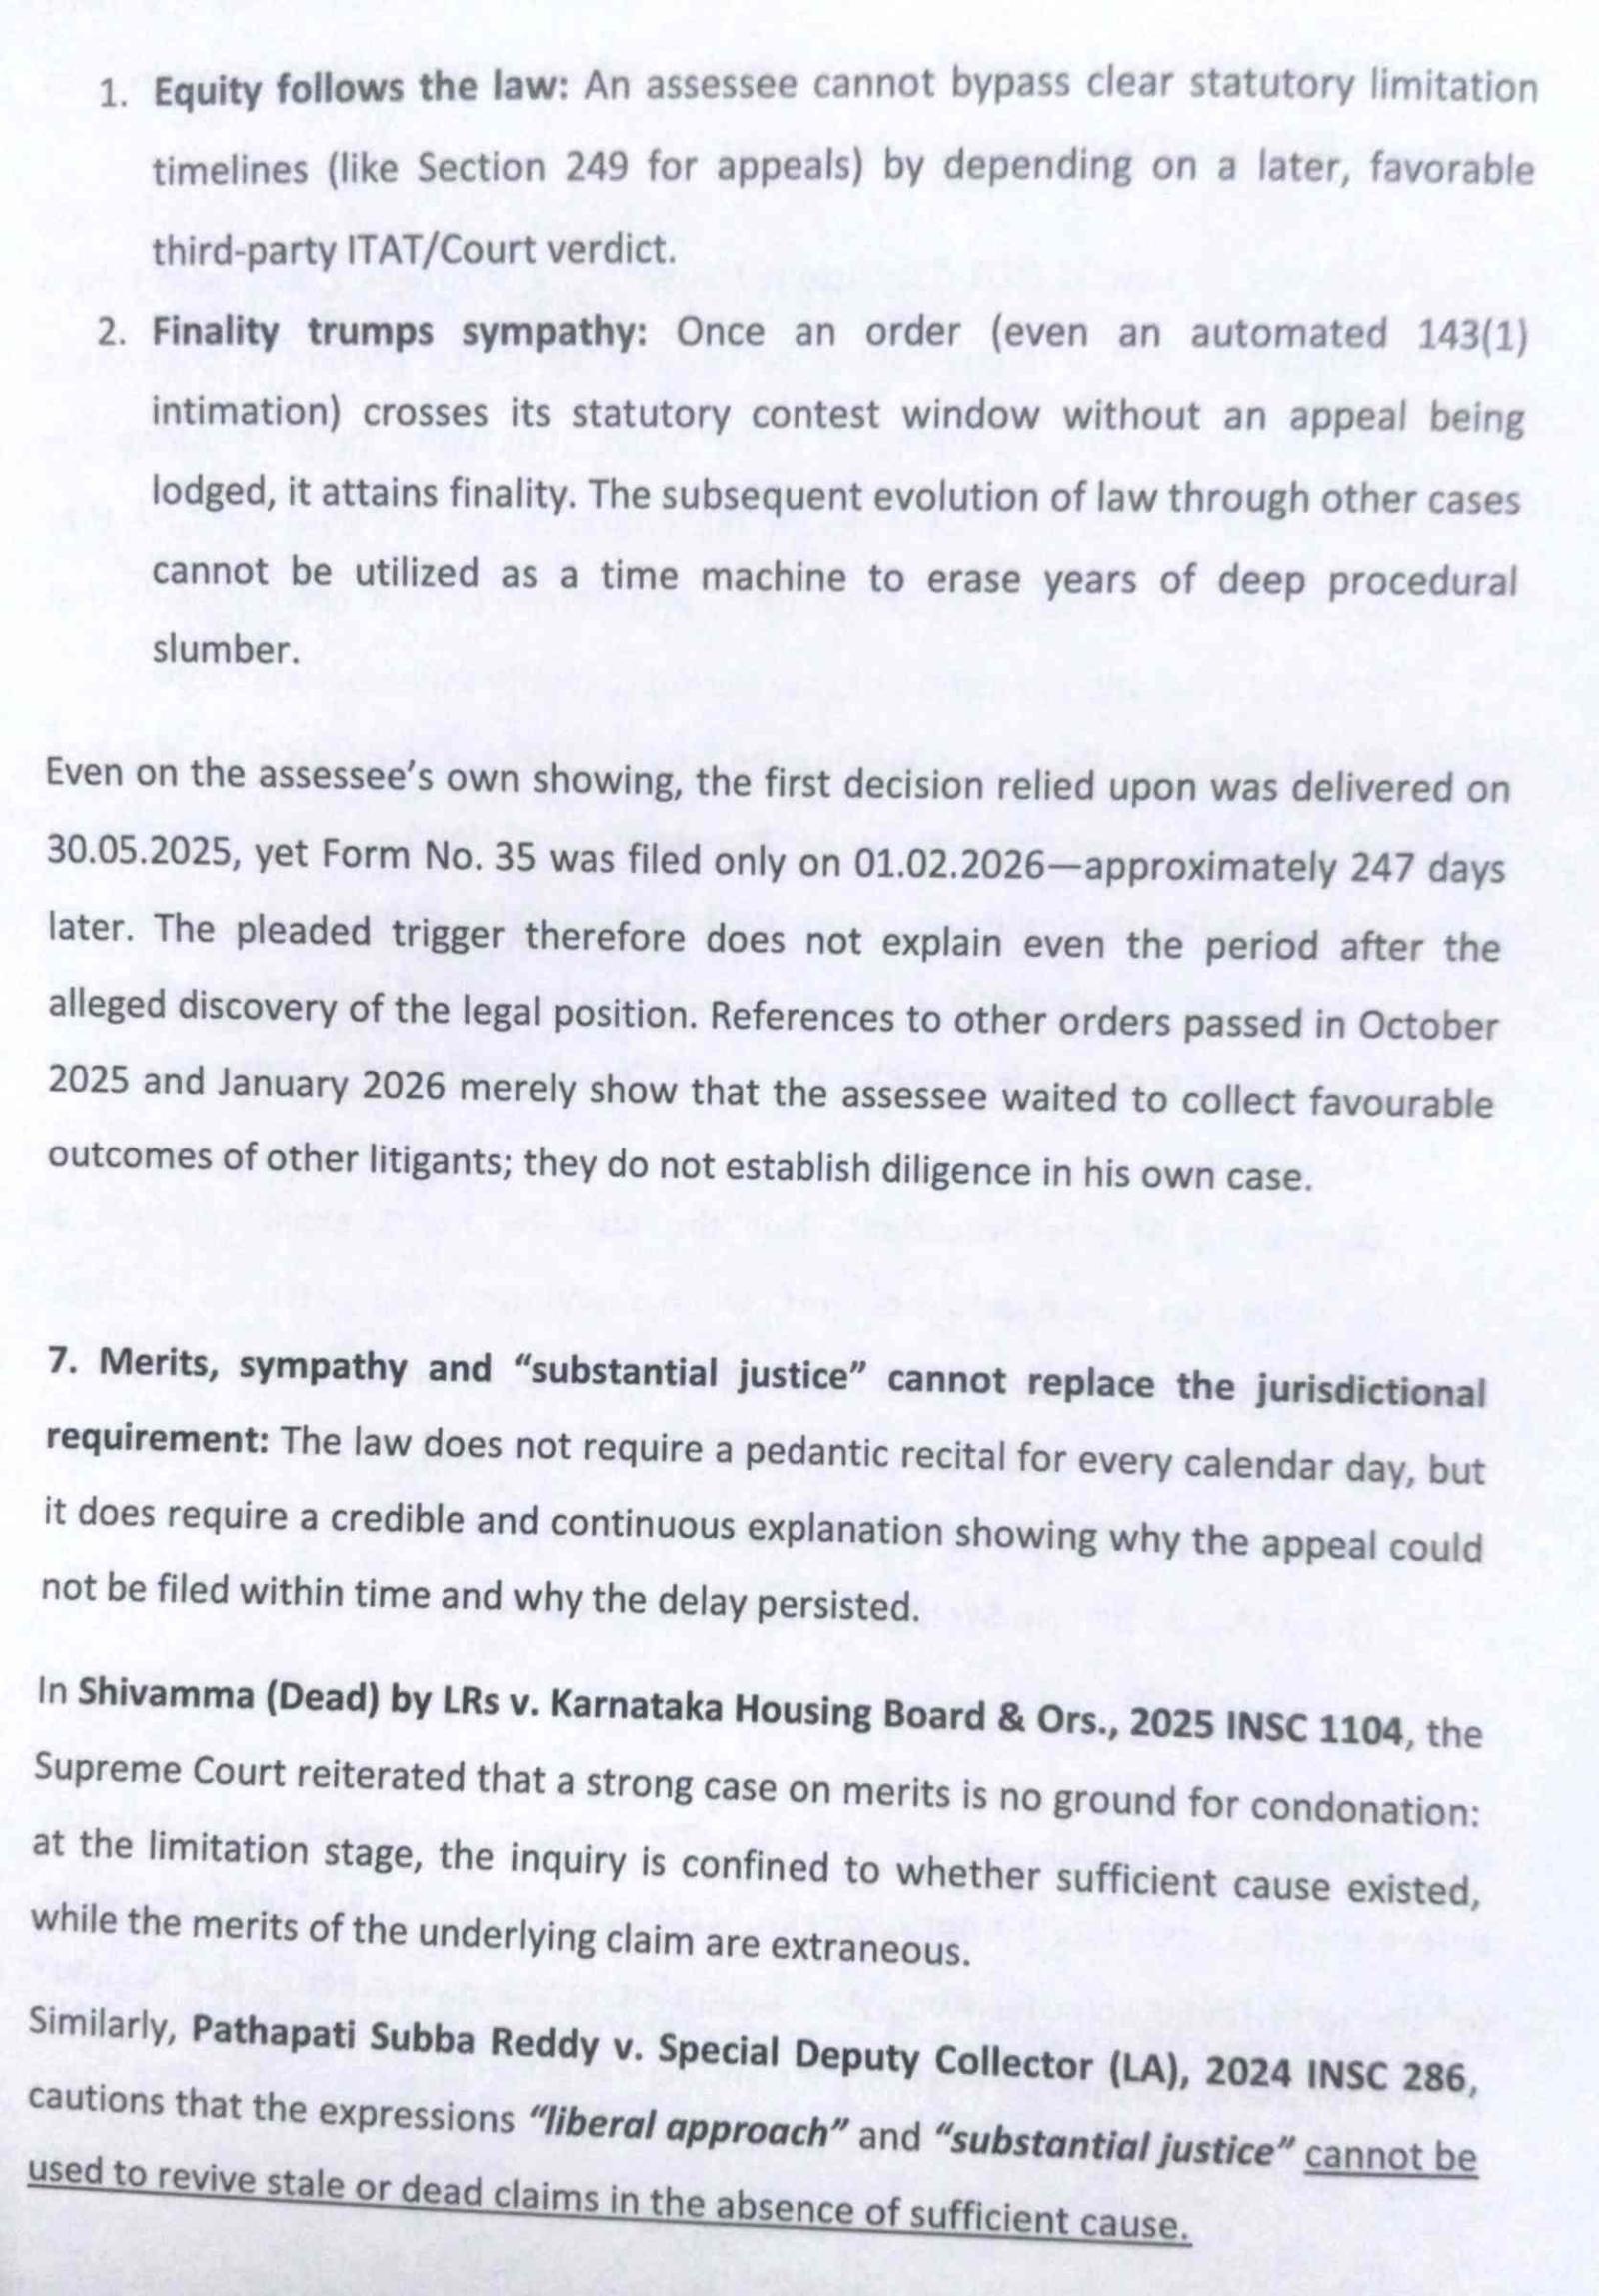
–
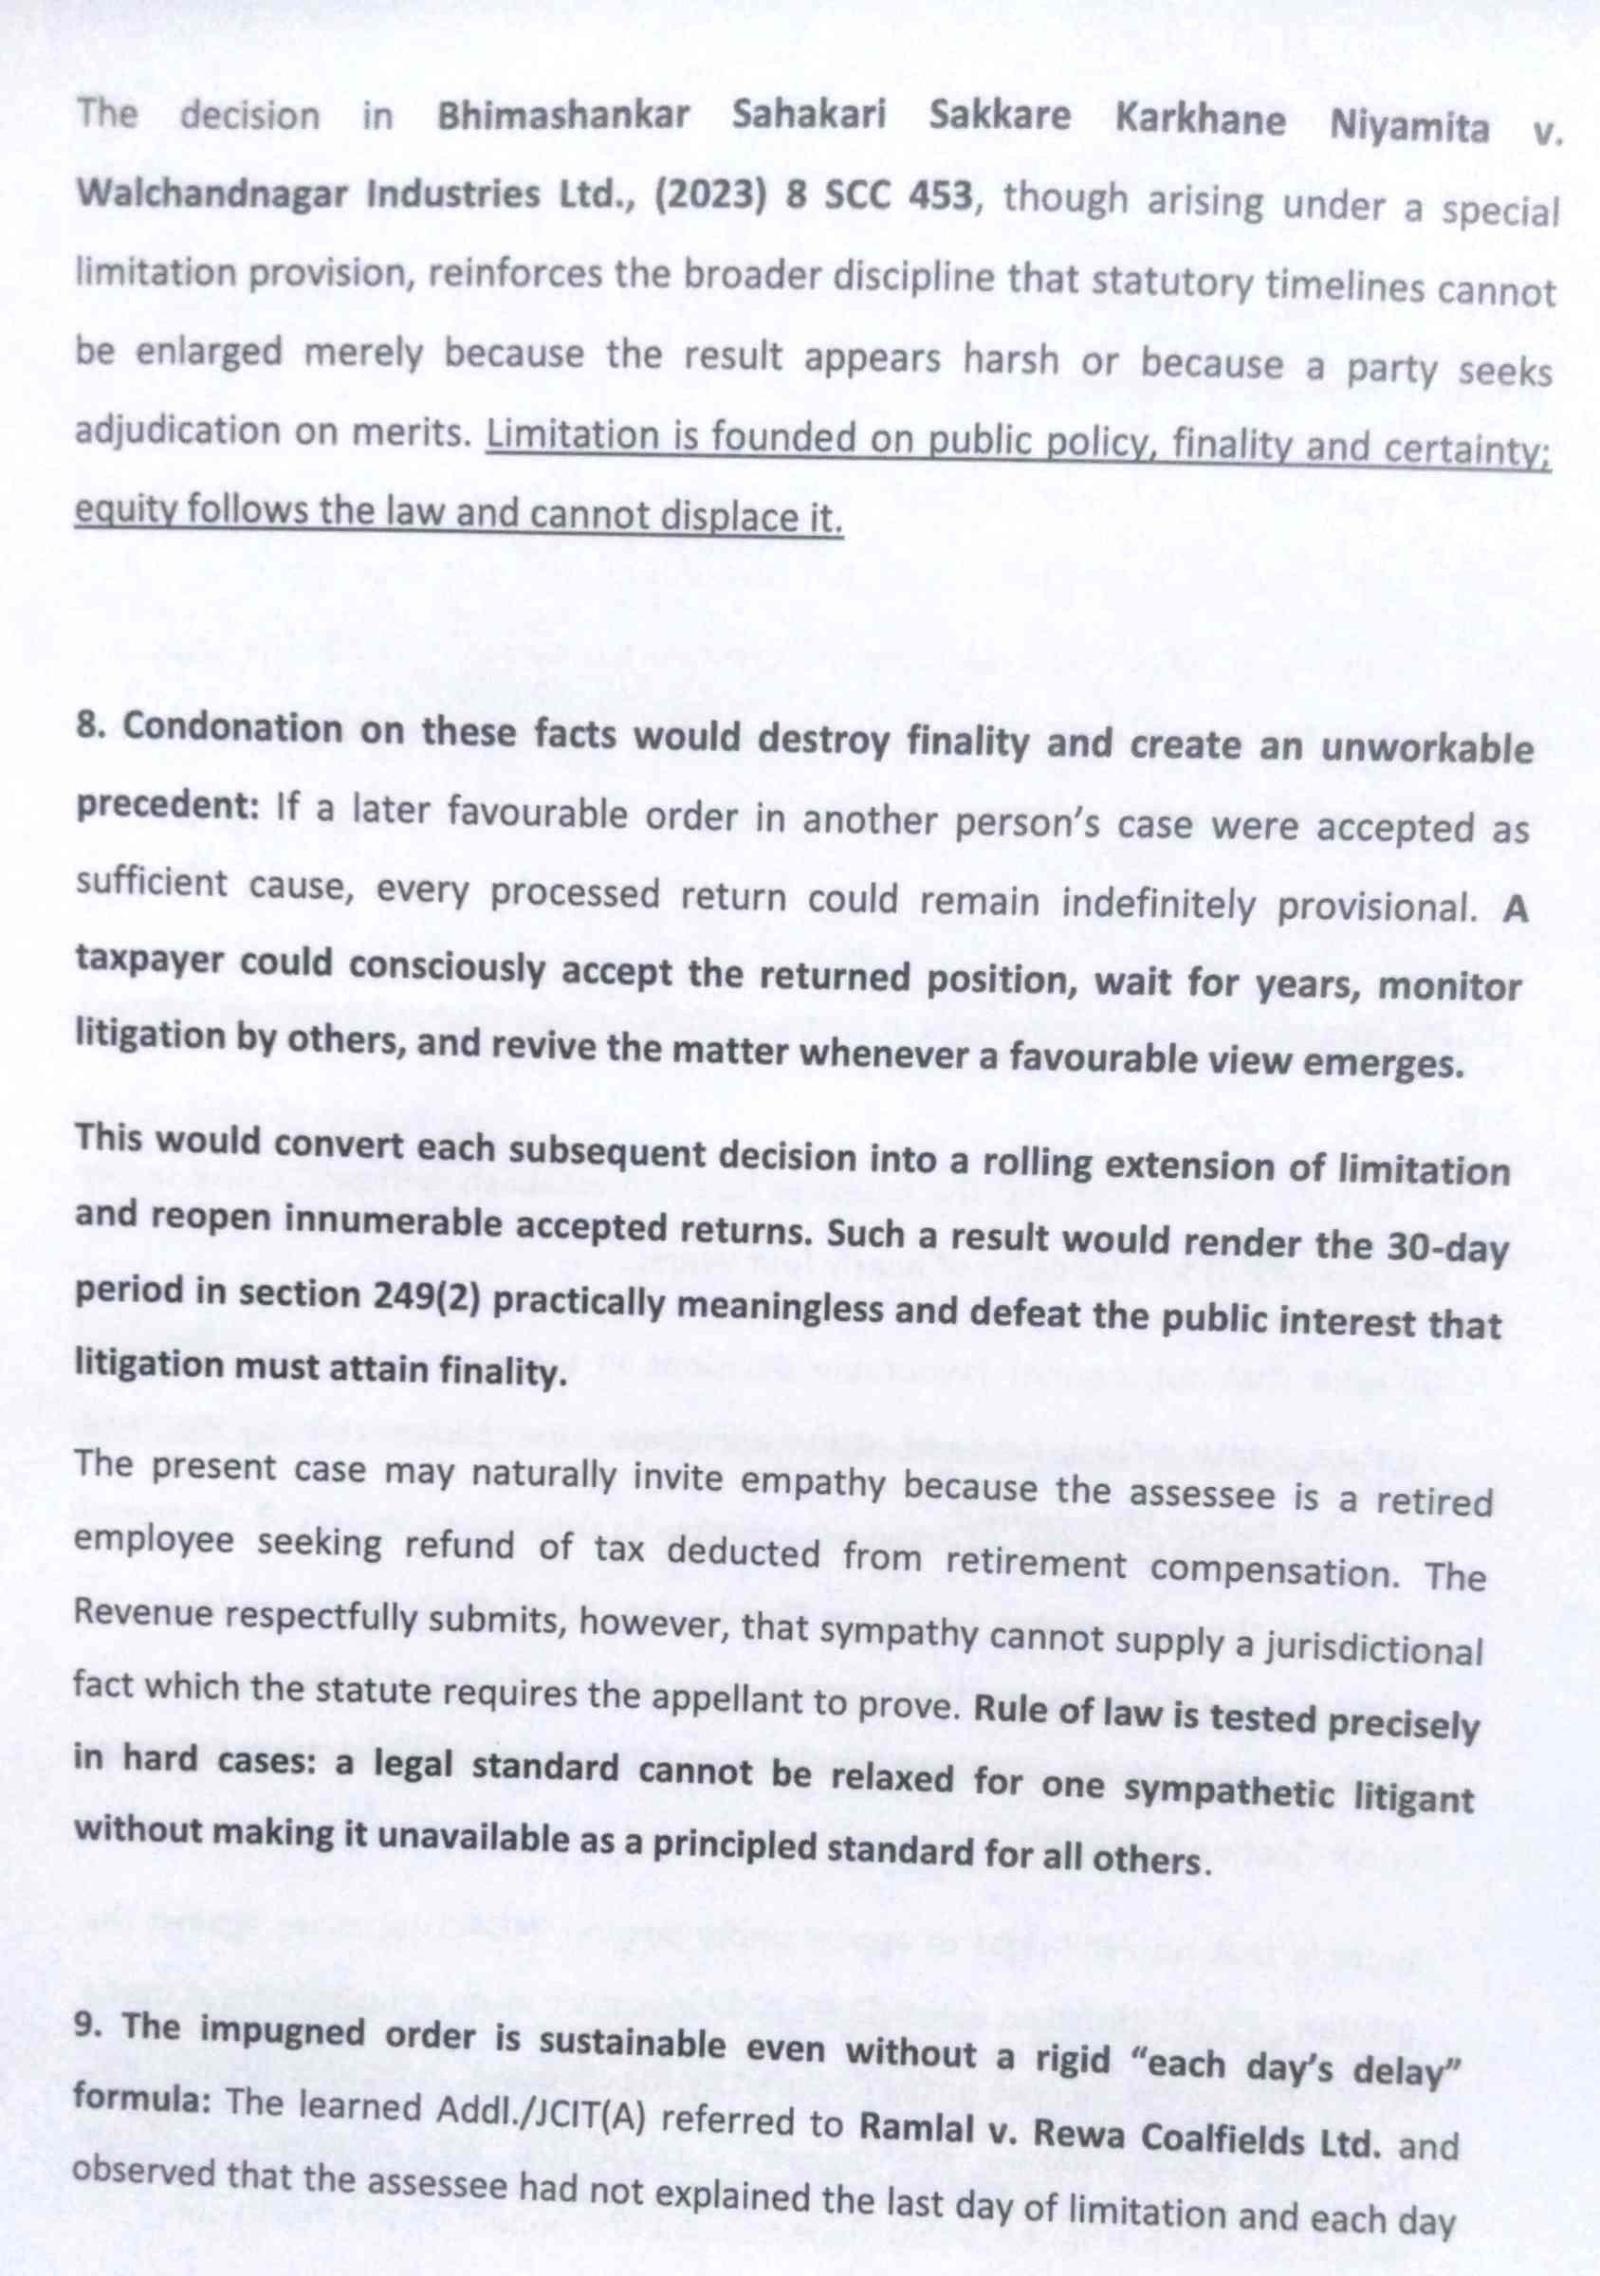
–
–
–
–
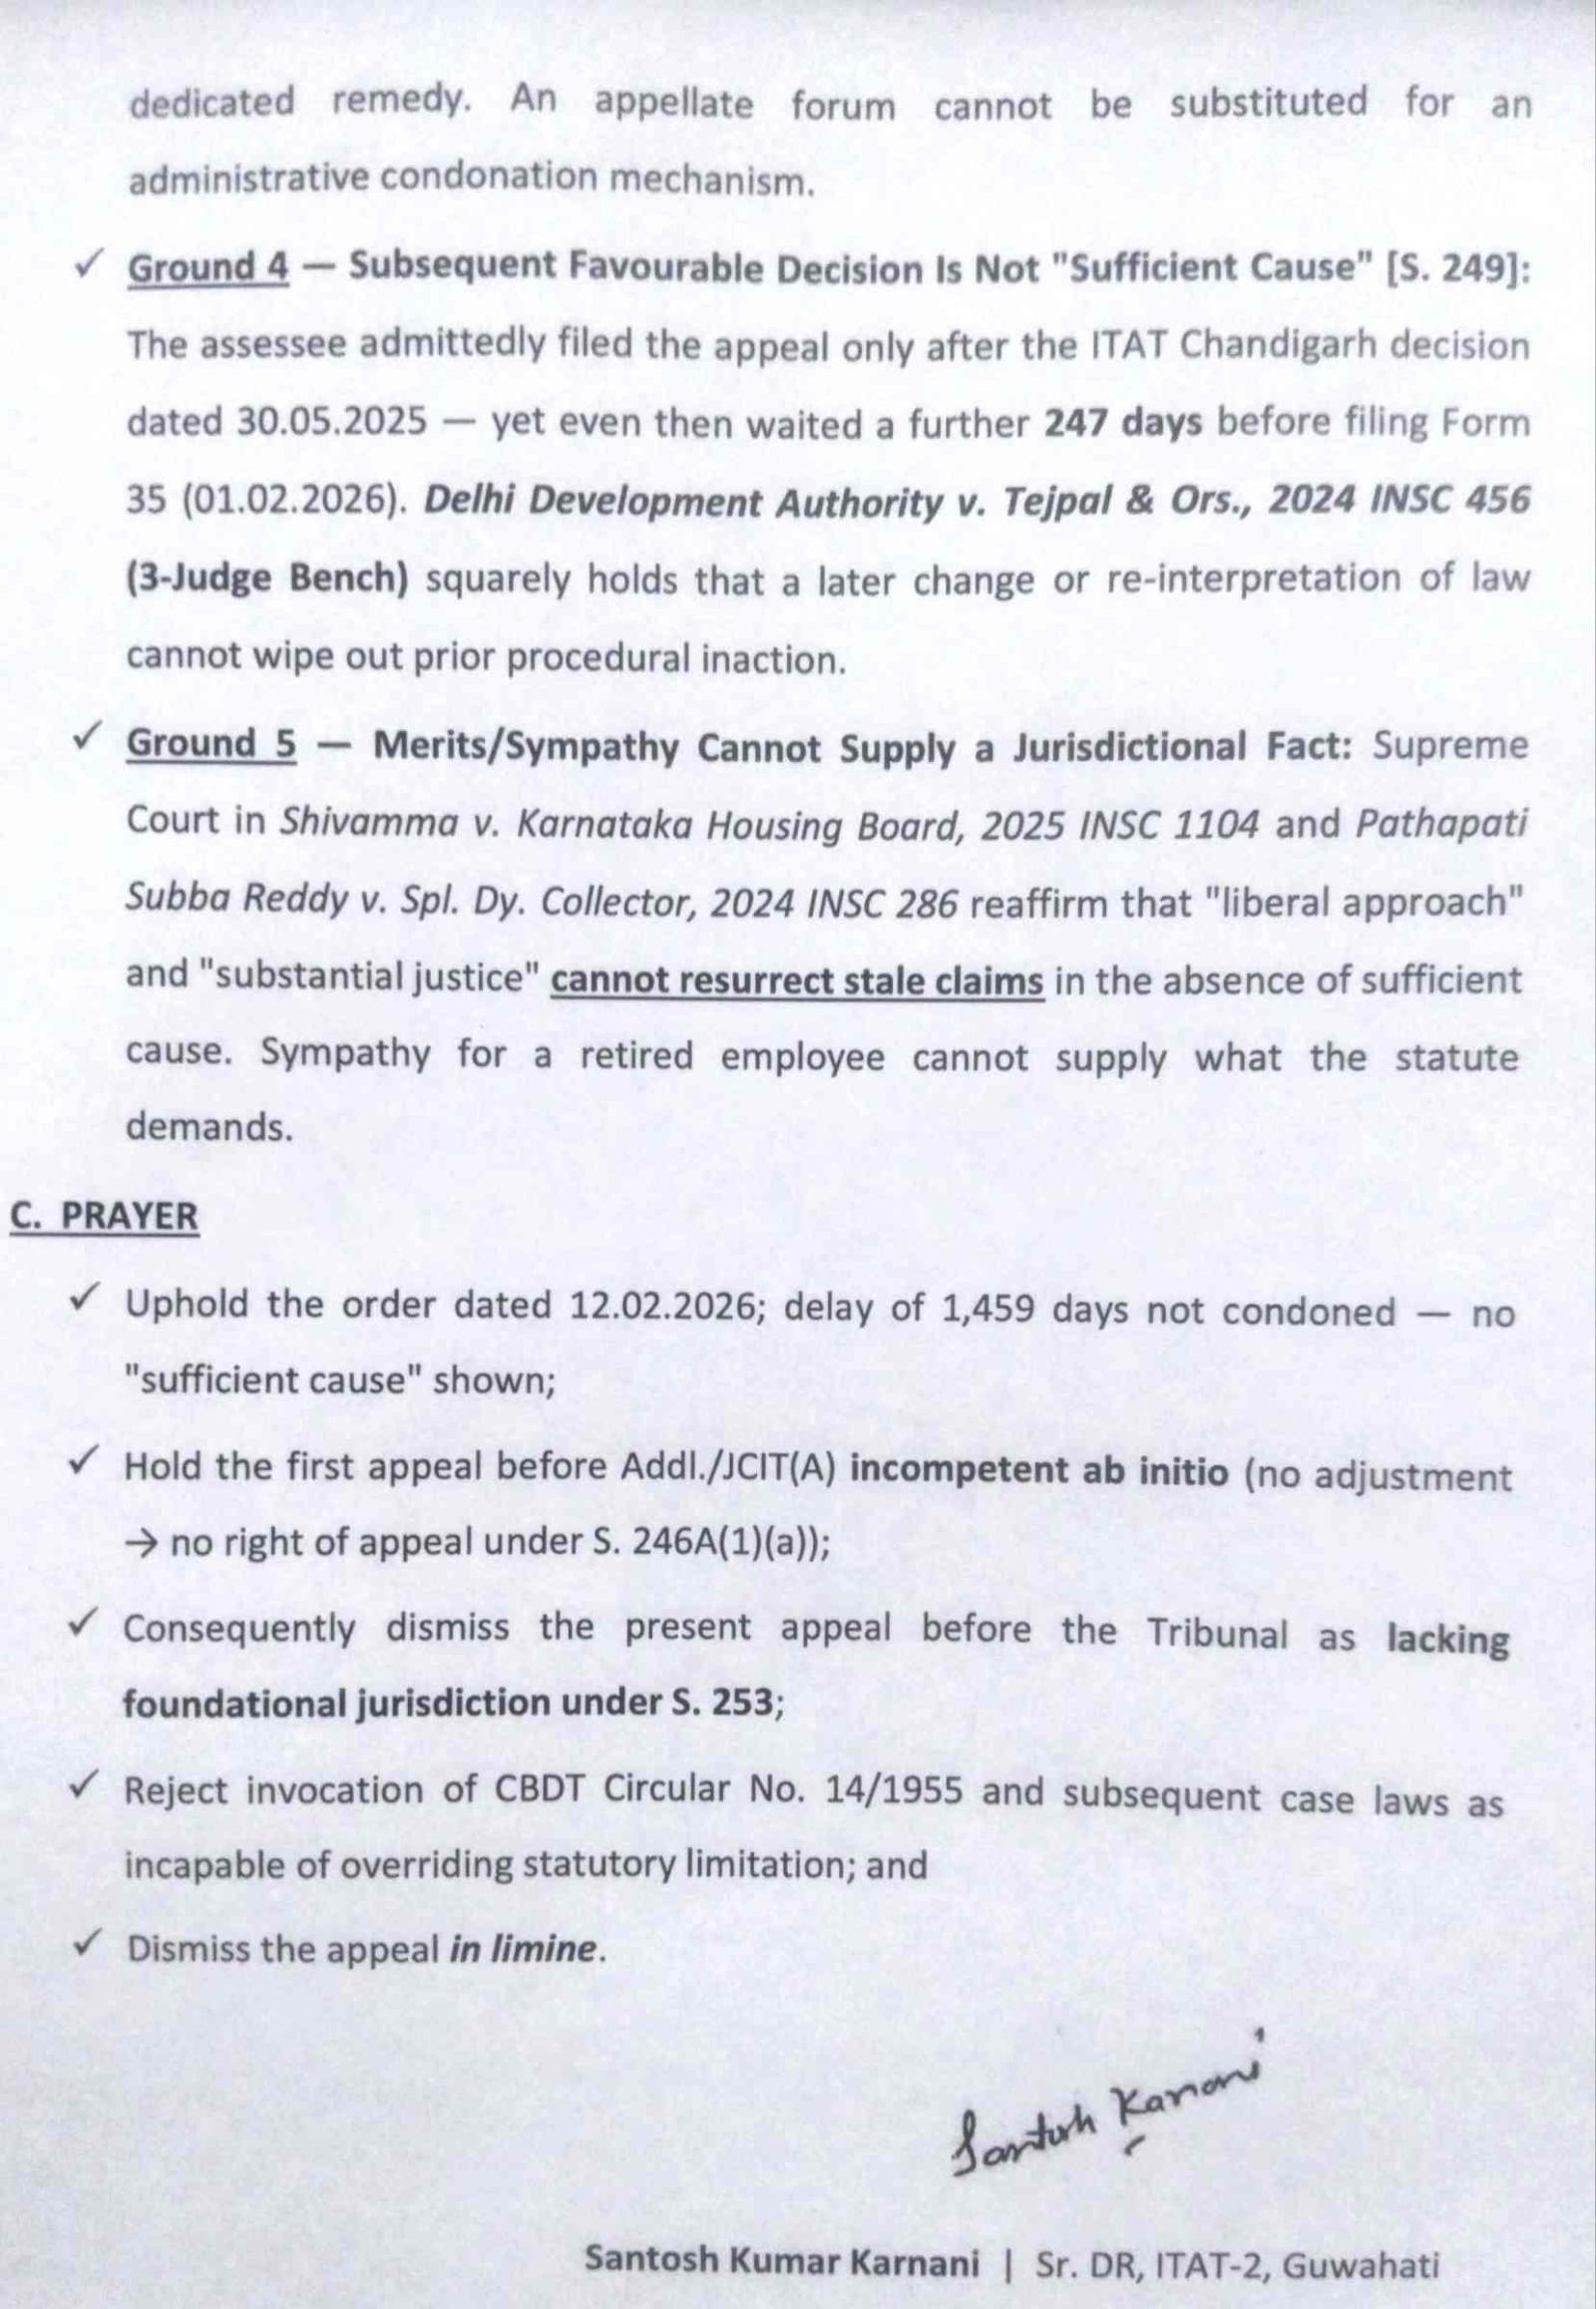
7. Considering the rival submission, we noted that the ld. CIT (A) has not condone the delay observing that there is no reasonable cause provided by the assessee for delay in filling the appeal. Here in the case on hand the assessee filed appeal after the judgement passed by the Co- ordinate bench of the ITAT Chandigarh on the similar set of facts and the co-ordinate bench has allowed the appeal of the assessee. The case of the assessee is also similar then why the assessee should deprive from not giving benefit of section 10(10B) of the Act. The assessee is also an employee of the BSNL and took VRS and got compensation as per the scheme framed by the BSNL. In the series of the judgements as relied by the ld. Counsel noted supra,the Co-ordinate bench has allowed the appeal of the assessee. Considering the condonation application submitted before the ld. CIT(A) noted supra we condone the delay before the ld. Cit(A). The ld. DR could not brought any materials against the above judgement that the Revenue has filed any appeal before the hire forum. The Ld. DR has relied on the judgement of hon’ble Apex Court in the case of Delhi Development Authority vs and others 2024 INSC 456is not applicable on the principle of parity of the same organisation. In one side the Income Tax Department has given benefit on the same set of facts and accepted the judgement of the co-ordinate bench of the ITAT and on the other side the ld. Dr is referring the judgemnt of the Hon’ble Apex Court which of the other organization. Although there is there is no cause of action arised from the order of the CPC-Bengaluru. The Income Tax Act itself has not given right to collect Tax on the compensation amount received, then the Income Tax Department should not collect tax on the exempt income as per section 10(10B) of the Act. The case law relied by the Ld. DR does not support the arguments of the ld. DR. However, the co-ordinate Bench of the ITAT, Ahmedabad Benche in the case of Jayeshkumr Tulsidas Sutaria Vs. ITO reported in (2026) 183 taxmann.com 587 (Ahmedabad-Trib) in ITA No. 2387& 2388/AHD/2025 order dated 17.02.2026has dealt with the similar issue condoning the delay and accepting the appeal of the assessee, the return was processed u/s 143(1) of the Act and there was no any demand in 143(1) processing. The Co-ordinate Bench has allowed the appeal of the assessee. For the sake of convenience, we are reproducing the entire judgment which is as under:
“The captioned two appeals have been filed by the Assessee against the orders passed by the learned Commissioner of Income Tax (Appeals) / National Faceless Appeal Centre (NFAC), Delhi, vide orders dated 14.10.2025, for the Assessment Years 2020-21 and 2021-22. Since the issues involved in both the appeals are common and identical, we extract the grounds of appeal raised in ITA No.2387/Ahd/2025 for Assessment Year 2020-21 for the purpose of adjudication. The decision rendered in the said appeal shall apply mutatis mutandis to the other appeal bearing ITA No. 2388/Ahd/2025 for Assessment Year 2021-22.
The assessee has raised the following grounds of appeal:
1. The Ld. CIT(A) has erred in law in holding that the appellant’s grievance does not emanate from the Intimation u/s 143(1) and in directing the appellant to seek condonation and file a revised return, Ignoring the settled legal position that appellate authorities are fully empowered to entertain and adjudicate a new claim even if not made in the return of income. The refusal to consider the exemption u/s 10(108) is contrary to the binding decisions of the Hon’ble Supreme Court in Jute Corporation of India Ltd. v. CIT (1991 taxmann.com 30 (SC)/(1991) 57 ELT 176 (SC)|04-09-1990), NTPC Ltd. v. CIT (1998) 229 ITR 383 (SC) and the Hon’ble Bombay High Court in Pruthvi
Brokers & Shareholders Pvt. Ltd, which categorically hold that filing a revised return is not mandatory for making a new claim. The finding of the CIT(A) is therefore illegal, perverse and liable to be set aside
2. The Ld. CIT(A) has erred in dismissing the appeal as “not maintainable” on the incorrect assumption that the issue does not arise from the intimation u/s 143(1), without appreciating that the said Intimation has assessed VIRS compensation without granting exemption u/s 10(100). This has resulted in an adverse tax consequence, thereby giving rise to a valid, appealable grievance under section 246A. The conclusion of the CIT(A) is contrary to facts and law.
3. The Id. CIT(A) has erred in refusing to adjudicate the exemption claim u/s 10(108) on merits, thereby violating section 250(6) mandating a reasoned and speaking order on each ground of appeal. The impugned order is nonspeaking, arbitrary, contrary to statutory requirements, and deserves to be quashed.
4. The Ld. CIT(A) has committed a serious error in law by directing the appellant to approach the PCIT for condonation and filing of a revised return, thereby unlawfully bypassing and abandoning his own statutory appellate jurisdiction. The powers vested in the CIT(A) under section 251 are wide and Include the authority to entertain and allow a fresh legal claim. in contrast, the PCIT acting under section 119(2)(b) cannot adjudicate or grant exemption u/s 10(108). The impugned direction amounts to abdication of duty, rendering the order bad in law.
5. The Ld. CIT(A) has failed to appreciate that the appellant received compensation under the duly approved “BSNL VRS-2019” scheme, which fully satisfies the conditions prescribed under Rule 2BA and is eligible for exemption u/s 10(108). The CIT(A) ignored relevant judicial precedents, including the recent decision of the Hon’ble ITAT Chandigarh in Harish Kumar vs. ITO (ITA No. 42/CHD/2025, dated 30.05.2025),wherein identical BSNL VRS-2019 benefits were held eligible for exemption. The order is therefore contrary to law and merits reversal.
6. The learned CIT(A) erred in refusing to consider the exemption u/s 10(108) merely because it was not claimed in the return, in complete disregard ofCBDT Circular No. 14 of 1955 which obligates tax authorities to grant all lawful reliefs even if not claimed by the assessee. The impugned order is therefore contrary to binding CBDT directions and bad in law.”
3. The assessee was employed with Bharat Sanchar Nigam Limited (BSNL), a Government of India enterprise. BSNL notified the Voluntary Retirement Scheme (VRS) 2019 on 04.11.2019, which was duly approved and implemented by the employer. The assessee opted for the scheme and accordingly received compensation under the VRS, as per the terms laid down by BSNL. It is submitted that the assessee had not been paid regular salary for several months prior to opting for the scheme and was under severe financial and professional uncertainty. In view of these circumstances, the assessee opted for the scheme as a measure of financial security. The compensation received by the assessee was in the nature of compensation under the BSNL VRS-2019 scheme. The compensation amount received under the scheme was offered to tax in the return of income due to lack of awareness regarding the exemption available under section 10(10B) of the Income-tax Act, 1961. The employer had also deducted tax at source on the said amount. No exemption was claimed in the original or revised return of income. The CPC, Bengaluru issued an intimation under section 143(1) for the said year without granting any exemption, and no rectification or appeal was initiated at that time. It was only upon learning about the recent judgment of the Hon’ble ITAT Chandigarh Bench in the case of Harish Kumar vs. ITO Ward 5(5), Chandigarh (ITA No. 42/CHD/2025, dated 30.05.2025) that the assessee became aware that the compensation received under the BSNL VRS-2019 scheme is eligible for exemption under section 10(10B), subject to compliance with Rule 2BA.
4. Aggrieved by the orders of the Assessing Officer, the assessee carried the matter in appeal before the Ld.CIT(A), who dismissed the appeal of the assessee by observing as follows:
“…The Appellant was employed with Bharat Sanchar Nigam Limited (BSNL), a Government of India enterprise. BSNL had notified the Voluntary Retirement Scheme (VRS) 2019 on 04.11.2019, which was duly approved and implemented by the employer. The Appellant opted for this scheme and accordingly received compensation under the VRS, as per the terms laid out by BSNL. The compensation amount received under the scheme was offered to tax by the appellant in the return of income due to lack of awareness about the availability of exemption under Section 10(10B) of the Income Tax Act. 1961. The employer had also deducted TDS on the said amount. No exemption was claimed in the original or revised return for the year by the appellant. The CPC, Bengaluru issued an intimation u/s 143(1) for the said year without granting any exemption, and no rectification or appeal was initiated at that time. The issue on this appeal pertains to exemption u/s 10(10B) of the Income Tax Act.
The appellant in his written submission has stated that it was only upon learning about the recent judgment of the Hon’ble ITAT Chandigarh, in the case of Harish Kumar vs. ITO Ward 5(5), Chandigarh (ITA No. 42/CHD/2025, dated 30.05.2025), that the Appellant came to know that the compensation received under the BSNL VRS 2019 scheme is eligible for full exemption u/s. 10(10B), subject to Rule 2BA compliance.
The grievance raised in the grounds of appeal does not emanate from the order appealed against. It is not a case where the appellant claimed exemption u/s.10(10B) and it was denied by the Assessing Officer. The appellant having omitted to claim relief in the return of income can claim the relief by filing the revised return. In cases where the time limit for filing the revised return has expired, the appellant may seek condonation of delay from the jurisdiction PCIT and then proceed with filing the revised return. The issue raised in grounds of appeal does not emanate from the order of intimation u/s.143(1). Hence, the appeal is dismissed…
” 5. Aggrieved by the orders of the Ld.CIT(A, the assessee is in further appeal before us.
6. The Ld. Counsel for the assessee submitted that due to lack of awareness of the legal provisions at the time of filing the return of income, the assessee inadvertently offered the compensation received under BSNL VRS-2019 to tax. Subsequently, based on the decision of the Hon’ble ITAT Chandigarh Bench in Harish Kumar vs. ITO Ward 5(5), Chandigarh (ITA No. 42/CHD/2025 dated 30.05.2025), wherein compensation under the same BSNL VRS-2019 scheme was held to be exempt under section 10(10B), the assessee now seeks exemption of such compensation. We find that the assessee filed the claim before the Ld. CIT(A) and since the income of the assessee is not taxable, the assessee is eligible for the refund of the TDS.
7. In the result, both the appeals of the assessee are allowed.”
8. The above judgments relied by the Ld. Counsel supports the case of the assessee on the similar set of facts. Respectfully following the judgment cited (supra), we allow the appeal of the assessee.
9. In the result, all 47 appeals filed by the different assessees are allowed in above terms.
10. A common order passed shall be kept in the respective case files.
Order pronounced on 30.06.2026.








