
Dinesh Kumar Tiwari Vs ITO (ITAT Raipur)
The Income Tax Appellate Tribunal (ITAT), Raipur Bench, adjudicated an appeal filed by the assessee against the order of the Commissioner of Income Tax (Appeals)/NFAC dated 17.09.2025 for the assessment year 2017–18.
The matter originated from a survey conducted under Section 133A of the Income Tax Act, 1961 in the case of Mahadev Cars Pvt. Ltd. During the survey proceedings, it was noticed that the assessee had purchased a car in cash during the relevant year. A statement on oath was recorded in which the assessee accepted that the amount of ₹12,65,000 invested in the purchase of the car represented undisclosed income for that year.
Subsequently, in written submissions, the assessee stated that the investment in the car was made out of the sale proceeds of an old car and business receipts. The assessee was asked to furnish evidence relating to the transfer of ownership of the old car allegedly sold during the year, capital accounts, balance sheets for assessment years 2015–16, 2016–17 and 2017–18, and justification of gross receipts shown in the return of income to support the claim.
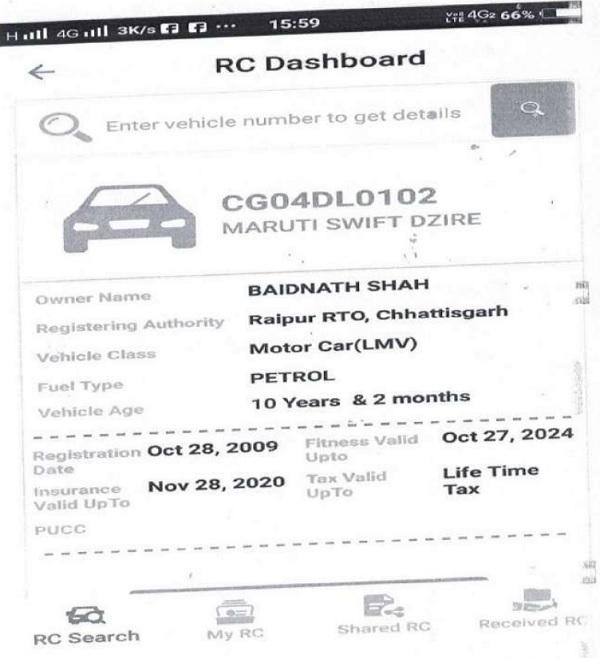
The assessee submitted documents along with written submissions. The registration certificate relating to the purchased Swift Dzire car bearing registration number CG 04 DL 0102 reflected the assessee’s name. However, verification through the Government website M-Parivahan indicated that the vehicle was registered in the name of Baidhyanath Shah.
The Assessing Officer examined the capital account furnished by the assessee and observed that profit on sale of the old car amounting to ₹1,53,375 had been recorded. However, on examining the return filed in ITR-4S for assessment year 2016–17, the Assessing Officer noted that such income had not been offered for taxation. Further discrepancies were observed in the cash balance. The capital account showed a cash balance of ₹11,78,063 as on 31.03.2016, whereas the ITR-4S filed by the assessee showed cash balance of ₹85,900.
It was also noted that during assessment year 2016–17, the assessee had filed three returns of income. The original return was filed on 28.12.2016 in ITR-4 and subsequently revised on 16.03.2017 and 13.05.2017 in ITR-4S. In that year, the assessee declared profit of ₹2,50,000 on gross receipts of ₹11,00,000. In earlier years the assessee had disclosed income in the range of 14% to 22% of gross receipts. For the year under consideration, the assessee declared income of ₹4,56,432 on gross receipts of ₹8,46,800, representing approximately 53% of gross receipts.
On the basis of these findings, the Assessing Officer concluded that the assessee had manipulated accounts and documents to support the claim that the car purchase was made out of cash in hand and business income. The explanation was treated as a concocted story to justify the cash payment for the car. Accordingly, the amount of ₹12,65,000 was treated as undisclosed investment under Section 69 of the Income Tax Act and taxed under Section 115BBE at the rate of 60%.
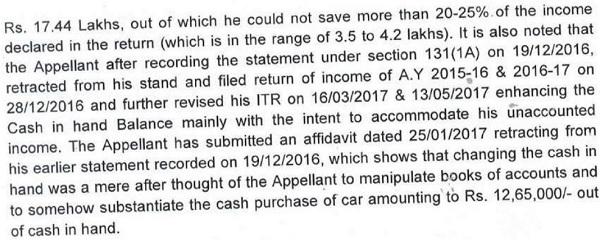
The assessee challenged the assessment before the Commissioner of Income Tax (Appeals)/NFAC. The appellate authority examined the returns filed by the assessee from assessment year 2011–12 to 2017–18 and recorded details regarding turnover, net profit, income declared and cash balances reported in various years. It was noted that returns for assessment years 2015–16 and 2016–17 were filed belatedly on 28.12.2016. It was also observed that the assessee subsequently revised the return for assessment year 2016–17 to enhance the reported cash-in-hand balance. However, the Commissioner (Appeals) upheld the findings of the Assessing Officer.
The matter was thereafter brought before the ITAT. The Tribunal examined the records and considered submissions of both parties. The Assessing Officer had doubted the sale of the old car based on the Government website and RTO documents showing the vehicle registered in the name of Baidhyanath Shah, whereas the assessee had produced documents indicating that the car was sold to Raj Kumar Tiwari.
During the hearing before the Tribunal, counsel for the assessee submitted that the discrepancy in the RTO records may have arisen because the new owner had not completed the procedure with the RTO authorities. It was argued that the assessee should not be penalised for such procedural lapse and the sale transaction should not be doubted.
The Tribunal was also informed that in the return of income the assessee had disclosed the total consideration received from sale of the car amounting to ₹3,80,000 in Schedule DPM. Further, the profit from the sale of the car amounting to ₹1,53,375 had been offered to tax in the return of income. This position was admitted by the Senior Departmental Representative.
The Tribunal observed that the sale transaction of the car had been duly recorded in the return of income and tax had already been offered on the profit arising from that transaction. Therefore, the Tribunal noted that there was no loss to the Revenue in terms of collection of taxes relating to the sale transaction.
The Tribunal also addressed the doubts raised by the Assessing Officer regarding the revised returns filed by the assessee. It noted that the Revenue authorities had not provided any evidence to establish that the revised returns were filed as an afterthought or were fabricated to justify the cash payment. Since the revised returns were valid returns filed in accordance with law and accepted by the Department, they could not be rejected without supporting evidence.
The Tribunal held that the findings of the Assessing Officer and the Commissioner (Appeals) were based merely on suspicion and not supported by corroborative material. It reiterated that tax cannot be imposed solely on the basis of suspicion in the absence of evidence.
Considering the overall facts and circumstances of the case, the Tribunal set aside the order of the Commissioner of Income Tax (Appeals)/NFAC and directed the Assessing Officer to delete the addition made under Section 69. Consequently, the appeal filed by the assessee was allowed.
FULL TEXT OF THE ORDER OF ITAT RAIPUR
The present appeal preferred by the assessee emanates from the order of the Ld.CIT(Appeals)/NFAC, dated 17.09.2025 for the assessment year 2017-18 as per the grounds of appeal on record.
2. The relevant facts in this case are as follows:
“A survey action u/s.133A of the Income Tax Act, 1961 in the case of Mahadev Cars Pvt. Ltd. During the survey proceedings, it was noticed that the assessee has purchased a car in cash during the year under consideration. Statement on oath was recorded and during statement on oath and the assessee accepted that the amount of Rs.12,65,000/-invested in purchasing of car was the undisclosed income for the year under consideration.
1. In the written submission filed by the assessee, it was submitted that the amount of investment in car is out of sale proceeds of old car and out of business receipts.
1. The assessee was asked to furnish the evidence in respect of transfer of ownership of old car said to have been sold during the year, capital account and balance sheet for asstt. year 2015-16,2016-17 and 2017-18 alongwith justification of gross receipts shown in the return of income to substantiate the claim that the purchase of car was out of sale proceeds and business receipts.
2. The assessee has filed written submission enclosing therewith the required documents. The registration certificate filed by the assessee in respect of purchase of Swift Desire Car CG 04 DL 0102 bears the name of the assessee . But on going through the Government website M Parivahan, the name of the owner is seen as “Baidhyanath Shah” in respect of vehicle in question
1. From the capital account filed by the assessee, it is observed that the profit on sale of car is shown at Rs. 1,53,375/-. However, on going through the ITR -4S filed for A.Y.2016-17 no such income was offered for taxation.
2. The capital account furnished by the assessee shows a cash balance of Rs.11,78,063/-as on 31.3.2016 whereas in the ITR 4S filed by the assessee the cash balance as on 31.3.2016 shows an amount of Rs.85,900/- only.
3. Further, during the A.Y 2016-17, the assessee has filed 3 return of income: Original return was filed on 28/12/2016 in ITR-4 which is later on revised on 16/03/2017 & 13/05/2017 in ITR-4S. The profit declared in A.Y 2016-17 is Rs.2,50,000/- on gross receipt of Rs.11,00,000/- which is around 22% of gross received. In earlier years also, assessee has disclosed income around 14 to 22% of gross receipt. The income disclosed during the year under consideration is Rs. 4,56,432/- on gross receipt of Rs.8,46,800/- which is around 53% of gross receipt.
From the above position, it is very clear that the assessee has manipulated his accounts and documents to substantiate the claim that the purchase of car was made out of his cash in hand of previous year and current year income. It is nothing but a concocted story to cover up his claim of cash payment towards purchase of car. In the given circumstances, I treat the amount of Rs.12,65,000/- as his undisclosed investment and same is added back u/s 69 of the I.T.Act, 1961. The Total Income assessed is taxed u/s 115 BBE of the Act at the rate of 60%.
Addition: Rs.12,65,000/-”
3. That on this factual scenario, the Ld. CIT(Appeals)/NFAC has held and observed as follows:
5.1.12. The Appellant has filed belated return of income (ITR-4) for A.Y 2015-16, 2016-17 on 28/12/2016 and declared total turnover of Rs. 13,50,000/- & Rs. 11,00,000/- on which taxable income of Rs. 3,06,000/- & Rs. 2,50,200/- has been offered respectively. It is further noted the cash in hand reported is Rs. Nil for A.Y 2015-16 and Rs. 85,910/- for A.Y 2016-17(After recording of Statement under oath u/s 131(1A) of the IT Act on 19/12/2016). The Appellant subsequently revised his return of income of A.Y 2016-17 on 16/03/2017 & 13/05/2017 to enhance the cash in hand balance. The gist of the returns filed from 2011-12 to 2017-18 are reproduced hereinunder:
| A.Y | Date of Filing | Type of ITR filed | Total Turnover reported | Net Profit on turnover | Total income declared | Cash in hand reported |
|---|---|---|---|---|---|---|
| 2011-12 | 28/03/2012 | ITR-1 | Nil | Nil | 1,56,000/- | Nil |
| 2012-13 | 30/03/2013 | ITR-1 | Nil | Nil | 1,74,000/- | Nil |
| 2013-14 | 05/03/2014 | ITR-1 | Nil | Nil | 1,86,000/- | Nil |
| 2014-15 | 21/03/2015 | ITR-4 | 15,00,000/- | 2,16,000/- | 2,16,000/- | Nil |
| 2015-16 | 28/12/2016 | ITR-4 | 13,50,000/- | 3,06,000/- | 3,06,000/- | Nil |
| 2016-17 | 28/12/2016 | ITR-4(Invalid Return) |
11,00,000/- | 2,50,200/- | 4,03,580/- | 85,910/- |
| 2016-17 | 16/03/2017 | ITR-4S | 11,00,000/- | 2,50,200/- | 2,50,200/- | 85,910/- |
| 2016-17 | 13/05/2017 | ITR-4S | 11,00,000/- | 2,50,200/- | 2,50,200/- | 85,910/- |
| 2017-18 | 14/08/2017 | ITR-4 | 18,45,870/- | 4,56,432/- | 4,56,932/- | 98,435/- |
| 2018-19 | 29/12/2018 | ITR-4 | 5,43,860/- | 3,29,315/- | 3,44,505/- | 1,21,780/- |
5.1.13. On perusal of the above mentioned, it is noticed that even if total income of the Appellant for the period of A.Y 2011-12 to 2017-18 is accumulated it comes to
4. I have carefully considered the facts and issues emanating in this case, heard the submissions of the parties herein. The A.O had doubted the sale of old car by referring to the government website and RTO documents, wherein the vehicle was registered in the name of Baidhyanath Shah, whereas the assessee had submitted document showing that vehicle was sold to Raj Kumar Tiwari. That answering this discrepancy, at the time of hearing, the Ld. Counsel for the assessee submitted that the new owner may not have properly completed the procedure in RTO office, for which, the assessee should not be penalized or that the sale transaction should not be doubted. The Ld. Counsel also brought to the notice of the Bench that the assessee had in his return of income in ‘Schedule DPM’ at ‘Sr. No.8’ disclosed the total consideration received during the year from sale of the car at Rs.3,80,000/-. Similarly, the tax has been offered at Rs.1,53,375/- at ‘Column No.16’ in the return of income. Therefore, the assessee had demonstrated that there was no loss to the Revenue in terms with collection of taxes as regards the sale transaction of the car and that the entire sale transaction has been duly recorded for in the return of income and had already been offered to tax. This fact was admitted by the Ld. Sr. DR.
5. The A.O had also doubted the various revised returns that were filed by the assessee and the same findings were upheld by the Ld. CIT(Appeals) /NFAC. However, the Revenue had failed to point out why they have stated that such filing of revised returns are an afterthought and concocted story to cover up the claim of cash payment since all the revised returns filed were valid returns as per law and the Revenue had also not brought on record any evidence to corroborate the findings of the A.O or the Ld. CIT(Appeals)/NFAC that such revised returns filed were nothing but to cover up the cash payments and a concocted story. That in absence of any adverse material on record, the valid revised returns which has been accepted by the Department could not be questioned and the findings of the Revenue authorities are merely based on suspicion. There cannot be any tax imposed only on the basis of suspicion in absence of corroborative evidences.
6. Considering the totality of the facts, I set aside the order of the Ld. CIT(Appeals)/NFAC and direct the A.O to delete the additions from the hands of the assessee while providing appeal effect of this order.
7. As per the above terms, grounds of appeal of the assessee are allowed.
8. In the result, appeal of the assessee is allowed.
Order pronounced in open court on 12th day of March, 2026.




