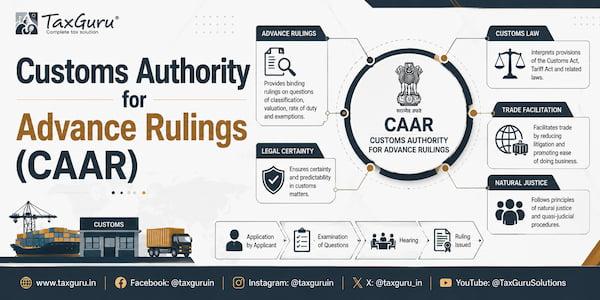
In re Sanmina-SCI India Private Limited (CAAR Mumbai)
The Customs Authority for Advance Rulings, Mumbai, examined an application by Sanmina-SCI India Private Limited concerning the customs classification of five storage server models and the eligibility of imported manufacturing inputs for exemption from Basic Customs Duty under Serial No. 39 read with Serial No. 8 of Notification No. 24/2005-Customs dated 01.03.2005.
The applicant proposed classification of all five models under CTH 8471 70 90 as other storage units. The jurisdictional Commissionerate distinguished passive JBOD storage enclosures from servers having independent computing capabilities.
The Authority classified Crestone Model-1 and Crestone Model-2 under CTH 8471 70 90, while La Jolla, Coronado and Mlk Mavericks were classified under CTH 8471 50 00 as processing units. All five models consequently fell within Heading 8471.
The Authority further held that imported goods actually used to manufacture these storage servers could qualify for the Nil rate of Basic Customs Duty under Serial No. 39, subject to the specified exclusions and compliance with the IGCR Rules, 2022. Goods falling under Chapter 74 and specified solar tempered glass are excluded. The exemption does not extend to integrated tax or other duties outside the First Schedule.
The ruling does not determine the classification of individual imported inputs. Their classification remains subject to assessment, and any material change in the configurations described in the application may affect the ruling’s applicability.
Want to Read the Complete Judgment?
You have read the free case summary. Unlock the full judgment, the detailed judicial reasoning and the downloadable PDF, along with every other premium judgment on TaxGuru.
Already subscribed? Log in
One subscription covers the entire premium judgment library, not just this case.