
Sanjay Jain Vs Enforcement Directorate (Delhi High Court)
In the case of Sanjay Jain vs. Enforcement Directorate (Delhi High Court), the court considered various factors before granting bail to the petitioner. The ruling took into account precedents, the completion of investigation, absence of incriminating evidence, and the petitioner’s background.
Non-Arrest of Co-Accused: Relevant Factor for Bail: The court emphasized that the non-arrest of co-accused is a relevant factor in bail considerations. Citing judgments from previous cases, including Dr. Bindu Rana vs. Serious Fraud Investigation Office and Ramesh Manglani vs. ED, the court highlighted the significance of this factor in the bail decision-making process.
Completion of Investigation and Lack of Incriminating Evidence: The court noted that the investigation against the petitioner was complete, and no incriminating material was recovered from him. Despite searches conducted by multiple agencies, no evidence supporting the respondent’s claims was found. Additionally, the petitioner had cooperated with the investigation on multiple occasions.
Conditions for Bail: After considering the petitioner’s background, travel history, and criminal record, the court granted regular bail. Various conditions were imposed, including restrictions on leaving the country, appearing before the court, joining the investigation when directed, and refraining from criminal activities or tampering with evidence.
Conclusion: The Delhi High Court’s ruling in the Sanjay Jain bail case underscores the importance of considering multiple factors in bail decisions. Precedents and legal principles regarding the non-arrest of co-accused, completion of investigation, and absence of incriminating evidence played a crucial role in the court’s decision-making process.
FULL TEXT OF THE JUDGMENT/ORDER OF DELHI HIGH COURT
1. The present petition has been filed under Section 45 of the Prevention of Money Laundering Act, 2002 read with Section 439 of the Code of Criminal Procedure, 1973 seeking regular bail in connection with ECIR No. DLZO-I/43/2021 dated 20.05.2021 registered by the respondent/ED.
FACTS
2. The Enforcement Case Information Report (hereinafter referred to as ‘ECIR’) was registered against the petitioner and others on the basis of FIR No. RC221/2021/E0009 dated 17.05.2021 registered by the CBI under Sections 120B read with 420 IPC and Sections 13(2) read with 13(1)(d) of the PC Act, 1988.
3. The summary of the allegations contained in the FIR registered by the CBI are as follows: –
a. Two complaints were forwarded to the CBI against the MD, Indian Farmers Fertilizer Cooperative Limited (hereinafter referred to as ‘IFFCO’) relating to subsidy fraud in IFFCO by opening Kisan International Trading, exchange of illegal commissions in import of raw materials and fertilizers, manipulation of sales data of fertilizers for claiming higher subsidy etc.
b. During scrutiny and verification of the complaints by the CBI, specific inputs were received from reliable sources alleging serious irregularities committed by the MD, IFFCO and other board members of IFFCO as well as MD, Indian Potash Limited (hereinafter referred to as „IPL‟) and others resulting in huge losses to both the entities and undue pecuniary gain to them and their family members.
c. It is alleged that the accused persons including the petitioner entered into a criminal conspiracy amongst themselves and during the period from 2007-2014 cheated and defrauded IFFCO, IPL, the general shareholders of these entities, as well as, the Government of India by fraudulently importing fertilizers and other materials at inflated prices and claimed higher subsidy thereby causing loss to the public exchequer. It is alleged that the commission from the supplies was siphoned off and the same was done through a complex web of fake commercial transactions through multiple companies which were owned by the accused persons to camouflage the fraudulent transactions as genuine.
d. It is the case of the respondent that IFFCO set up its 100% subsidiary namely, M/s Kisan International Trading FZE in Jebel Ali, Free Zonal Dubai for importing fertilizers and other raw materials from foreign companies/firms. It is alleged that the modus operandi adopted by the accused persons was that original bills were raised by the foreign manufacturers/suppliers (M/s Uralkali Trading Ltd.) at inflated prices to cover the bribe money which was to be paid to the Managing Directors of IFFCO and IPL. It is further alleged that incentives were paid through intermediaries/hawala
e. The commission was received by the sons of the Managing Directors of IFFCO and IPL, respectively through an individual, namely Rajeev Saxena, who in order to justify the receipt of commission from M/s Urakali Trading Ltd. (hereinafter also referred to as “Uralkali”) would execute consultancy agreements without rendering any consultancy services. Subsequently, the commission so received by Rajeev Saxena was transferred by him to the sons of the Managing Directors of IFFCO and IPL as per the instructions of the middleman Pankaj Jain by again executing consultancy agreements with the companies of the sons of the Managing Directors of IFFCO and IPL, respectively without rendering any consultancy services.
f. The specific allegation against the petitioner is that he along with the co-accused acted as intermediaries who channelized the ill-gotten money through various firms and companies registered either in their names or in the names of the sons of the Managing Directors of IFFCO and IPL. It is further alleged that the petitioner along with other co-accused are the owners/key persons of Rare Earth Group and M/s Jyoti Trading Corporation, Dubai which imports fertilizer products on a very large scale.
g. It was further revealed that out of the total illegal commission, an amount of USD 80.18 million (Rs. 481 Crores approx.) was channelized through Rare Earth Group and the remaining amount of USD 34.40 million (Rs. 204 Crores approx.) has been received by the sons of the Managing Directors of IFFCO and IPL either in the accounts of the firms/companies owned by them or in cash.
h. It also transpired that Rare Earth Group Commodities, DMCC (beneficially owned by Pankaj Jain) supplied a large quantity of Rock Phosphate to IFFCO during the period 2007-11 directly or through Kisan Trading It was further revealed that the company of Pankaj Jain namely, Ferttrade DMCC also supplied fertilizers to IFFCO from 2012 onwards. Trans Globe DMCC, a company of Pankaj Jain also supplied fertilizers to IFFCO. Rare Earth Commodities DMCC and Trans Globe DMCC also supplied fertilizers to IPL.
4. In a nutshell, as per the case of the respondent, the petitioner herein has received the proceeds of crime through two routes which are as follows:
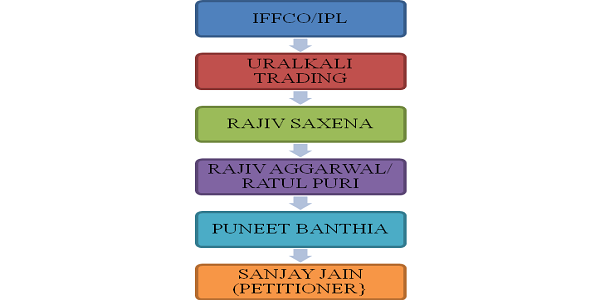
Direct Route/Ratul Puri Route – Under this route, Rajeev Saxena would receive proceeds of crime from Uralkali, then he would pay cash to the petitioner through one Rajiv Aggarwal (an associate of Mr. Ratul Puri). One Punit Banthia used to pick up cash from Rajiv Aggarwal on behalf of the Petitioner. The Direct Route could be depicted by the following flow chart:
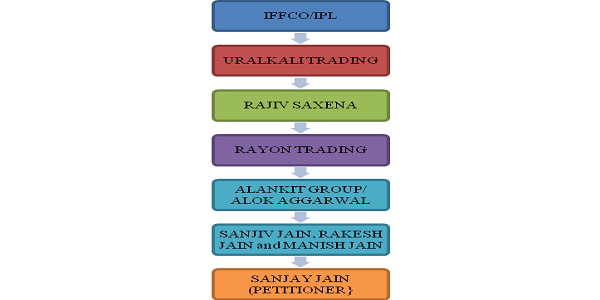
Indirect Route/Rayon Trading Route – Under this route, Rajeev Saxena after receiving the proceeds of crime would send money through an entity called Rayon Trading to the Alankit group of companies. Alankit group of companies (owned by Alok Aggarwal and Ankit Aggarwal) in turn made payments to the petitioner. The money used to be handled by Sunil Kumar Gupta and Mahesh Upadhyay and given to various persons on behalf of the petitioner.
SUBMISSIONS ON BEHALF OF THE PETITIONER
5. Mr. Dayan Krishnan, learned Senior Counsel appearing for the petitioner at the outset submits that in order to initiate an investigation and subsequent prosecution under the Prevention of Money Laundering Act, 2002 [in short “the PMLA”] there should be a commission of a scheduled offence and there should be generation of proceeds of crime from such scheduled offence. The person sought to be prosecuted should be directly or indirectly involved in any process or activity connected with the said proceeds of crime and the money trail shall remain unbroken for curtailing the personal liberty of the accused.
6. Krishnan further submits that the predicate offence under the Act should also hold good i.e. hold authority under the law, which is based on cogent material that would lead to a reasonable inference that the accused would be convicted of the predicate offence. If the predicate offence is weak, the same shall enure in favor of the petitioner.
CBI LACKS THE REQUISITE JURISDICTION TO REGISTER THE FIR UNDER THE PROVISIONS OF PREVENTION OF CORRUPTION ACT, 1988
7. The learned Senior Counsel has drawn the attention of the Court to Annexure P-2, the RC221/2021/E0009 dated 17.05.2021 registered by the CBI under Sections 120B r/w 420 IPC and Sections 13(2) r/w 13(1)(d) of the PC Act, 1988, to submit that although the RC was registered by the CBI under the provisions of the Prevention of Corruption Act, but at the relevant time i.e. at the time of import from 2007-2014, neither IFFCO nor IPL was a public company, rather they have been private companies/entities since the year 2000. In this regard, the learned Senior Counsel referred to letters dated 21.08.2017 and 05.09.2018 of the CBI (annexed as Annexure P-13 to the paper book) wherein the CBI has already taken a categorical stand that CBI has no jurisdiction over Indian Potash Limited since it is not a public authority. The letter dated 21.08.2017 reads as under:
No. 179/CO AC 1 2016 A 0009
O/o Supdt. of Police
Central Bureau of Investigation
Anti Corruption –I
B-5 CBI Hqrs., 8th Floor
CGO Complex, Lodhi Road
New Delhi 110003
Tele-fax:-011-24360361
Dated:21.8.2017
To
Sh.Kulwant Rana,
Under Secretary to the Govt. of India,
Ministry of Chemicals & Fertilizers,
Department of Frtilizers,
Shastri Bhawan, New Delhi.
Sub: Irregularities in import of fertilizers –regarding
Sir,
Kindly, refer your office letter F.No.16/4/14-Vig (L.S) dated 12.07.2017 on caption mentioned above.
In this regard, it is informed that the competent authority of CBI has closed this complaint because CBI has no jurisdiction over Indian Potash Limited which at present is not a public authority.
For information please.
Sd/-(Rajiv Ranjan) Supdt. of Police CBI/AC-I/New Delhi.
8. To the same effect is the letter dated 05.09.2018 written by the CBI to the Member of Parliament, which reads as under:
No. 274/CO AC 1 2016 A 0009
O/o Supdt. of Police
Central Bureau of Investigation
Anti Corruption –I B-5 CBI Hqrs., 8th Floor
CGO Complex, Lodhi Road
New Delhi 110003
Tele-fax:-011-24360361
Dated:5.9.2018
To
Dr. Arun Kumar,
Hon‘ble Member of Parliament,
(Lok Sabha),
171-172, South Avenue,
New Delhi.
Sub: Legal Notice for Filing Public Interest Litigation Against Scam in import of Fertilizers By Indian Potash Limited on Government Account-regarding.
Sir,
Kindly refer to your letter dated 08.08.2018.
It is to inform that allegations/complaint mentioned in your letter was already analyzed by the CBI. It is found that CBI has no jurisdiction over Indian Potash Limited since it is not a public authority.
Hence, complaint was closed by the CBI after taking approval from the competent authority.
Thanking You
Supdt. of Police
CBI/AC-I/New Delhi.
9. Further referring to the RC, the learned Senior Counsel submits that the said RC was registered on the basis of two complaints dated 14.06.2016 and 05.09.2016, whereas, on the other hand, the CBI in the year 2017 as well as in 2018 had already taken a stand that it does not possess jurisdiction over IPL. According to the learned Senior Counsel, this contradiction, as well as, the delay in registration of FIR makes it highly improbable that the petitioner would be convicted in the predicate offence.
10. In addition to the aforesaid, Mr Krishnan submits that the co-accused in the present matter i.e. the Managing Directors of IPL and IFFCO have approached this Court by filing WP(C) 1051/2021 and WP(C) 1052/2021, respectively, challenging the registration of RC by the CBI and vide common order dated 31.05.2021 this Court has been pleased to direct that no coercive steps shall be taken against them. The relevant paragraph of the order dated 31.05.2021 reads as under:
“7. Till further orders, no coercive steps shall be taken against the petitioners, however, they shall join investigation as and when called by SHO/IO.“
ANOMALIES IN THE CASE OF THE RESPONDENT IN THE INDIRECT ROUTE/COMMISSION THROUGH RAYON TRADING
11. The submission of the learned Senior Counsel in respect of the indirect route is that in the said route the chain remains inconclusive and suffers from various material irregularities at each leg of this route / money trail, which are enumerated below:
a. IFFCO and IPL have paid Uralkali for fertilizers at inflated prices to cover the commission amount which was subsequently received by the accused persons –
i. It is the submission of the learned Senior Counsel that the respondent has failed to produce any evidence showing payment of inflated prices by IFFCO and IPL. For this purpose, the attention of the Court was drawn to Annexure P-10, the Office Memorandum dated 23.07.2012 issued by the Ministry of Chemicals and Fertilizers in response to a letter written by the Directorate of Enforcement dated 24.02.2012, to submit that the Ministry of Chemicals and Fertilizers has in unequivocal terms dismissed allegations of any wrongdoing on part of IFFCO.
ii. He submits that the said memorandum states that up till the year 2010, the subsidy which an entity was entitled to claim was subject to the weighted average price of the entire industry or based on the price of import by an entity, whichever was lower.
iii. He submits that after 01.04.2010 the subsidy which was payable on imports was directly linked to the percentage of the chemical component in the fertilizer and not the import price thereof. This makes the case of the prosecution doubtful as the subsidy payable was not dependent upon the price of the import or the industry average.
b. Once the money for commission was received by Uralkali Trading, the money was transferred to Rajeev Saxena which was done by creating forged and fabricated consultancy agreements
i. Mr Siddharth Aggarwal, the learned Senior Counsel, who also appeared on behalf of the petitioner, submits that the sole incriminating material collected by the respondent in this regard are the statements of Rajeev Saxena, which are unreliable given the inherent contradictions. He submits that Rajeev Saxena is not reliable as a witness, inasmuch as, it is the respondent’s own case that Rajeev Saxena is guilty of withholding, providing partial documents, as well as, forging documents. To buttress his contention, the attention of the Court is invited to an application under Section 306 CrPC filed by the respondent/ED seeking revocation of tender of pardon granted to Rajeev Saxena in another case titled “The Directorate of Enforcement v. Gautam Khaitan and Ors.”.
ii. He submits that with respect to the statement of Rajeev Saxena, no person from Uralkali has been examined by the respondent/ED to the effect that the money which has been received by Rajeev Saxena was against those very shipments which were imported by IPL/IFFCO. Further, Rajeev Saxena has taken different stands before different investigating agencies, in respect of the above transaction.
iii. It is also contended that Rajeev Saxena is also a co-accused in the present matter and the statement of the co-accused being a weak piece of evidence cannot be used by the prosecution to deny the benefit of bail to the petitioner.
iv. He further submits that the respondent has failed to establish a link between the petitioner and Rajeev Saxena, in as much as there is no record to show any communication between them. Further, the prosecution complaints are based entirely on the unsubstantiated false statements and internal records of Rajeev Saxena (co-accused), thus, the veracity of the allegations against the petitioner is doubtful.
c. Thereafter, the money was transferred to Rayon Trading by Rajeev Saxena –
i. Mr Aggarwal submits that no proof of payment of money in the form of bank account statements has been placed on record by the ED to show any transaction between the entities of Rajeev Saxena and Rayon Trading. He submits that reliance in this regard has been placed by the respondent solely on plain paper (excel sheet) entries and the said document is not a contemporaneous record and has been prepared for investigating agencies. Further, the said document submitted by Rajeev Saxena is not a ledger maintained during the course of business and cannot pass the test of Section 34 of the Indian Evidence Act, 1872.
d. Once the money was received by Rayon Trading, the same was transferred to Alankit Group/ Alok Aggarwal –
i. Mr. Aggarwal submits that the purpose of payment between Rayon Trading and Alankit Group/Alok Agarwal has not been established as the transactions between the two entities have been explained by Alok Agarwal as genuine in his statement dated 28.11.2022 under Section 50 of the PMLA. The relevant part of the said statement reads as under:
”Q.5 Please explain the transactions figuring in the Ledger account of Rayon General Trading LLC in the books of M/s Alankit Global Resources DMCC as submitted by Sh. Ankit Agarwal vide his statement dated 24.11.2022?
Ans 5. These transactions pertain to the consultancy services provided by Alankit Global Resources DMCC to Rayon General Trading LLC. I do not remember the details thereof, however, I undertake to provide the same along with supporting documents by 30.11.2022.
Premised on the above statement the learned Senior Counsel submits that the statement of Alok Agarwal under Section 50 PMLA has to be read in favor of the petitioner.
e. Thereafter, the proceeds of crime have been transferred by Alankit Group to the petitioner
i. Mr Aggarwal submits that to prove the transfer of money by Alankit Group to the petitioner, the respondent/ED has relied entirely on the personal ledgers of Sunil Kumar Gupta and contrary to law, Section 22 of the PMLA has been invoked to read this ledger against the petitioner. Further, it is submitted that Sunil Kumar Gupta has admitted that he has no knowledge of whether these payments were actually made and has admitted to merely noting the entries on the directions of Alok Agarwal and Ankit Agarwal and thus his statement is at best hearsay.
ii. In respect of the cash transactions, it is submitted that each of the persons who have alleged to have received cash from Alankit Group on the petitioner‟s behalf, has denied this fact in their statements under Section 50 of the PMLA and thus must be read in favour of the petitioner. Reference in this regard is made to the statements of Rakesh Jain, Sanjeev Jain, Rahul Mittal, Manish Jain and Sharad Jain.
iii. In respect of the RTGS/Cheque transactions in the personal ledger of Sunil Kumar Gupta, it is submitted that the said transactions are legitimate and have been fully disclosed in accordance with law, on which applicable tax has been paid.
ANOMALIES IN THE CASE OF THE RESPONDENT IN THE DIRECT ROUTE
12. It may be noticed that the first two steps i.e. steps at sub paras (a) and (b) in para 11 above, insofar as payment from IFFCO/IPL to Uralkali and then from Uralkali to Rajeev Saxena, are concerned, the same are common in both the routes, therefore, the submissions apropos the said two steps in the indirect route are same in the direct route, therefore, they are not being repeated for the sake of brevity.
13. The submission of the learned senior counsel in respect of the direct route is that even in the said route there are numerous breaks in the money trail, and such breaks at each step are enumerated below:
a. the proceeds of crime from Rajeev Saxena came to the hands of Ratul Puri and his employee, Rajiv Agarwal
i. The learned Senior Counsel for the petitioner submits that neither Ratul Puri nor his employee Rajeev Aggarwal have supported the case of the prosecution. Reliance in this regard is placed on the statement of Ratul Puri recorded on 20.10.2022 under Section 50 of the PMLA, the relevant part of the statement reads as under:
”Q1. Was any cash delivered to you by Sh. Sanjay Jain through Sh. Rajeev Agarwal?
Ans.1. No, I do not who Sh. Sanjay Jain is.
Q2. Did Sh. Rajeev Saxena give any corresponding credit entries to you or your companies abroad in lieu of cash delivered by you to Sh. Sanjay Jain though Sh. Rajeev Agarwal?
Ans. 2. No.
Q3 You are being shown statement dated 11.06.2021 of Sh. Rajeev Saxena running into 74 pages. Please go through it and comment as far as it pertains to you?
Ans.3. l have seen and read statement dated 11.06.2021 of Sh. Rajeev Saxena running into 74 pages. l have put my dated signatures on all the 74 pages as a token of having read the same. I state that I strongly deny the statemenT made by Sh. Rajiv Saxena. I have no such account with him which he has enumerated in excel spreadsheets. My company’s business dealings were limited to sourcing of Solar panels.
Q.4 Please refer to Question number 15 of statement dated 03.07.2019 tendered before Income Tax Authorities and accepted vide his statement dated 11.06.2021 under section 50 of PMLA, 2002 of Sh. Rajeev Saxena, wherein he has referred to payment of Rs. 5 crores and 1 crores to Sh. Pankaj Jain on 15.01.2014 and 19.08.2013 respectively through you. Do you know Sh. Pankaj Jain and comment on the nature of these transactions?
Ans. 4. I do not know Sh. Pankaj Jain and no such transactions were undertaken. I strongly deny the statement made by Sh. Rajiv Saxena.
Q5 Please refer to Question number 28 of statement dated 03.07.2019 tendered before Income Tax Authorities and accepted vide his statement dated 11.06.2021 under section 50 of PMLA, 2002 of Sh. Rajeev Saxena, wherein he has referred to payments of various amounts through you as detailed under:
a. Rs. I crores to Sh. Sanjay Jain on 16.01.2011
b. Rs. 3 crores to Mr. Amarendra Dhari Singh on 20.07.2011
c. Rs. 2 crores to Mr. Reddy on 14.12.2011
d. Rs. 1.5 crores to Sh. Sanjay Jain on 14.12.2011
e. Rs. 0.75 crores to Sh. Sanjay Jain on 20.12.2011
f. Rs. 1 crore to Sh. Sanjay Jain on 08.02.2016
g. Rs. 1 crore to Sh. Sandeep Khanna on 07.08.2016
Please explain the source of money given by you to these persons.
Ans. 5. No money was given by me to these persons and I strongly deny the statement made by Sh. Rajiv Saxena.
I request that my further statement may be recorded on 21.l 0.2022.
I undertake to appear on 28.10.2022 at 1500 hours.
The above statement of mine running into two pages has been tendered voluntarily on my own without any fear, pressure, force, coercion, threat or inducement and the same is true and correct to the best of my knowledge and belief. It has been typed on a computer at my request.‖
ii. Mr Aggarwal contends that to a similar effect is the statement of Rajiv Aggarwal recorded under Section 50 of the PMLA on 14.10.2022, the relevant part of which reads as under:
”Q.1 Have you ever interacted with Rajiv Saxena in relation to payment of cash in India to Sanjay Jain brother of Pankaj Jain of Dubai?
Ans.1 No.
Q.2 Have you ever interacted with Pankaj Jain or Sanjay Jain in any matter?
Ans.2 No, I do not know these persons at all. I have never met them or interacted with them in any matter at all.
Q.3 Have you ever had any telephone conversations with these two persons?
Ans.3 No.
Q4. Were you having phone numbers of these two persons?
Ans.4 No. I was not having phone numbers of these two persons.
Q.5 Have you ever interacted with Puneet Banthia or Puneet in India for payment of cash in India?
Ans.5 No.
Q.6 Have you ever interacted with Puneet Banthia or Puneet in India for any other matter?
Ans. No.
Q.7 Have you ever had telephonic conversation with Puneet Banthia or Puneet?
Ans. No.
Q.8 Were you having phone numbers of Puneet Banthia or Puneet?
Ans.8 It was there in my telephone diary but I never interacted with him.
Q.9 Who gave you his phone number?
Ans.9 I do not remember.
Q.10 In what connection were you having his phone number?
Ans.10 I do not remember.
Q.11 How do you know him?
Ans. I do not know him.
Q.12 If you do not know him why were you having the phone number of a complete stranger in your telephone diary?
Ans.12 I do not remember in what context anybody has given his number to me. But as per my memory, I have never met him or interacted with him in any manner.
I request that my further statement may be recorded on 18.10.2022. I undertake to present myself at 1530 hours on 18.10.2022 to continue my further statement.
The above statement of mine running into two pages has been tendered voluntarily on my own without any fear, pressure, force, coercion, threat or inducement and the same is true and correct to the best of my knowledge and belief.
iii. He further submits that the statement of Rajeev Saxena would not be admissible as the same is hearsay as he has admitted that he did not coordinate the delivery of cash, which has been allegedly received by the petitioner. For this purpose, the learned Senior Counsel relied upon the statement of Rajiv Saxena recorded under Section 132(4) of the Income Tax Act, 1961, the relevant part of which reads as under:
“Q.19. How did you coordinate the transfer of cash without having any contact person in Delhi/India?
Ans. I was not coordinating the cash. The coordination was done by Rajeev Agarwal with the representative of Mr. Sanjay Jain i.e., Mr. Puneet.‖…
iv. Elaborating further, the learned Senior Counsel submits that according to Rajeev Saxena, it was Shahnawaz Khan, his employee, who was handling cash on his behalf. However, it stated by Shahnawaz Khan that he had no knowledge of the parties on whose behalf cash transfers were being carried out. The relevant part of Shahnawaz‟s statement dated 18.10.2021 under Section 50 of the PMLA reads as under:
“Q.15 Give the normal day to day work handled by you while you were working for Mr. Rajiv Saxena.
Ans. …. On being asked I stated that the party on whose behalf these transfer were being carried out was not know to me…‖
v. It is fairly submitted by Mr Aggarwal, learned Senior Counsel that only one person namely, Puneet Banthia in his statements recorded on 24.09.2021 and 10.10.2022 has supported the case of the prosecution to the effect that he (Puneet Banthia) carried cash from Ratul Puri to the petitioner. He, however, adds that the statement of Puneet Banthia is contradictory to his earlier statement given to Income Tax Authorities in 2019. Further, no figure/amount has been disclosed by Puneet Banthia and that the said transaction (of carrying cash) is of the year 2016, whereas, the ledgers recovered from Rajeev Saxena are only up till the year 2014. This according to Mr. Aggarwal shows that if any cash was carried by Puneet Banthia to the petitioner, the same has no connection with the transactions with Uralkali.
BAIL ON THE GROUND OF PARITY
14. Mr Aggarwal, the learned Senior Counsel for the petitioner submits that the petitioner is also entitled to be enlarged on bail in view of the fact that all the accused persons named in the first complaint dated 30.07.2021 and summoned by the Ld. Special Judge have already been enlarged on bail. The details of the said accused are as follows:





