
In re Adhav Packs Private Limited (GST AAR Tamil Nadu)
Summary: Adhav Packs Private Limited manufactures and supplies paper bags and carry bags to retailers for packaging and carrying goods sold to consumers. It was classifying the goods as “other sacks and bags” under HSN 4819 40 and charging 18% GST under Entry 185 of Schedule II to Notification No. 09/2025–Central Tax (Rate) dated 17 September 2025. It asked whether its kraft paper bags and its carry bags made of uncoated paper or paperboard could instead be classified under HSN 4819 20 and attract 5% GST under Entry 322 of Schedule I.
The Tamil Nadu Authority for Advance Ruling admitted both questions under Section 97(2)(a) and (b) of the CGST and TNGST Acts. At the personal hearing on 18 August 2026 and in additional submissions dated 4 September 2026, the applicant described its products and supplied a catalogue. The Authority examined greaseproof pouches, V-bottom cut bags, sheet-fed self-opening satchels without handles, and regular and luxury carry bags with handles. It noted that the applicant claimed the paper was biodegradable and acknowledged that some materials used in the products contained non-biodegradable content.
The Authority held that Heading 4819 covers paper bags as well as other paper and paperboard packing containers. Within that heading, HSN 4819 10 covers cartons, boxes and cases of corrugated paper or paperboard, and HSN 4819 20 covers folding cartons, boxes and cases of non-corrugated paper or paperboard. Referring to the tariff notes and the ordinary meanings of those terms, the Authority distinguished a bag as a flexible container with an opening at the top. It therefore held that both categories of paper bags fell outside HSN 4819 20 and were ineligible for the 5% rate under Entry 322, which covers cartons, boxes and cases.
The applicant also cited divergent Gujarat and Rajasthan advance rulings on paper bags under HSN 4819 40 00. The Tamil Nadu AAR found that those rulings had no direct bearing because the application asked specifically about HSN 4819 20 and Entry 322. The operative ruling is confined to those questions.
Cases Discussed
- RAJ/AAR/2025-26/16, dated 17 December 2025 — In re SGS Packaging Private Limited (GST AAR Rajasthan). The Rajasthan AAR held that the applicant’s paper bags attracted 18% GST. Adhav Packs cited the ruling, and the Tamil Nadu AAR found it had no direct bearing on the questions under Entry 322.
- GUJ/GAAR/R/2026/24, dated 3 July 2026 — In re Canpac Trends Private Limited (GST AAR Gujarat). The Gujarat AAR held that paper bags under tariff item 4819 40 00 attracted 5% GST under Entry 319. The Tamil Nadu AAR found that ruling had no direct bearing on the questions under Entry 322.
Alternative SEO Titles
1. Kraft Paper Carry Bags Fall Outside HSN 4819 20: Tamil Nadu AAR
2. Uncoated Paper Carry Bags Excluded From 5% GST Under Entry 322: Tamil Nadu AAR
3. Paper Bags Do Not Qualify as Folding Cartons Under HSN 4819 20: Tamil Nadu AAR
4. Biodegradable Kraft Paper Bags Do Not Qualify for Entry 322 GST Rate: Tamil Nadu AAR
5. Tamil Nadu AAR Rejects HSN 4819 20 Classification for Paper Retail Carry Bags
FULL TEXT OF THE ORDER OF THE AUTHORITY FOR ADVANCE RULING, TAMIL NADU
M/s Adhav Packs Private Limited, having place of business at Madathukulam, No. 2/319, Survey No. 573/3, Palani Taluk, Midapadi, Dindigul, Tamil Nadu, 624618 (hereinafter called as the ‘Applicant’) is registered under the Goods and Service Tax Act, with GSTIN 33AATCA3755C1ZQ. They have filed an application for Advance Ruling under Sec.97 of the CGST Act, 2017 and the corresponding provision of the TNGST Act, 2017. The Applicant has made the payment of Rs.10,000/- towards application fees, under sub rule (1) of Rule 104 of CGST Rules, 2017 and TNGST Rules, 2017.
2. Statement of relevant facts having a bearing on the questions raised.
The Applicant states that they are engaged in the business of manufacturing and supply of paper bags and paper carry bags, primarily intended for use as packing material.
It has been stated that the paper bags manufactured by the applicant,
- Are produced from kraft paper/paper board;
- Are biodegradable;
- Are designed and supplied for exclusive use as packaging material or carry bags;
- Are exclusively supplied to retailers of goods, who in turn provide the same to the ultimate customers for carrying goods sold to them.
It has been stated by the applicant that the said goods are currently being classified by them under HSN 4819 40 under the description — ‘Other Sacks and bags’, taxable at 18% GST under the entry 185 of Schedule II of Notification 9/2025-CT (R) dated 17.09.2025; That, however, they seek to know, whether the paper carry bags manufactured using kraft paper/uncoated paper and paperboard, which are biodegradable and supplied to retailers for use exclusively as packaging material and as carry bags for goods sold to ultimate customers, are classifiable under HSN 4819 20 and covered under Entry 322 of Schedule I of Notification 9/2025-CT (R) dated 17.09.2025.
3. The applicant has therefore, sought an Advance Ruling, under Sec.97(2)(a) and (b) of the CGST Act, 2017, on the following questions:
1. Classification and Rate of tax & applicability of Notification — Whether paper bags /paper carry bags manufactured using Kraft Paper, which are biodegradable and supplied to retailers for use exclusively as packaging material and carry bags for goods sold to ultimate consumers, are classifiable under the HSN 4819 20 and covered under Entry 322 of Schedule-I of Notification No. 09/2025 – Central Tax (Rate) dated 17.09.2025?
2. Classification and Rate of tax & applicability of Notification — Whether paper carry bags manufactured using uncoated paper and paper board, which are supplied to retailers for use of packaging or carry bags for goods sold by them to customers, be classified under HSN 4819 20 which is taxable @ 5% and covered under entry 322 of Schedule I of Notification 9/2025-CT (R) dated 17.09.2025?
4. Applicant’s interpretation of law:
The Applicant interprets their proposed classification on the following basis:
a. Classification of the goods:
-
- The paper bags and paper carry bags manufactured and supplied by the applicant are classifiable under HSN 481920, which covers:
“Cartons, boxes and cases of :
• Corrugated paper or paper board or
• Non- corrugated paper” - Goods falling under HSN 481920, as per entry 322 of Schedule I of the Notification 9/2025-CT (R) dated 17.09.2025 attracts GST @ 5%.
- At present, paper bags and carry bags dealt by the applicant is classified under HSN 481940 and taxed at 18% under entry 185 of Schedule II of Notification 9/2025- CT (R) dated 17.09.2025;
- The paper bags and paper carry bags manufactured and supplied by the applicant are classifiable under HSN 481920, which covers:
b. Applicable GST Tariff:
1. The GST tariff rate for cartons, boxes , cases of corrugated paper or paper board or non-corrugated paper, classifiable under HSN 481920, is 5% as per entry 322 of Schedule I of Notification 9/2025- CT (R) dated 17.09.2025;
2. The ruling is sought for as to whether paper bags/ paper carry bags made of uncoated paper and paper board, which are biodegradable and penultimately used exclusively as packing should also attract the same rate of 5% GST under 481920, instead of 18%.
5. The applicant is under the administrative control of State. The concerned authorities of the Centre and State were addressed to report if there are any pending proceedings against the applicant on the issues raised by the applicant in the ARA application and for comments on the issues raised. Since no communication has been received from the jurisdictional Assistant Commissioner-State/Centre, it is presumed that there are no pending proceedings against the applicant on the issues raised by the applicant in the Advance Ruling application.
6. Personal Hearing
The applicant was given an opportunity to be heard in person on 18.08.2026. Ms. Deepa Praveen, Chartered Accountant, appeared for the personal hearing as the authorized representative (AR) of M/s. Adhav Packs Private Limited. She submitted that the applicant manufactures paper bags and paper carry bags, primarily for use as packing material; That such bags produced by the applicant are made of kraft paper/paper board, are biodegradable and designed exclusively for the use as packing material or carry bags; That the supply of such bags were made to retailer of goods, who provide the same to the ultimate customer.
The AR further stated that, at present, the applicant classified their product under HSN 481940 attracting GST @ 18% under S.No. 185 of Schedule II of Notfn. 9/2025-CT (R), as amended and sought a ruling on whether the same can be classified under 481920 and be covered by the entry 322 of Schedule I of Notification 9/2025-CT (R), attracting 5% GST.
Additional submissions:
The applicant filed additional submissions vide their mail dated 04.09.2026, enclosing a catalogue of their products with a brief write up. (captured below)
They state that the paper bags are manufactured using paper (virgin, recyclable and/or biodegradable grade) as the base material, with water-based/food-grade ink and gum and do not contain any plastic lamination, plastic coating or plastic film. The foiling, lamination, CV coating, embossing and knurling finishes for the luxury paper bag with handles, are done with materials that contain non-biodegradable content to a small extent.
The catalogue categorizes the products based on their functional deployment/features and as branded carry bags, detailed below:
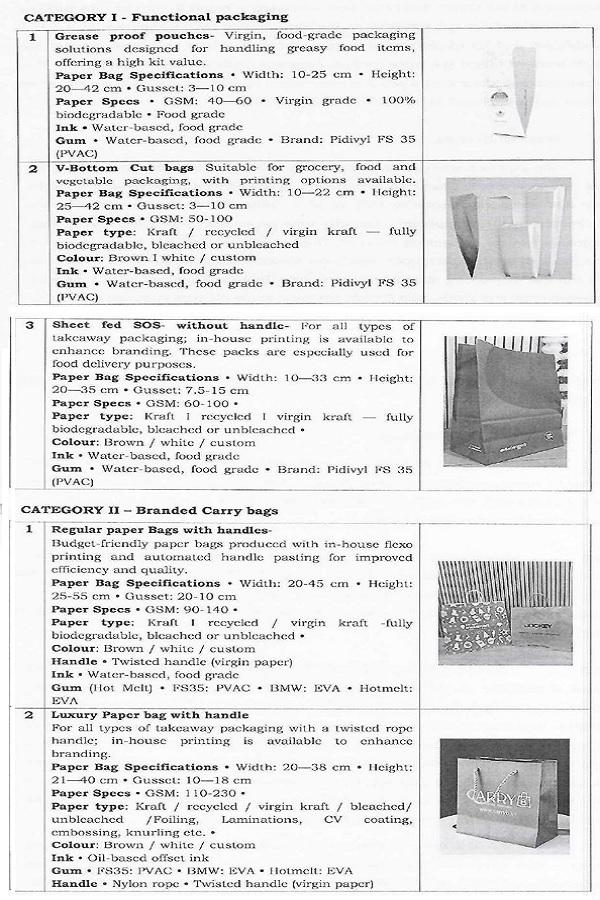
Further, they have stated that the issue of correct applicable rate was sought in the light of the relevant GST rate notification and the specific entry relating to paper sacks/bags liable to 5% GST and the recent divergent Advance Rulings on the issue, by (i) Gujarat AAR, in the case of M/s Canpac trends (P) Ltd– wherein paper bags under HSN 48194000 were held to be covered by the specific entry relating to paper sacks/bags and liable to 5% GST and (ii) Rajasthan AAR, in the case of M/s SGS Packaging (P) Ltd., has taken a contrary view and has held that the goods were liable to 18% GST.
7. Discussions and Findings:
7.1 We have carefully examined the submissions made by the applicant in their advance ruling application, during the personal hearing and also the additional submissions and the applicant’s interpretation of law in respect of question on which the advance ruling is sought.
7.2 We find that the query is liable for admission as it gets covered under Section 97(2)(a) and Section 97(2)(b) of CGST/TNGST Act, 2017, under, (a) classification of any goods or services or both; (b) rate of tax based on the applicability of a notification issued under the provisions of the CGST/TNGST Act, respectively.
7.3 We find that the applicant M/s Adhav Packs Private Limited, having place of business at Madathukulam, No. 2/319, Survey No. 573/3, Palani Taluk, Midapadi, Dindigul, Tamil Nadu, 624618, registered with the GST department with GSTIN 33AATCA3755C1ZQ, is engaged in the business of manufacturing and supply of paper bags and paper carry bags, primarily intended for use as packing material and that such bags are produced from kraft paper/uncoated paper, paper board and are designed and supplied for exclusive use as packaging material or carry bags, to retailers of goods, who in turn provide the same to the ultimate customers for carrying goods sold to them.
We find that, at present, the applicant is classifying the said goods under HSN 4819 40- under the description – ‘Other Sacks and bags’, and are supplying the same at 18% GST, as per entry 185 of Schedule II of Notification 9/2025-CT (R) dated 17.09.2025. They require to know if their product could be classified under 4819 20 and be covered by entry no. 322 of Schedule I of the Notification 9/2025-CT (R), @ 5% GST. The two questions that require ruling in the instant application, are,
(1) Whether paper bags /paper carry bags manufactured using Kraft Paper, which are biodegradable and supplied to retailers for exclusively use as packaging material and carry bags for goods sold to ultimate consumers, are classifiable under the HSN 4819 20 and covered under Entry 322 of Schedule-I of Notification No. 09/2025 – Central Tax (Rate) dated 17.09.2025?
(2) Whether paper carry bags manufactured using uncoated paper and paper board, which are supplied to retailers for use of packaging or carry bags for goods sold by them to customers, can be classified under HSN 4819 20 which is taxable @ 5% and covered under entry 322 of Schedule I of Notification 9/2025-CT (R) dated 17.09.2025?
We shall now proceed to analyse the facts on hand with the provisions of law and answer each one of the above questions, in that order.
7.4 The catalogue submitted by them reveals that, the applicant is involved in the manufacture of paper bags that include grease proof pouches, V-bottom cut bags and Sheet fed SOS (Self Opening Satchel) without handle, that are largely used for packaging food including greasy food, groceries, vegetables and all types of takeaway. It is seen that, by and large, the basic raw materials used in the manufacture of all these bags are, food grade paper (wherever food grade is required), ink, gum and coloring agent for customized colour paper bags. We find that applicant also manufactures Branded Carry bags, which include Regular paper Bags with handles and Luxury Paper bag with handle. Both of these are paper bags with in-house flexo printing, for which the applicant uses both food grade-water based ink as well as oil based offset ink; the bags are produced with automated handle pasting that include twisted rope handles made of either nylon or virgin paper. The bags are designed for all kinds of takeaway and also cater to the luxury market, for which the bags undergo processes of foiling, laminations, CV coating, embossing, knurling etc. and wherever the bags are not brown or white, pigments are added to customise the colour.
It is pertinent to add that though the catalogue claims that the paper used are biodegradable, it is also an admitted fact that the applicant uses materials that contain non-biodegradable content. In the backdrop of these facts, we now proceed to analyze the questions raised in the application for precise answers.
7.5.1 Question (1) Whether paper bags /paper carry bags manufactured using Kraft Paper, which are biodegradable and supplied to retailers for use exclusively as packaging material and carry bags for goods sold to ultimate consumers, are classifiable under the HSN 4819 20 and covered under Entry 322 of Schedule-I of Notification No. 09/2025 – Central Tax (Rate) dated 17.09.2025?
It is an undeniable and admitted fact that the applicant is involved in the business of manufacture of different varieties of paper bags, as detailed in the preceding paragraphs (Para 6 and 7.4).
Chapter 48 of the HSN covers ‘Paper and paperboard; articles of paper pulp, of paper or of paperboard’ and the Chapter Sub Heading- 4819 covers within its scope, ‘Cartons, boxes, cases, bags and other packing containers of paper, paperboard, cellulose wadding or webs of cellulose fibres; box files, letter trays and similar articles, of paper or paperboard of a kind used in offices, shops or the like.’ Hence, it is apt to classify the impugned product- paper bags under Chapter 48 and specifically under Chapter Sub heading 4819.
For ease of reference, the relevant portion of Chapter sub heading 4819 and the connected HSN notes is extracted here.
| 4819 | Cartons, boxes, cases, bags and other packing containers of paper, paperboard, cellulose wadding or webs of cellulose fibres; box files, letter trays and similar articles, of paper or paperboard of a kind used in offices, shops or the like |
| 4819 10 | Cartons, boxes and cases, of corrugated paper or paperboard: |
| 4819 1010 | Boxes |
| 4819 1090 | Other |
| 4819 20 | Folding cartons, boxes and cases of non-corrugated paper or paperboard: |
| 4819 2010 | Cartons, boxes, cases, intended for packing of match sticks |
| 4819 2020 | Boxes |
| 4819 2090 | Other |
| 4819 3000 | Sacks and bags, having a base of width of 40 cm or more |
| 4819 4000 | Other sacks and bags, including cones |
| 4819 50 | Other packing containers, including record sleeves : |
| 4819 5010 | Made of corrugated paper or paperboard |
| 4819 5090 | Other |
| 4819 6000 | Box files, letter trays, storage boxes and similar articles, of a kind used in offices, shops or the like |
The notes to the sub heading 4819 reads as below:
48.19 – Cartons, boxes, cases, bags and other packing containers, of paper, paperboard, cellulose wadding or webs of cellulose fibres; box files, letter trays, and similar articles, of paper or paperboard of a kind used in offices, shops or the like.
4819.10 – Cartons, boxes and cases, of corrugated paper or paperboard
4819.20 – Folding cartons, boxes and cases, of non-corrugated paper or paperboard
4819.30 – Sacks and bags, having a base of a width of 40 cm or more
4819.40 – Other sacks and bags, including cones
4819.50 – Other packing containers, including record sleeves
4819.60 – Box files, letter trays, storage boxes and similar articles, of a kind used in offices, shops or the like
(A) Cartons, boxes, cases, bags and other packing containers
This group covers containers of various kinds and sizes generally used for the packing, transport, storage or sale of merchandise, whether or not also having a decorative value. The heading includes cartons, boxes, cases, bags, cones, packets, sacks, paperboard drums (containers), whether manufactured by rolling or by any other method, and whether or not fitted with reinforcing circular bands of other materials, tubular containers for posting documents, protective garment bags, jars, pots and the like (e.g., for milk or cream), whether or not waxed. The heading also covers special purpose paper bags such as bags for vacuum cleaners, bags for travel sickness, and record boxes and sleeves.
The heading includes folding cartons, boxes and cases. These are:
- cartons, boxes and cases in the flat in one piece, for assembly by folding and slotting (e.g., cake boxes);
and
- containers assembled or intended to be assembled by means of glue, staples, etc., on one side only, the construction of the container itself providing the means of forming the other sides, although, where appropriate, additional means of fastening, such as adhesive tape or staples may be used to secure the bottom or lid.
The articles of this group may be printed, e.g., with the name of the merchant, directions for use, illustrations. Thus, seed packets with pictures of the products and sowing directions, in addition to the name of the firm, or chocolate or cereal packets with pictures for the amusement of children remain classified in this heading.
The articles of this heading may also have reinforcements or accessories of materials other than paper (e.g., textile backings, wooden supports, string handles, corners of metal or plastics).
(B) Box files, letter trays and similar articles of a kind used in offices, shops or the like
This group covers containers, such as filing cabinets, box files, letter trays, storage boxes and similar articles of a rigid and durable type, and generally of better finish than the packing containers of group (A) above. They are used for the filing or storage of documents or stock of various kinds in offices, shops, warehouses, etc.
These articles may have reinforcements or accessories of non-paper materials (e.g., hinges, handles, locking devices of metal, wood, plastics or textile material). They may also be provided with frames of metal, plastics, etc., for the insertion of indication cards.
The heading excludes:
a. Articles of heading 42.02 (travel goods, etc.).
b. Articles of plaited paper (heading 46.02).
c. Coated, covered and printed paper or paperboard of heading 48.11, presented in rolls, used for the manufacture of containers and creased and marked to identify individual containers to be cut from the rolls.
d. Albums for samples or for collections (heading 48.20).
e. Sacks and bags of woven paper yarn, of heading 63.05.
7.5.2 A detailed examination of the sub headings of 4819 and the notes thereof, reveals the following.
CSH 4819 10 deals with cartons, boxes and cases of corrugated paper or paper board and CSH 4819 20 deals with folding cartons, boxes and cases of non-corrugated paper or paper board.
The Merriam Webster English dictionary describes, ‘Carton’ as a type of box or container, typically made from paperboard, used for packaging a wide range of products including food, beverages, pharmaceuticals, and consumer goods; ‘Box’ is described as a container with a flat base and sides, typically square or rectangular and having a lid and ‘Case’ is described as a container or a large reusable receptacle that can accommodate smaller cartons or cases in a single shipment, designed for efficient handling of cargo.
On the contrary, we find that the applicant is in the business of manufacturing ‘bag’ which is defined as a flexible container with an opening at the top, used for carrying things.
The applicant’s question is whether their product “paper bags /paper carry bags manufactured using Kraft Paper…” can be classified under HSN 4819 20.
CSH 481920 specifies cartons, boxes and cases made of non-corrugated paper or paperboard and not ‘bags’, which is the impugned product. Paper bags/paper carry bags are distinct from cartons, boxes and cases specified under 4819 20. Therefore, we hold that the impugned product- paper bags made of kraft paper is not classifiable under HSN 4819 20.
Further, as regards to whether the impugned product is covered by entry 322 of Schedule I of the Notfn.9/2025-CT (R), it is seen that the said entry covers, cartons, boxes and cases of
(a) corrugated paper or paper boards; or
(b) non-corrugated paper or paper board, at 5% GST.
| 322. | 4819 10, 4819 20 | Cartons, boxes and cases of, – (a) Corrugated paper or paper boards; or (b) Non-corrugated paper or paper board |
In as much as the impugned product is not classifiable under 4819 10 or 4819 20, for the reasons mentioned above, we hold that the impugned product will not be covered under Entry 322 of Schedule I of the above notification, attracting 5% GST.
7.6.1 Question (2) Whether paper carry bags manufactured using uncoated paper and paper board, which are supplied to retailers for use of packaging or carry bags for goods sold by them to customers, can be classified under HSN 4819 20 which is taxable @ 5% and covered under entry 322 of Schedule I of Notification 9/2025-CT (R) dated 17.09.2025 ?
As discussed under para 7.5, it is reiterated that, the impugned product being paper carry bags, do not qualify to be classified under 4819 20, which covers folding cartons, boxes and cases of non-corrugated paper or paper board and not paper bags. Therefore, we hold that the impugned product, paper carry bags manufactured using uncoated paper and paperboard is not classifiable under HSN 4819 20 and for the same reason, we hold that they are not covered under Entry 322 of Schedule I of the Notification 9/2025-CT (R), at 5% GST.
7.7 Further, we find that, the applicant, in their additional submissions have brought the attention of this forum, to the divergent Advance Rulings of Gujarat AAR, in the case of M/s Canpac trends (P) Ltd., wherein paper bags under HSN 48194000 were held to be covered by the specific entry relating to paper sacks/bags and liable to 5% GST and that of Rajasthan AAR, in the case of M/s SGS Packaging (P) Ltd., who has taken a contrary view and has held that the goods were liable to 18% GST. We find that the aforesaid rulings do not have a direct bearing on the questions raised in the present application, as the applicant has specifically sought a ruling on the applicability of HSN 4819 20 and Entry 322 of Schedule I of Notification No. 09/2025-CT (Rate).
8. In view of the above, we rule as under:
RULING
1. Whether paper bags /paper carry bags manufactured using Kraft Paper, which are biodegradable and supplied to retailers for use exclusively as packaging material and carry bags for goods sold to ultimate consumers, are classifiable under the HSN 4819 20 and covered under Entry 322 of Schedule-I of Notification No. 09/2025 – Central Tax (Rate) dated 17.09.2025?
Ans. The impugned product- paper bags made of kraft paper is not classifiable under HSN 4819 20 and therefore is not covered under Entry 322 of Schedule I of the notification 9/2025-CT (R) dated 17.09.2025, attracting 5% GST.
2. Whether paper carry bags manufactured using uncoated paper and paper board, which are supplied to retailers for use of packaging or carry bags for goods sold by them to customers, be classified under HSN 4819 20 which is taxable @ 5% and covered under entry 322 of Schedule I of Notification 9/2025-CT (R) dated 17.09.2025?
Ans.The impugned product- paper carry bags manufactured using uncoated paper and paper board, is not classifiable under HSN 4819 20 and therefore is not covered under Entry 322 of Schedule I of the notification 9/2025-CT (R) dated 17.09.2025, attracting 5% GST.




