
Arya Kanya Vidyalaya Samiti Vs CIT (Exemption) (ITAT Jaipur)
Wrong Clause in Section 12A Application Is a Curable Defect: ITAT Jaipur
Background of the Dispute
The assessee challenged the CIT(E)’s order dated 24 September 2025, rejecting its application in Form 10AB under Section 12A(1)(ac)(iii) of the Income Tax Act, 1961.
The rejection rested on three grounds: filing the application under an incorrect clause, absence of registration under the Rajasthan Public Trust Act, and failure to establish the genuineness of activities.
The assessee was engaged in the charitable activity of imparting education. It contended that substantial documents and evidence supporting its activities had been submitted but were not properly considered before rejection.
Assessee’s Submissions
The assessee submitted that only two notices had been issued, dated 2 July 2025 and 15 September 2025, and that it had responded to both. Although the second response was considered incomplete, no further opportunity was provided to address the deficiencies.
According to the assessee, the CIT(E) rejected the application for want of bills and vouchers without adequately examining the voluminous material already furnished.
Regarding registration under the Rajasthan Public Trust Act, the assessee stated that it had subsequently obtained registration. Evidence showing that it had applied for such registration had already been placed before the CIT(E).
The assessee therefore sought another opportunity to establish compliance and demonstrate the genuineness of its educational activities.
Why the Application Was Filed Under Clause (iii)
The CIT(E) observed that the assessee already held registration under Section 12AA, granted on 3 February 2009. Consequently, according to the CIT(E), it should have applied under Section 12A(1)(ac)(i) instead of clause (iii).
However, the assessee explained that the Department had granted it provisional registration twice. The first order, dated 27 May 2021, covered assessment years 2021-22 to 2023-24. The second order, dated 7 April 2023, covered assessment years 2023-24 to 2025-26.
As the second provisional registration approached expiry, the assessee filed the application on 28 March 2025 under clause (iii). It maintained that the application had been filed bona fide, considering the provisional registrations previously granted by the Department.
Tribunal Finds Inadequate Opportunity of Hearing
The Tribunal noted that the assessee had responded to both notices. It therefore could not be regarded as non-cooperative during the proceedings.
A paper book comprising four volumes was filed before the Tribunal, demonstrating the documents, details and evidence submitted to the CIT(E).
The Tribunal observed that the CIT(E) had treated the genuineness of activities as unestablished for want of bills and vouchers without dealing with the material concerning the assessee’s educational activities.
Considering these circumstances, the Tribunal concluded that the assessee deserved another opportunity to address both the public trust registration issue and the genuineness of its activities.
Incorrect Clause Does Not Invalidate Application
On the objection concerning the incorrect clause, the Tribunal found that the CIT(E) had not properly examined the assessee’s explanation or verified the history of provisional registrations.
It observed that there appeared to have been errors or omissions on the part of both the assessee and the Department, concerning the applications and the grant of provisional registration.
The CIT(E) was directed to verify the facts, examine where the error or omission occurred, and then determine whether any deficiency existed.
Crucially, the Tribunal held that mere mention of a wrong clause does not invalidate an application. It is a curable defect, which should be brought to the assessee’s notice so that an opportunity for correction can be provided.
Decision and Significance
The Tribunal restored the registration issue to the CIT(E), directing adequate opportunity to furnish evidence regarding Rajasthan Public Trust Act registration, establish genuineness of activities, and address the incorrect-clause objection.
The appeal was allowed for statistical purposes. Registration was not granted outright; the CIT(E) must reconsider the application, including other matters necessary for registration.
The ruling underscores the need to examine explanations and supporting records before rejecting an application for a procedural defect.
FULL TEXT OF THE ORDER OF ITAT JAIPUR
The present appeal has been filed by the assessee against the order passed by the CIT Exemption, Jaipur (hereinafter referred to as “Ld. CIT(E)”), dated 24.09.2025, rejecting assessee’s application in Form 10AB seeking registration under Section 12A(1)(ac)(iii) of the Income Tax Act, 1961 (hereinafter referred to as “the Act”).
2. The grounds raised by the assessee read as under:-
1. 2. That Ld. CIT Exemption, Jaipur erred in cancelling the registration granted to the appellant without any cogent reason even when the appellant has been carrying on its activities as per the provisions of Income Tax Act, 1961. Accordingly, the impugned order cancelling the registration of the appellant u/s 12AB is bad in law and facts and deserves to be quashed.
2. 3. That the appellant prays to add OR alter any ground of appeal at OR before the time of hearing.
3. 1. That Ld. CIT Exemption, Jaipur erred in rejecting the application for renewal of registration u/s 12AB even when the appellant has been carrying on its activities according to the objects of the society and the grounds mentioned in the impugned order for rejecting the claim of renewal are against the facts of the case, trivial and no cogent ground mentioned in the order. Accordingly, the impugned order is bad in law and facts of the case, hence the appellant’s application for renewal of registration deserves to be accepted.
3. The order of the ld. CIT(E) reveals that the assessee’s application was rejected for the following reasons:-
- Non-maintainable as application filed in wrong clause.
- Non registrationunder Rajasthan Public Trust Act, 1959 (in short “RPT Act”)
- Non-genuineness of activities.
4. As far as the non-registration under the RPT Act and the non- genuineness of the activities is concerned, ld. Counsel for the assessee pleaded before us that sufficient opportunity of hearing was not granted to the assessee, with only two notices being issued to the assessee, one on the 02.07.2025 to which the assessee filed reply, and the other on the 15.09.2025 to which again the assessee filed reply, but was found to be incomplete by the Ld. CIT(E). He contended that voluminous documents, details & evidences were filed to the Ld. CIT (E) who failed to consider the same and rejected assesses application stating that bills and vouchers were not produced before him. It was further contended that the assessee has obtained registration under the RPT Act and had filed evidence before the Ld. CIT(E) of having applied for seeking the said registration. Ld. Counsel for the assessee pleaded that the assessee having obtained RPT registration and also being in a position to establish the genuineness of the activities carried out by it, therefore, an opportunity be granted to the assessee to clear the above two deficiencies noted by the ld. CIT(E) for grant of registration u/s 12A of the Act.
5. With respect to the deficiency noted by the Ld. CIT(E) of application being filed under the wrong clause, it was pointed out to us during the course of hearing, that a detailed reply in this regard was filed by the assessee to the ld. CIT(E), which is reproduced at page 4-6 of the order explaining the assessee’s position as to why the application was filed u/s 12A(1)(ac)(iii) , which the Ld.CIT€ noted to be wrong clause and to which, he contended, no cognizance was taken by the Ld. CIT(E).
6. Ld. DR however supported the order of the ld. CIT(E).
7. We have considered the rival submissions. Undoubtedly, the present order of the Ld. CIT(E) rejecting assessee’s application seeking registration u/s 12A(1)(ac)(iii) of the Act has been passed after giving only two notices of hearing to which. We find, Ld. CIT(E) has himself noted at para 1 of his order that the assessee did respond to the two notices. Therefore, it is not that the assessee was non-cooperative in the proceedings before the Ld. CIT(E). No further notices of hearing were given and the Ld. CIT(E) noted deficiencies to the effect that genuineness of activities were not established and that assessee was not registered under RPT Act. Genuineness of activities was found to have not been established since the assessee failed to produce complete bills and vouchers. Before us Paper Book in four volumes has been filed demonstrating the documents, details and evidences filed to the Ld. CIT(E) as under:
INDEX OF PAPER BOOK
| S.No. | Particulars | Page No. |
|---|---|---|
| (A) FILE NO – 1 | ||
| 1. | Devsthan Department Registration Certificate under Rajasthan Public Trust Act, 1959 | 1 |
| 2. | Provisional Registration u/s 12A of Income Tax Act,1961 from AY 2023-24 to AY 2025-26 | 2-3 |
| 3. | Application in form 10AB for renewal of registration u/s12A with Acknowledgement | 4-17 |
| 4. | Reply dated 14-07-25 submitted during proceeding u/s12A to CIT (Exemption) Jaipur | 18-19 |
| 5. | Executive Committee List with PAN and Aadhaar Card copies | 20-40 |
| 6. | Constitution (Vidhan – Patra) of Samiti | 41-49 |
| 7. | Certificate of Registration dated 26-11-1956 issued by Registrar of Companies | 50 |
| 8. | Application made to Devsthan Department for Registration | 51-56 |
| 9. | Audit Report for FY 2021-22, FY 2022-23 and FY 2023-24 | 57-132 |
| (B) FILE NO – 2 | ||
| 10. | Copies of ledger Accounts of Income and Expenditure of Samiti and Institutions run by Samiti for FY 2023-2024 | 133-497 |
| 11. | List of Institutions with Addresses run by Samiti | 498 |
| 12. | List of students for whom fees exempted in FY 2023-24 | 499 |
| 13. | Copy of Bank Account of Samiti for FY 2023-24 | 500-515 |
| (C) FILE NO – 3 | ||
| 14. | Reply dated 21-07-25 submitted during proceeding u/s12A to CIT (Exemption) Jaipur | 516-518 |
| 15. | Copies of 5 Expenditure Bills of Samiti and all educational institutions for FY 2023-24 submitted to CIT (Exemption) during 12A proceedings | 519-677 |
| 16. | Class wise details of number of students (3545) in Session 2023-24 | 678-679 |
| 17. | Photographs of the educational institutions with copies of newspaper cuttings | 680-717 |
| 18. | Details of Bank Accounts and E-mail addresses of Samiti and Institutions | 718-719 |
| (D) FILE NO – 4 | ||
| 19. | List of immovable properties with copies of purchase deeds | 720-916 |
| 20. | Copy of Resolution for Devsthan Registration | 917 |
| 21. | List of Vehicles owned by Samiti and Schools with Transport Department Registration Certificates | 918-922 |
| 22. | Copies of Recognition Letters issued by Education Department and University | 923-968 |
| 23. | Copies of Declaration form 10AC, ITR Ack., IT Computations | 969-981 |
| 24. | Details of staff and salary of samiti, schools and college for three years | 982-1067 |
| (E) FILE NO – 5 | ||
| 25. | Notice dated 02-07-2025 issued by CIT (Exemption) Jaipur | 1068-1075 |
| 26. | Notice dated 15-09-2025 issued by CIT (Exemption) Jaipur | 1076-1077 |
| 27. | Reply of Notice dated 19-09-2025 | 1078-1081 |
| 28. | Application for Condonation of delay dated 19-09-2025 | 1082-1085 |
| 29. | Application for Registration u/s12A filed on 31-12-2020 (The very first application) | 1086-1090 |
| 30. | Order for Provisional Registration dated 27-05-2021 | 1091-1093 |
| 31. | Order for Provisional Registration dated 07-04-2023 | 1094-1095 |
| 32. | Application for Registration u/s12A(1)(ac)(iii) filed on 28-03-2025 | 1096-1109 |
| 33. | Order dated 24-09-2025 for rejection of Application for renewal of Registration u/s12A (This order is the subject matter of appeal before ITAT) | 1110-1126 |
8. The Ld. CIT(E) has merely held genuineness of activities as not established for want of vouchers and bills, without dealing with the details and documents filed by the assessee as above relating to the charitable activity of imparting education carried out by it. Clearly, lack of sufficient opportunity of hearing has resulted in the Ld. CIT(E) recording finding of the assessee not being registered under the RPT Act and the genuineness of his activities not been established.
9. Ld. Counsel for the assessee has stated before us, that the assessee has obtained registration under the RPT Act, and we note that evidence of having applied for grant of registration under RPT Act was filed before the Ld.CIT( E).
10. Considering that adequate opportunity of hearing was not granted to the assessee with respect to these two issues of non-registration under the RPT Act and genuineness of activities carried out by the assessee trust not being established, we are of the view that the assessee be given another opportunity of hearing to bring out his contentions in this regard.
11. With regards to the denial of registration for the reason that application was filed under the wrong clause, the Ld. CIT(E)’s finding is to the effect that the assessee ought to have applied for registration under clause (i) of Section 12A(1)(ac) of the Act rather than applying for registration under sub-clause (iii) of the Act. As per the Ld. CIT(E) the assessee was already registered u/s 12AA of the Act vide registration order dated 03.02.2009 and therefore, assessee ought to have applied for registration as per law under clause (i) of Section 12A(1)(ac) of the Act. It is in this context, that he has held that the application filed by the assessee under sub-clause (iii) was under the wrong clause. His findings in this regard are contained at page 6 and 7 of his order as under:-
….
In view of the above discussions, it is imperative to quote the section 12A of Income Tax Act which is stated as below:
“12A. (1) The provisions of section 11 and section 12 shall not apply in relation to the income of any trust or institution unless the following conditions are fulfilled, namely:-
(ac) notwithstanding anything contained in clauses (a) to (ab), the person in receipt of the income has made an application in the prescribed form and manner to the Principal Commissioner or Commissioner, for registration of the trust or institution,-
(i) where the trust or institution is registered under section 12A (as it stood immediately before its amendment by the Finance (No. 2) Act, 1996 (33) of 1996)] or under section 12AA (as it stood immediately before its amendment by the Taxation and Other Laws (Relaxation and Amendment of Certain Provisions) Act, 2020 (38 of 2020)], within three months from the first day of April, 2021;
(ii) where the trust or institution is registered under section 12AB or approved under sub- clause (iv) or sub-clause (v) or sub-clause (vi) or sub-clause (via) of clause (23C) of section 10 and the period of the said registration or approval, as the case may be, is due to expire, at least six months prior to expiry of the said period;
(iii) where the trust or institution has been provisionally registered under Section 12AB or provisionally approved under sub-clause (iv) or sub-clause (v) or sub-clause (vi) or sub- clause (via) of clause (23C) of section 10, at least six months prior to expiry of period of the provisional registration 87[or provisional approval, as the case may be, or within six months of commencement of its activities, whichever is earlier,
(iv) where registration of the trust or institution has become inoperative due to the first proviso to sub-section (7) of section 11, at least six months prior to the commencement of the assessment year from which the said registration is sought to be made operative;
(v) where the trust or institution has adopted or undertaken modifications of the objects which do not conform to the conditions of registration, within a period of thirty days from the date of the said adoption or modification;
(vi) in any other case, where activities of the trust or institution have-
(A) not commenced, at least one month prior to the commencement of the previous year relevant to the assessment year from which the said registration is sought;
(B) commenced and no income or part thereof of the said trust or institution has been excluded from the total income on account of applicability of sub-clause (iv) or sub-clause (v) or sub-clause (vi) or sub-clause (via) of clause (23C) of section 10, or section 11 or section 12, for any previous year ending on or before the date of such application, at any time after the commencement of such activities, and such trust or institution is registered under section 12AB:
Provided that where the application is filed beyond the time allowed in sub-clauses (i) to (vi), the Principal Commissioner or Commissioner may, if he considers that there is a reasonable cause for delay in filing the application, condone such delay and such application shall be deemed to have been filed within time;”
On perusal of the sub-sections of 12A, it is noted that the applicant can apply for provisional registration under sub-clause (vi) only when it is not eligible to apply for registration under sub-clauses (i) to (v). In the present case, the applicant already have registration u/s 12AA dated 03.02.2009(affixed below) due to which the applicant should have applied for registration under clause (i) rather than applying for registration under sub-caluse (iii) on 28.03.2025. Thus, the applicant has taken registration in wrong clause.
……
12. The contention of the ld. Counsel for the assessee is that the circumstances in which the application was filed under sub-clause (iii) of Section 12A(1)(ac) of the Act, we find is correct. The order of the ld. CIT(E) itself reproduced the explanation of the assessee at page 4 to 6 of his order as under:-
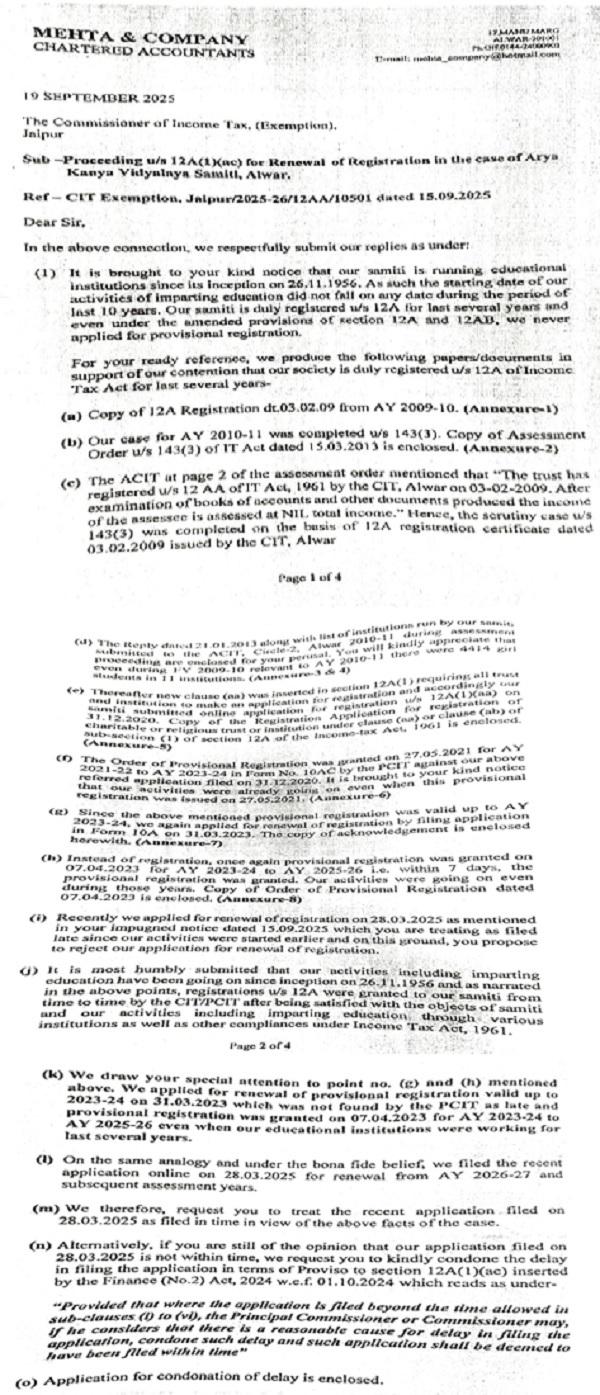
13. A perusal of the above would reveal that the assessee’s application seeking registration earlier on two occasions were approved and the assessee was granted provisional registration on both the occasions in the part, once on 27.05.2021 granting provisional registration for AY 2021- 22 to AY 2023-24 and another vide provisional registration order dated 07.04.2023 for AY 2023-24 to AY 2025-26. That when the provisional registration granted for the second time was about to expire the assessee filed the present application on 28.03.2025 seeking renewal of registration in terms of Section 12A(1)(ac)(iii) of the Act. The assessee in its letter had contended that this application was filed bonafidely. As per the assessee submission, it appears that the Department itself had granted provisional registration on previous two occasions therefore there appears to be have been some errors and omissions both on the part of the assessee and the Department while filing application forseeking registration and while granting provisional registration to the assessee, respectively.
14. Though, all these facts were brought to the notice of the Ld. CIT(E), he has not applied his mind to the same, not verified the facts before arriving at his finding of the assessee having filed application under the wrong clause for rejecting the application filed by the assessee.
15. We are of the view that the Ld. CIT(E) needs to look into the matter, verify the facts stated by the assessee, consider at whose part the error or omission took place when the assessee has stated that he has beengranted provisional registration twiceand thereafter arrive at a finding of deficiency if any in the application filed by the assessee. We may add that mere mentioning of wrong clause does not invalidate the application filed by the assessee. It is a curable defect in the application and the ld. CIT(E) ought to bring this notice of the assessee, after considering the explanation of the assessee of the circumstances in which the application was filed in clause(i) of section 12A(1)(ac) of the Act in the present case, so as to give him opportunity to remove the defect.
16. In view of the above , we restore the issue of grant of registration u/s 12A(1)(ac) of the Act back to the file of the Ld. CIT(E) to give adequate opportunity of hearing to the assessee to furnish all facts regarding being granted registration under the RPT Act, establishing the genuineness of its activities and also vis-à-vis the issue of application being filed under the wrong or incorrect clause, which is to be considered as per our findings and directions above and to consider all other matters necessary for grant of registration under the Act.
17. In effect, the appeal of the assessee stands allowed for statistical purposes.
Order pronounced in the Open Court on 02.11.2026




