Manish Chandulal Jobanputra Vs ITO (ITAT Rajkot)
Unsigned Section 151 Approval Invalidates Reassessment: ITAT Allows Assessee’s Appeal
Approval Lacked Both Manual and Digital Signatures
The Rajkot Bench of the Income Tax Appellate Tribunal (ITAT) has allowed an assessee’s appeal against reassessment after finding that the approval under Section 151 was neither manually signed nor digitally signed.
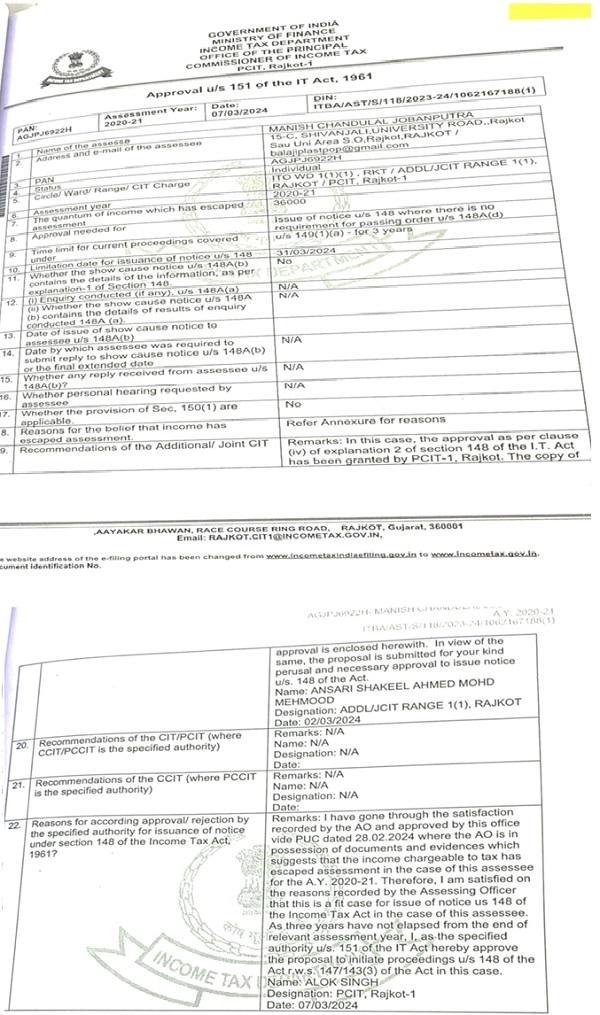
The Tribunal verified the defect by directing the Departmental Representative to produce the approval from the assessment records. The copy furnished before the Bench confirmed the absence of either form of signature.
Following its earlier decision in M/s Aditya Plastic, the Tribunal accepted the challenge to the reassessment founded on the defective approval. The decision turned on the validity of the jurisdictional sanction, rather than the merits of any income addition.
Case Details
The ruling was delivered in Manish Chandulal Jobanputra v. ITO, Ward-1(1)(1), Rajkot, ITA No. 414/RJT/2026, concerning Assessment Year 2020-21.
The order was pronounced on 22 October 2026 by Accountant Member Dr. Arjun Lal Saini, sitting on the Rajkot SMC Bench.
The assessee challenged the appellate order dated 4 February 2026, arising from an assessment completed under Section 147 on 7 March 2025.
At the hearing, the assessee focused on whether the approval relied upon to initiate reassessment constituted a valid sanction under Section 151.
Assessee Challenges Reopening Based on Defective Approval
The assessee’s counsel submitted that the sanctioning authority had not signed the approval manually or digitally.
He argued that reassessment proceedings initiated on the strength of such approval were bad in law and that the resulting assessment should be quashed.
In support, counsel relied on the Rajkot Tribunal’s decision in M/s Aditya Plastic, ITA No. 185/Rjt/2024, concerning Assessment Year 2013-14, decided on 3 September 2025.
According to the assessee, that decision involved identical and similar facts and squarely governed the present appeal.
The Departmental Representative relied on the Assessing Officer’s order.
Earlier Decision Treats Unsigned Approval as Invalid
The Tribunal examined the reasoning adopted in Aditya Plastic.
In that case, the approval of the Principal Commissioner was found to be without a signature. The earlier order also recorded the absence of a Document Identification Number (DIN) in the approval reproduced before it.
The coordinate Bench held that an unsigned approval could not be treated as a valid recording of satisfaction under Section 151. Consequently, a notice under Section 148 issued on its basis lacked the necessary jurisdictional foundation.
The present order relied on that precedent because the approval produced in the assessee’s own case was also unsigned. The finding concerning absence of a DIN formed part of the earlier case’s discussion, rather than a separate express finding in the present appeal.
Allahabad High Court Judgment Supports Prior Valid Satisfaction
The decision in Aditya Plastic had relied on the Allahabad High Court’s judgment in Vikas Gupta [2022] 142 taxmann.com 253.
The passages reproduced by the Tribunal explained that the Assessing Officer obtains jurisdiction to issue a Section 148 notice only after the prescribed authority records the necessary satisfaction under Section 151.
In Vikas Gupta, the relevant digital approval had been signed after the Section 148 notice was issued. The High Court therefore held that valid satisfaction did not exist when the Assessing Officer issued the notice.
The timing defect in that judgment differed from the absence of signatures in the present case. However, it supported the requirement that valid statutory approval must exist before jurisdiction is exercised.
Tribunal Calls for Original Assessment Record Evidence
The Tribunal did not decide the appeal merely on the assessee’s assertion.
It directed the Departmental Representative to produce a copy of the Section 151 approval from the assessment records, specifically to verify whether it had been signed.
The Departmental Representative furnished the document. On examination, the Tribunal expressly recorded that the approval was neither digitally nor manually signed.
This verification established the factual basis for applying the coordinate Bench’s decision. The defect concerned the approval supporting the assessee’s own reassessment, rather than an inference drawn solely from another taxpayer’s case.
Coordinate Bench Precedent Followed
The Tribunal found that Aditya Plastic squarely covered the issue in favour of the assessee.
It noted that there was no relevant change in facts or law and that the Revenue had produced no material warranting departure from the coordinate Bench’s findings.
Respectfully following that precedent, the Tribunal allowed the appeal.
Its reasoning treated the unsigned approval as a defect affecting the lawful initiation of reassessment proceedings. The outcome was therefore based on jurisdiction, without adjudicating the underlying tax dispute on merits.
Final Outcome
The assessee succeeded in the appeal on the ground that the Section 151 approval lacked both manual and digital authentication.
The ruling highlights the importance of examining the actual sanction available in the assessment records. In this case, the document produced by the Revenue itself confirmed the defect, enabling the Tribunal to apply its binding coordinate Bench precedent and grant relief.
Cases Discussed
- M/s Aditya Plastic Vs ITO (ITAT Rajkot), ITA No. 185/RJT/2024, AY 2013-14, dated 03.09.2025 — Directly followed. The coordinate Bench found the approval unsigned and discussed the absence of DIN; reassessment was quashed.
- Vikas Gupta (Allahabad High Court), (2022) 142 taxmann.com 253 — Discussed through the reproduced Aditya Plastic ruling. Digital approval recorded after the Section 148 notice was insufficient to confer jurisdiction when the notice was issued.
FULL TEXT OF THE ORIGINAL JUDGMENT/ORDER
Captioned appeal filed by the assessee, pertaining to assessment year (AY) 2020-21, is directed against the order passed under section 250 of the Income-tax Act, 1961 [hereinafter referred to as ‘the Act’] dated 04.02.2026 by the National Faceless Assessment Centre, Delhi/ Commissioner of Income Tax (Appeals) [hereinafter referred to as ‘Ld.CIT(A)/NFAC’], which in turn arises out of an assessment order passed by the Assessing Officer [hereinafter referred to as ‘AO’] u/s. 147 of the Act dated 07.03.2025.
2. When this appeal was called out for hearing, Ld. Counsel for the assessee invited my attention to the order dated 03.09.2025, passed by the Hon’ble ITAT, Rajkot Bench in the case of M/s Aditya Plastic, in ITA No. 185/Rjt/2024, for AY 2013-14, wherein identical and similar facts have been discussed and adjudicated in favour of assessee. The learned Counsel for the assessee submitted that approval under section 151 of the Act has neither been signed manually nor signed digitally, hence assessment order may be quashed. The Ld. Counsel pointed out that based on defective approval, the reassessment proceedings initiated by Assessing Officer is bad in law. The Ld. Counsel stated that the present appeal is squarely covered by the aforesaid order of the Hon’ble ITAT, Rajkot Bench, a copy of which was also placed before the Bench.
3. Learned Departmental Representative (Ld. DR) relied on the order of Assessing Officer.
4. I see no reasons to take any other view of the matter than the view so taken by the Hon’ble ITAT, Rajkot Bench in the case of M/s Aditya Plastic in ITA No. 185/Rjt/2024 for AY 2013-14 vide order dated 03.09.2025. In this order, the ITAT, Rajkot has inter alia observed as follows:
“8. We have heard both the parties, perused the material available on record. We note that the approval of the PCIT is without any signature of the Ld.PCIT and without generating any DIN number which is reproduced below:
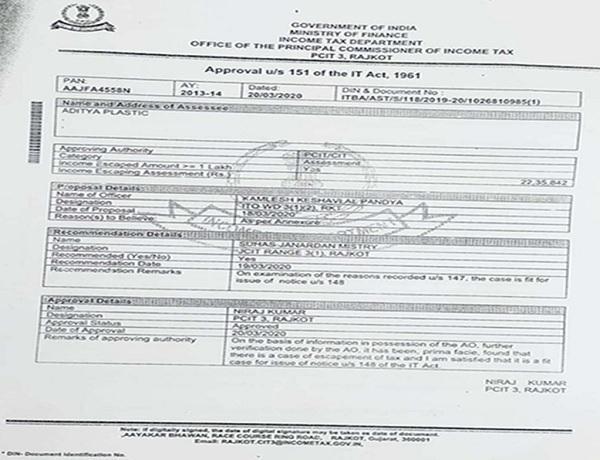
8.1. Therefore, the Ld.Cousel for the assessee has stated that the approval u/s.151 of the Act dated 30/03/2020 is not signed by the Ld.PCIT and, hence, it is not considered as a valid approval/satisfaction and, thus, the notice u/s.148 of the Act issued on the basis of said approval is bad in law and without jurisdiction. For that, reliance is placed on the judgement of Hon’ble High Court of Allahabad in the case of Vikas Gupta reported at (2022) 142 taxmann.com 253 (Allahabad HC). The relevant part of judgement is reproduced:
13. Thus, as per provision of section 151 of the Income-tax Act, 1961, an assessing officer gets jurisdiction to issue notice to an assessee under section 148 of the Act, 1961 after Principal Chief Commissioner or Chief Commissioner or Principal Commissioner or Commissioner of Income-tax is satisfied on the reason recorded by the assessing officer that it is a fit case for issuing such notice. The date and time of the approval granted digitally under section 151 of the Act and the date and time of the notice under section 148 of the Act, shows that the satisfaction was recorded by the PCTT digitally after the notice under section 148 was digitally signed.
29. In the present set of facts there was no valid satisfaction recorded by the by the Prescribed Authority under section 151 of the Act, 1961 when the Assessing Officer issued notice to the assessee under section 148 of the Act, 1961. At the time when the notice under section 148 of the Act, 1961 was issued by the Assessing Officer to the petitioner there was no valid satisfaction recorded by the Prescribed Authority ie. the Principal Chief Commissioner or Chief Commissioner or Principal Commissioner or Commissioner. Subsequent to issuance of the notice under section 148 of the Act, 1961 by the Assessing Officer, the satisfaction under section 151 was digitally signed by the Prescribed Authority. Therefore, the point of time when the Assessing Officer issued notices under section 148, he was having no jurisdiction to issue the impugned notices under section 148 of the Act, 1961. Consequently the impugned notices issued by the Assessing Officer under section 148 of the Act, 1961 were without jurisdiction. The questions no. (a) and (b) are answered accordingly.
8.2. Therefore, based on these facts and circumstances of the case, the assessment order framed by the AO needs to be quashed as there was no approval u/s.151 of the Act for initiating the re-assessment proceedings by the Ld.PCIT, therefore, on this count the assessment order framed by the AO should be quashed.”
5. The Bench has directed the learned DR for the revenue to provide approval under section 151 of the Act, from the assessment records, to verify the fact whether the approval under section 151 of the Act has been signed or not. Accordingly, Ld. DR for the revenue, provided to the Bench, a copy of the approval under section 151 of the Act, which is neither signed digitally nor manually, which is reproduced below:
6. As the issue is squarely covered in favour of the assessee by the decision of the ITAT, Rajkot Bench in the case of M/s Aditya Plastic (supra), and there is no change in facts and law and the revenue is unable to produce any material to controvert the aforesaid findings of the Division Bench (supra). I find no reason to interfere in the said order of the Division Bench. Therefore, respectfully following the binding precedent of the Coordinate Bench (supra), I allow the appeal of the assessee.
7. In the result, the appeal of the assessee is allowed.
Order is pronounced in the open court on 22/10/2026.