Aditya Plastic Vs ITO (ITAT Rajkot)
Summary: The Income Tax Appellate Tribunal, Rajkot Bench, in Aditya Plastic Vs Income Tax Officer, considered two appeals relating to Assessment Year 2013-14, challenging the validity of reassessment proceedings and a consequential penalty. The Assessing Officer had reopened the assessment on the basis of information alleging that the assessee received unaccounted payments of Rs.22,35,842 through Shri Chetanbhai Haribhai Bhalodiya, proprietor of M/s Yash Enterprise, during Financial Year 2012-13. A notice under Section 148 of the Income-tax Act, 1961, was issued on 20 March 2020, and an assessment under Section 147 read with Section 144 was completed on 29 September 2021, treating the amount as unexplained money under Section 69A. The CIT(A) upheld the assessment.
The assessee challenged the reopening on several jurisdictional grounds. It was submitted that the original partnership firm had been dissolved on 30 October 2004 and subsequently operated as a proprietorship under a different PAN. The assessee further argued that the sanction purportedly granted under Section 151 did not bear the signature or digital authentication of the Principal Commissioner of Income Tax. The reasons recorded by the Assessing Officer were also challenged as constituting borrowed satisfaction based on information from the Investigation Wing without independent enquiry or application of mind. The assessee relied on several High Court decisions concerning invalid sanction, borrowed satisfaction and absence of tangible material.
The Tribunal examined the approval document reproduced in the order and recorded that the approval of the Principal Commissioner was without signature and without generation of a DIN. It referred to the Allahabad High Court decision in Vikas Gupta, which emphasised that valid satisfaction of the prescribed authority under Section 151 must exist when the notice under Section 148 is issued. Applying that principle, the Tribunal held that the reassessment proceedings lacked valid statutory approval and quashed the assessment. The decision was based on the jurisdictional defect, without separately determining the merits of the alleged unexplained money or the assessee’s alternative contention that only the profit element could be assessed.
In the connected appeal, ITA No.186/Rjt/2024, the assessee challenged a penalty imposed under Section 271(1)(b) for alleged non-compliance with notices. Since the underlying reassessment was quashed, the Tribunal also quashed the consequential penalty order. Both appeals were allowed. The order thus addresses the importance of valid approval under Section 151 before initiation of reassessment proceedings and the consequential effect of invalid reassessment on the related penalty.
List of Cases Discussed:
1. Vikas Gupta, (2022) 142 taxmann.com 253 (Allahabad High Court): Relied upon in the Tribunal’s reasoning. The High Court held that satisfaction under Section 151 recorded after issuance of the reassessment notice could not retrospectively confer jurisdiction upon the Assessing Officer.
2. Narsimha Trading Co., (2025) 170 taxmann.com 10 (Gujarat High Court): Cited by the assessee to challenge reopening based on borrowed satisfaction without independent enquiry.
3. Amitkumar Chandulal Rajani, SCA No.2930 of 2022, Gujarat High Court, dated 20.01.2025: Cited regarding the requirement to establish a connection between material received and the reasons recorded for reopening.
4. Vijay Ramanlal Sanghvi, (2023) 457 ITR 791 (Gujarat High Court): Cited regarding reopening without tangible material or independent satisfaction of the Assessing Officer.
5. Bhavin Jayendrakumar Soni, (2024) 165 taxmann.com 109 (Gujarat High Court): Cited concerning borrowed satisfaction and reassessment based solely on Investigation Wing information.
FULL TEXT OF THE ORIGINAL ORDER OF ITAT RAJKOT
Captioned two appeals filed by the same Assessee pertaining to Assessment Year (AY) 2013-14 are directed against the order passed by the Learned Commissioner of Income Tax (CIT(A)-[(in short “Ld.CIT(A)”] vide order dated 01/02/2024, which in turn arises out of an assessment order dated 29/09/2021passed by the Assessing Officer (AO) u/s. 147 r.w.s. 144 of the Income Tax Act, 1961 (in short, “the Act”) pertaining to Assessment Year (AY) 2013-14.
2. The grounds of appeal raised by the Assessee are as follows:
1. The learned Commissioner (Appeals) erred in confirming the action of Income Tax Officer ward-3(1)(1), Rajkot in issuing the notice u/s 148 of the Act and thereby framing assessment u/s 147 r.w.s. 144 of the Act.
2. `The learned Commissioner (Appeals), erred in upholding action of the Income-tax Officer, Ward 3(1)(1) Rajkot in not granting the reasonable opportunity of being heard to the Appellant, thereby violating the principle of natural justice.
3. On merits, the learned Commissioner (Appeals), erred in confirming the action of the Income-tax Officer, Ward 3(1)(1), Rajkot in making addition of Rs. 22,35,842/- by way of unexplained money u/s 69A of the Act.
4. On merits, the learned Commissioner (Appeals), erred in confirming the action of the Income-tax Officer, Ward 3(1)(1), Rajkot in making addition of Rs. 2,00,000/- by way of exemption limit.
5. The appellant craves leave to add, amend, alter or withdraw all or any ground of appeal at any time upto the date of hearing of the appeal.
3. Brief facts qua the issue are that, on perusal of the available records, the AO was found that the assessee has received unaccounted payments of Rs.22,35,842/- through Shri ChetanbhaiHaribhai Bhalodiya Prop. M/s. Yash Enterprise, Rajkot during the Financial Year 2012-13, i.e. Assessment Year 2013-14. As per the records, the assessee has not filed its return of income for the year under consideration. In view of above facts of the case, having reasons to believe that an amount of exceeding Rs.1 Lakh has escaped assessment within meaning of Sec. 147 of the I.T. Act, 1961 to the tune of Rs.22,35,842/- for the AY 2013-14, the assessment was re-opened u/s. 147 of the I.T. Act, 1961 after recording reasons and obtaining requisite approval from the Competent Authority. Thereafter, notice u/s. 148 of the Act was issued on 20.03.2020 which was duly served upon the assessee. Notice u/s. 142(1) was issued on 29.09.2020.The case was transferred to NFAC as per FAS-2019. However, due to technical reasons the same has been transferred back to the JAO for completion of assessment procedure as per E No. 187/3/2020-ITA-I, dated 06.09.2021 (Order u/s. 119 of the Act). Vide F.No.225/97/2021/ITA-II dated 06.09.2021 (Procedure for handling of assessment by JAO) it has been directed that the assessee’s may be requested to get themselves registered with the e-filing portal of the department. In light of the same, the assessee was requested to get registered with the e-filing portal of the department and/or send assessee’s e-mail address so that the assessment procedures can be completed through electronic mode.
3.1. The AO has recorded the reasons stating that the assessee has received amount of Rs.22,35,842/- in cash in lieu of cheque deposits or demand drafts for the year under consideration and the assessee has not declared income of Rs.22,35,842 /- in the return of income filed by the assessee. The A.O, after duly recording the reasons in writing that there is an is an omission or failure on the part of the assessee to disclose full and true material facts necessary for the assessment for the year under review had formed an opinion that income chargeable to tax has escaped assessment. Therefore, the case was re-opened after due diligence and not on the basis of allegation and without substantially establishing any connection. The assessment is re-opened of those assesses whose PAN is quoted, as per information received from ADIT (Inv)-II, Rajkot.
3.2. In view of the detailed discussion above, it is clear that the assessee had entered into transactions with M/s. Yash Enterprise Prop. Shri Chetan Bhalodiya to the tune of Rs.22,35,842/- during the A.Y. 2013-14 which has not been explained by the assessee nor has been shown by the assessee by filing ROI. Hence, the amount of Rs.22,35,842/- was assessed by AO u/s.69A of the Income-tax Act, 1961 on the ground that the credit was mere a procurement of money without proper explanation of how and why it has come to the assessee; hence unexplained money.
4. Aggrieved by the order of the AO, the assessee carried the matter in appeal before the ld.CIT(A) who has confirmed the action of the AO.
5. Dissatisfied with the order of the Ld.CIT(A), the assessee is in further appeal before us.
6. The Ld. Counsel for the assessee argued that there is no signature/digital ID on the approval u/s.151 of the Act. Therefore, approval given by the AO to the reasons recorded by the AO u/s.147/`148 of the Act is bad in law. Since there is no approval, therefore, the consequential re-ass1essment proceedings u/s.147/148 of the Act are bad in law.
6.1. The Ld. Counsel for the assessee also submitted that the reasons submitted by the AO are bad in law and there are basis on the borrowed satisfaction and there was no material before the AO to re-open the assessment proceedings. The Ld. Counsel for the assessee also submitted before us that the reasons on the technical issue which are reproduced below:-
“1. The Appellant-partnership firm has been dissolved on 30-10-2004 vide its dissolution deed dated 30-10-2004 [the same was informed to CIT(A)].
2. Notice u/s 148 for the year was issued on the PAN of the partnership firm i.e. AAJFA4558N whereas it was converted into a proprietorship firm under the same name having different PAN. Hence, if the A.O. had information regarding alleged unaccounted cash receipt from Mr. Chetan Bhalodiya, the A.O. could have issued notice in the name of Aditya Plastic existing as a proprietorship concern as the partnership firm was not in existence during the year.
3. Approval u/s 151 of the Act dated 20-03-2020 is not signed by the PCIT -3, Rajkot and hence it is not considered as a valid approval (satisfaction) and thus the notice u/s 148 issued on the basis of said approval is bad in law and without jurisdiction – Vikas Gupta (2022) 142 taxmann.com 253 (Allahabad HC).
4. The A.O. in Para 4 of the reasons recorded for re-opening u/s 147 of the Act states that “no further enquiries made as the information received from the DDIT (Inv.), Unit-1(3), Ahmedabad .”. This shows that the A.O. has blindly relied upon the information received from the DDIT (Inv.), Ahmedabad and has not made any further enquiries and has not applied his mind while forming a belief that income had escaped assessment in case of Appellant. This amounts to borrowed satisfaction which is not permitted in law. Narsimha Trading Co. (2025) 170 taxmann.com 10 (Guj HC).
5.Reasons recorded for re-opening do not show the link between the information received and reasons recorded by the A.O. No reference has been made in the reasons recorded as to the transaction carried out by the A.O.
6. Reliance in this regard is placed upon decisions of Gujarat High Court in following cases:
i. Amitkumar Chandulal Rajani in SCA No. 2930 of 2022 dated 20-01-2025, wherein it has been held that in absence of any link established by the A.O. between the material found from M/s. National Shroff and the reasons recorded and only relying upon the information received by the A.O. amounts to borrowed satisfaction and thus the assessment u/s 147 based on said reasons recorded is bad in law and is quashed.
ii. Vijay Ramanlal Sanghvi (2023) 457 ITR 791 (Guj HC) wherein it was held that in absence of any tangible material to form an opinion that income chargeable to tax had escaped assessment and in absence of any satisfaction recorded by Assessing Officer by merely relying upon information received from Office of Deputy Commissioner, impugned action of reopening assessment while exercising power under section 148 could not be sustained.
iii. Bhavin Jayendrakumar Soni (2024) 165 taxmann.com 109 (Guj. HC) wherein it was held that forming of ‘reason to believe’ is merely based on the information so received by the Assessing Officer. Thus, it cannot be said that the Assessing Officer has recorded its independent satisfaction, but only relied upon the information received from the Investigation Unit, which is nothing, but said to be borrowed satisfaction. Since no tangible and/or new material has come in possession of the Assessing Officer, the reassessment proceedings can also be said on the basis of the change of opinion, which, according to our considered opinion, is not permissible in the eye of law.
Hence, in view of binding precedents, the order u/s 147 is bad in law and it is prayed that the same be quashed.”
6.2. The Ld.Counsel for the assessee further submitted that if the addition is to be made in the hands of the assessee, then only profit element is to be added and not the entire amount.
7. On the other hand, the Ld.DR for the revenue submitted that approval given by the PCIT has to be signed for that the Ld.DR for the revenue has provided the necessary evidences.
7.1. On re-opening of the assessment, the Ld.DR for the revenue submitted that the AO has recorded the reasons after conducting the primary enquiry, therefore, reasons are recorded as per the scheme of the Act and there is no borrowed satisfaction in these reasons so recorded by the AO u/s.147/148 of the Act.
7.2. On merits, the Ld.DR submitted that since the assessee has not appeared before the AO, therefore matter may be remanded back to the file of the AO for fresh adjudication.
8. We have heard both the parties, perused the material available on record. We note that the approval of the PCIT is without any signature of the Ld.PCIT and without generating any DIN number which is reproduced below:
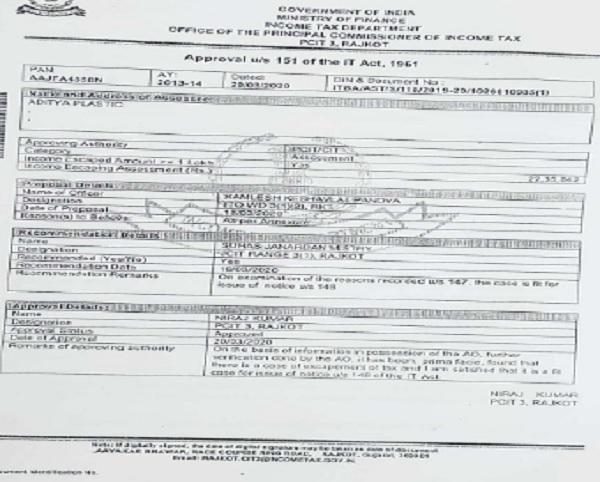
8.1. Therefore, the Ld.Cousel for the assessee has stated that the approval u/s.151 of the Act dated 30/03/2020 is not signed by the Ld.PCIT and, hence, it is not considered as a valid approval/satisfaction and, thus, the notice u/s.148 of the Act issued on the basis of said approval is bad in law and without jurisdiction. For that, reliance is placed on the judgement of Hon’ble High Court of Allahabad in the case of Vikas Gupta reported at (2022) 142 taxmann.com 253 (Allahabad HC). The relevant part of judgement is reproduced:
13. Thus, as per provision of section 151 of the Income-tax Act, 1961, an assessing officer gets jurisdiction to issue notice to an assessee under section 148 of the Act, 1961 after Principal Chief Commissioner or Chief Commissioner or Principal Commissioner or Commissioner of Income-tax is satisfied on the reason recorded by the assessing officer that it is a fit case for issuing such notice. The date and time of the approval granted digitally under section 151 of the Act and the date and time of the notice under section 148 of the Act, shows that the satisfaction was recorded by the PCTT digitally after the notice under section 148 was digitally signed.
29. In the present set of facts there was no valid satisfaction recorded by the by the Prescribed Authority under section 151 of the Act, 1961 when the Assessing Officer issued notice to the assessees under section 148 of the Act, 1961. At the time when the notice under section 148 of the Act, 1961 was issued by the Assessing Officer to the petitioner there was no valid satisfaction recorded by the Prescribed Authority ie. the Principal Chief Commissioner or Chief Commissioner or Principal Commissioner or Commissioner. Subsequent to issuance of the notice under section 148 of the Act, 1961 by the Assessing Officer, the satisfaction under section 151 was digitally signed by the Prescribed Authority. Therefore, the point of time when the Assessing Officer issued notices under section 148, he was having no jurisdiction to issue the impugned notices under section 148 of the Act, 1961. Consequently the impugned notices issued by the Assessing Officer under section 148 of the Act, 1961 were without jurisdiction. The questions no. (a) and (b) are answered accordingly.
8.2. Therefore, based on these facts and circumstances of the case, the assessment order framed by the AO needs to be quashed as there was no approval u/s.151 of the Act for initiating the re-assessment proceedings by the Ld.PCIT, therefore, on this count the assessment order framed by the AO should be quashed.
ITA 186/Rjt/2024 for AY 2013-14
9. That the assessee filed an appeal against the penalty order u/s. 271(1)(b) dated 31.12.2021 and the order was duly confirmed by the Ld. CIT(A) on 01.02.2024.
10. The penalty was levied on the assessee for non-compliance of notice dated 29.02.2020, 04.02.2021, 20.02.2021. Since in this case the assessee filed an appeal against the appellate order before this Tribunal in ITA No. 185/Rjt/2024 for AY 2013-14, that the reassessment order dated 01.02.2024 was quashed, resultantly the penalty order also quashed.
In the result, the appeal of the assessee is allowed.
Order pronounced in the Open Court on 03/09/2025 at Rajkot.