Summary: Punjab & Haryana High Court in Shaurya Alloys Pvt. Ltd. v. State of Punjab & Another laid down fourteen guidelines governing denial of Input Tax Credit (ITC) under Section 16(2)(c) of the CGST Act where suppliers fail to deposit tax, report nil or short liability, or subsequently face cancellation of GST registration. The Court held that supplier-side default or retrospective cancellation can trigger investigation but cannot, by itself, result in mechanical reversal of the purchaser’s ITC. The proper officer must investigate the nature of the supplier’s default, examine its nexus with the purchaser, disclose relied-upon material and consider evidence establishing the genuineness of the transaction. While the burden of proving ITC eligibility under Section 155 continues to rest on the purchaser, fraud attributable to the supplier cannot automatically be treated as fraud by the purchaser for invoking Section 74 or Section 74A. The Court also stressed examination of recovery proceedings against defaulting suppliers, the period-wise statutory position, Rule 37A, personal hearing and speaking orders. The guidelines apply to pending as well as future proceedings before proper officers within the Court’s jurisdiction.
- ITC Denial for Supplier’s Default: Punjab & Haryana High Court Draws a Procedural Red Line
- 1. The Core Controversy
- 2. The Fundamental Principle
- 3. What the Court Did, and What It Did Not Do
- 4. The Fourteen Guidelines: A New Adjudication Framework
- Guidelines I–IV: Investigation Before Demand
- Guideline I: Supplier default is a starting point, not the conclusion
- Guideline II: The proper officer must record satisfaction before issuing a notice
- Guideline III: The investigation must examine nexus with the purchaser
- Guideline IV: Material relied upon must be disclosed
- Guidelines V–VIII: Fraud, Burden of Proof and Supplier Recovery
- Guideline V: Fraud cannot travel automatically from seller to buyer
- Guideline VI: The Section 155 burden remains on the purchaser
- Guideline VII: Retrospective cancellation of the supplier’s registration
- Guideline VIII: Proceedings against the supplier matter
- Guidelines IX–XIV: Period-wise Law, Registration and Procedure
- Guideline IX: Different tax periods require different law
- Guideline X: The purchaser’s registration cannot be cancelled automatically
- Guideline XI: Personal hearing and cross-examination
- Guideline XII: A speaking order is not optional
- Guideline XIII: DRC-03 payment is not an admission of fraud
- Guideline XIV: Pending and future proceedings
- 5. Relief Granted in the Connected Petitions
- 6. Systemic Reforms Suggested by the Court
- 7. A Practical Framework After Shaurya Alloys
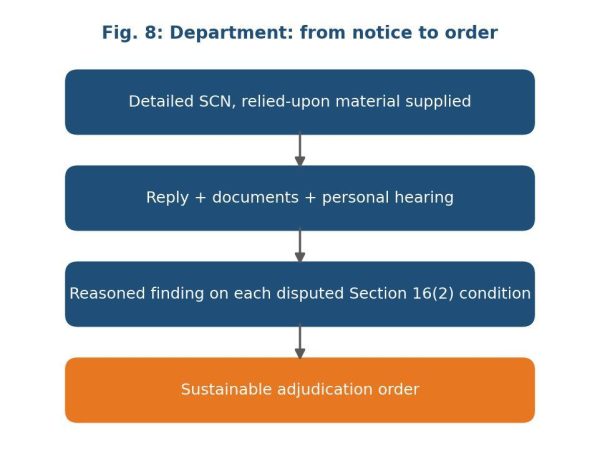
- For the Department
- –
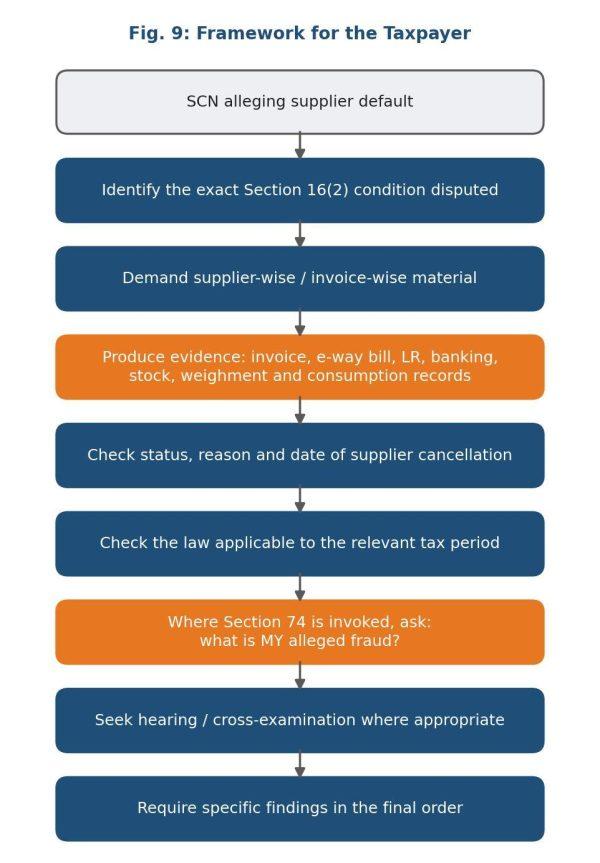
- For the Taxpayer
- 8. The Larger Significance
- Conclusion
ITC Denial for Supplier’s Default: Punjab & Haryana High Court Draws a Procedural Red Line
Analysis of Shaurya Alloys Pvt. Ltd. v. State of Punjab & Another and Connected Matters: Judgment dated 1 October 2026
| Case particulars | Details |
|---|---|
| Lead case | CWP-34296-2024 (O&M), Shaurya Alloys Pvt. Ltd. v. State of Punjab and Another, with a large batch of connected writ petitions |
| Court | High Court of Punjab and Haryana |
| Reserved / Pronounced | 21.08.2026 / 01.10.2026 |
| Provision in focus | Section 16(2)(c), CGST Act, 2017, read with Sections 29(2), 41, 73, 74, 74A, 75, 155 and Rule 37A, CGST Rules |
| Operative portion | Paragraph 103: fourteen guidelines for administering Section 16(2)(c) |
In its judgment of 1 October 2026 in Shaurya Alloys Pvt. Ltd. v. State of Punjab & Another and a large batch of connected petitions, the Punjab & Haryana High Court has set out a detailed framework for invoking Section 16(2)(c) of the CGST Act, 2017 against purchasing dealers.
The decision matters, but not because it dispenses with the requirement that tax charged on a supply must actually reach the Government. It matters because it restricts the mechanical shifting of a supplier’s default onto the purchasing dealer.
The Court has said in so many words that its guidelines neither dilute nor add to Section 16(2). They exist so that the statutory conditions are enforced through the machinery the GST law itself contemplates.
The ruling therefore takes the law forward on several connected questions: supplier default, retrospective cancellation of registration, bogus-billing allegations, the burden of proof under Section 155, and proceedings under Sections 73/74/74A.
1. The Core Controversy
Subject to Section 41, Section 16(2)(c) bars a recipient from availing ITC unless the tax charged on the supply has actually been paid to the Government, whether in cash or through admissible ITC.
The difficulty that kept recurring before the Court is shown below.
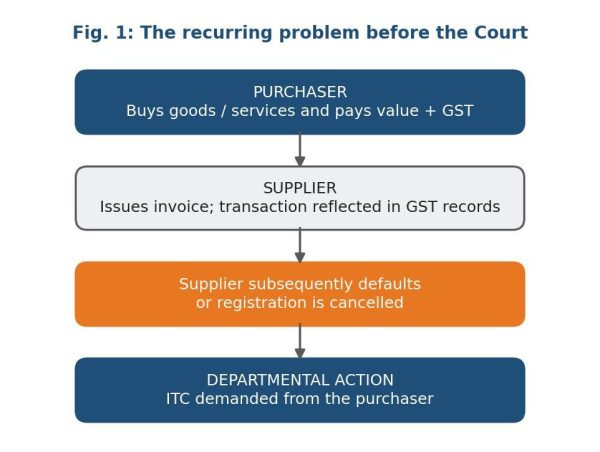
In several of the proceedings, ITC was sought to be denied because the selling dealer had failed to pay tax, had shown nil or short tax liability, or had later suffered cancellation of registration, in some cases with retrospective effect.
The Court held that such circumstances can justify an investigation. They cannot, on their own, justify automatic denial of ITC.
2. The Fundamental Principle
| The default or fraud of the supplier does not automatically become the default or fraud of the purchaser. |
Where the Department invokes Section 74 against a purchasing dealer on grounds of fraud, wilful misstatement or suppression, the notice itself must carry the foundational facts that connect that dealer with the alleged fraud.
Merely repeating words such as “fraud”, “wilful misstatement” or “suppression” will not do. Nor can gaps in the notice be filled later, by an affidavit in the High Court or by explanations devised after the notice was issued.
The practical consequences of this distinction are considerable.
3. What the Court Did, and What It Did Not Do
| Question | Position emerging from the judgment |
|---|---|
| Is Section 16(2)(c) rendered ineffective? | No. It continues to operate. |
| Is payment of tax by the supplier irrelevant? | No. It remains a statutory condition. |
| Can ITC be denied merely because the supplier’s registration was later cancelled? | Not automatically. Further examination is necessary. |
| Can retrospective cancellation alone establish a bogus purchase? | No. Its relevance to the particular supply must be established. |
| Does Section 155 place the burden on the purchaser? | Yes. The purchaser must establish eligibility to ITC. |
| Is an invoice alone sufficient in every case? | No. Receipt and genuineness may require supporting evidence. |
| Must the Department investigate the supplier’s default? | The proper officer must examine the nature of the default, recovery proceedings and relevant evidence before proceeding mechanically against the purchaser. |
| Can genuine transactions still lose ITC? | Section 16(2)(c) can operate in accordance with law, but only after the statutory framework and the Court’s guidelines are followed. |
| What about collusion or fake purchases? | Such cases remain fully open for departmental action. |
| Can Section 74 be invoked simply because the supplier committed fraud? | No. Facts connecting the purchaser with the fraud must be stated. |
4. The Fourteen Guidelines: A New Adjudication Framework
The heart of the judgment is paragraph 103, in which the Court formulated fourteen guidelines for the administration of Section 16(2)(c). They fall naturally into three groups.
| Group | Subject | Guidelines |
|---|---|---|
| I – IV | Investigation before demand | Alert is a starting point; satisfaction before notice; nexus with purchaser; disclosure of material |
| V – VIII | Fraud, burden of proof and supplier recovery | Section 74 / 74A; Section 155; retrospective cancellation; remedies against supplier |
| IX – XIV | Period-wise law and procedure | Tax period; purchaser’s registration; hearing; speaking order; DRC-03; pending cases |
Guidelines I–IV: Investigation Before Demand
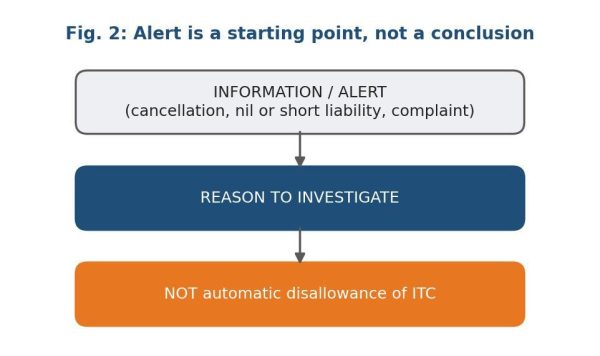
Guideline I: Supplier default is a starting point, not the conclusion
The following may legitimately set an inquiry in motion:
- retrospective or subsequent cancellation of the supplier’s registration;
- nil or short liability declared by the supplier;
- departmental alerts; and
- complaints or other intelligence.
None of these, taken alone, is enough to reverse the recipient’s ITC. The distinction is between information that gives a reason to investigate and a basis for automatic disallowance.
Guideline II: The proper officer must record satisfaction before issuing a notice
Before a notice resting on Section 16(2)(c) is issued, the proper officer must identify and examine the following.
| Area of examination | What must be considered |
|---|---|
| Supplier | Particulars of the selling dealer |
| Transaction | Invoice numbers and tax periods |
| Quantum | Amount of ITC involved |
| Nature of default | Whether tax was not paid, short paid, or discharged through allegedly inadmissible ITC |
| Reason for default | Circumstances surrounding the supplier’s failure to deposit tax |
| Recovery against supplier | Action under Sections 73, 74, 75(12)/79, 76 etc., and the status of that action |
Guideline III: The investigation must examine nexus with the purchaser
Where a violation of Section 16(2) is alleged, the investigation must establish some direct link between the purchaser and the supplier. This carries particular weight in alleged bogus-billing chains.
Guideline IV: Material relied upon must be disclosed
The show cause notice must state the basis of the proposed ITC denial together with supplier-wise particulars. The documents relied upon may include:
- alert notices and inspection reports;
- panchnamas and statements recorded during investigation;
- e-way bill and vehicle registration data;
- toll information; and
- banking data.
All of these are to be supplied to the noticee, subject to any privilege lawfully claimed.
Guidelines V–VIII: Fraud, Burden of Proof and Supplier Recovery
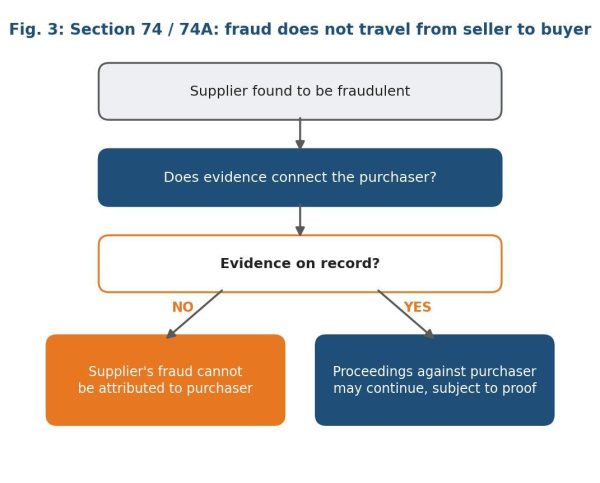
Guideline V: Fraud cannot travel automatically from seller to buyer
If Section 74, or Section 74A for the relevant period, is invoked alleging fraud, suppression or wilful misstatement, the notice must itself explain why the purchaser is alleged to have taken part in that conduct. The logic is set out below.
Guideline VI: The Section 155 burden remains on the purchaser
The judgment is no charter for automatic allowance of ITC. The Court expressly accepts that, under Section 155, the burden of proving eligibility rests on the person claiming credit. A purchasing dealer may discharge it with material such as the following.
| Evidence | Purpose |
|---|---|
| Tax invoice | Establishes the documentary basis of the purchase |
| E-way bill | Supports the movement of goods |
| Transport receipt | Establishes transportation |
| Weighbridge slip | Corroborates physical movement and quantity |
| Stock register | Demonstrates receipt into inventory |
| Consumption records | Establish subsequent use |
| Other business records | Corroborate commercial genuineness |
The proper officer must consider this evidence and deal with it in the order. The balance struck here is worth noting: the Department cannot proceed mechanically, but the purchaser also cannot rest on a tax invoice alone where genuineness is seriously disputed.
Guideline VII: Retrospective cancellation of the supplier’s registration
Where the denial of ITC rests on retrospective cancellation, the officer must examine three things:
1. why the registration was cancelled;
2. from what date the cancellation took effect; and
3. whether those grounds actually affect the genuineness of the particular supply made to the purchaser.
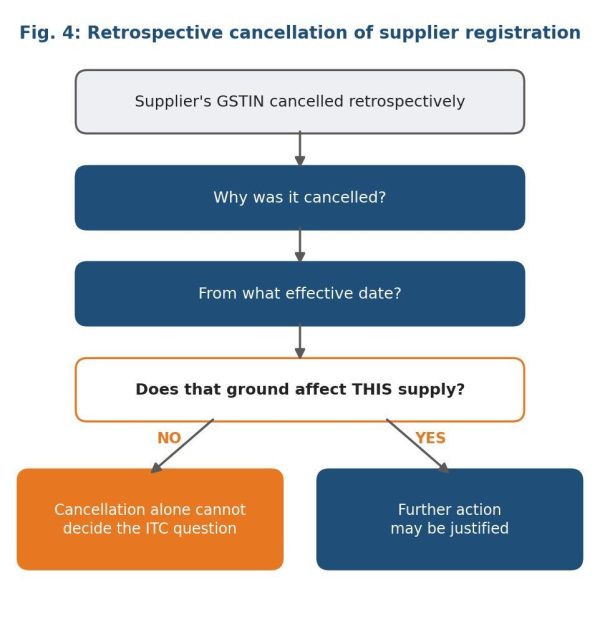
The ruling thus discourages the habit of treating retrospective cancellation as conclusive proof that every earlier transaction of that supplier was fictitious.
Guideline VIII: Proceedings against the supplier matter
The Court gives real weight to the remedies available against the defaulting supplier. The proper officer must ascertain and record the status of proceedings against the seller. Where the supplier falls under another Central or State jurisdiction, the officer should communicate with the concerned jurisdictional officer.
More significantly, if tax on the same supply has already been recovered from, or deposited by, the supplier, that must be recognised so that the same tax is not realised twice. Credit may then be re-availed to the extent permitted by Section 41(2), Rule 37A and other applicable provisions, subject to Section 17(5)(i).
This part of the judgment reads the GST law as an integrated statutory scheme, and not Section 16(2)(c) in isolation.
Guidelines IX–XIV: Period-wise Law, Registration and Procedure
Guideline IX: Different tax periods require different law
One of the technically strongest parts of the judgment is its recognition that the ITC provisions have changed substantially over time. The Court identifies three phases.
| Period | Statutory position highlighted by the Court |
|---|---|
| Before 01.10.2022 | Original Section 41 operated; Sections 42/43 remained on the statute book but were never operationalised; no mechanism for re-availment of reversed credit existed |
| From 01.10.2022 | Section 41 substituted; Sections 42/43 omitted; clause (ba) inserted in Section 16(2) |
| From 26.12.2022 | Rule 37A introduced in the CGST Rules |
The Court cautions that a condition or mechanism brought in by a later amendment cannot be applied to an earlier tax period. It names clause (aa) of Section 16(2), effective from 01.01.2022, in this connection. For periods before 26.12.2022, the absence of a re-availment mechanism must be kept in mind when deciding the consequence of the supplier’s default.
This direction can have a substantial bearing on pending ITC disputes for earlier financial years.
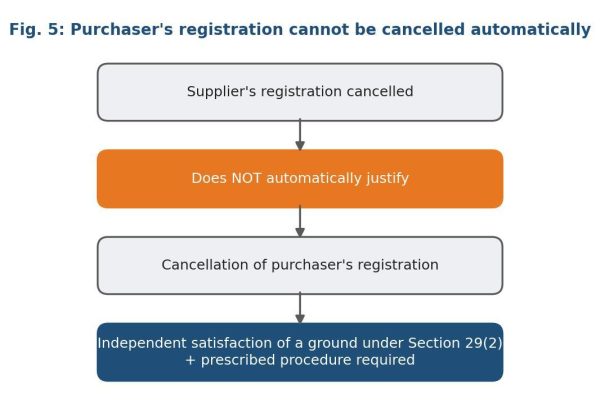
Guideline X: The purchaser’s registration cannot be cancelled automatically
The purchaser’s registration, particularly with retrospective effect, cannot be cancelled merely because ITC was availed from a supplier whose registration was later cancelled. The officer must be independently satisfied that a ground under Section 29(2) exists, and must then follow the prescribed procedure.
Guideline XI: Personal hearing and cross-examination
The Court reaffirms Section 75(4), and a personal hearing must be granted. Where statements of third persons are relied upon and the noticee seeks cross-examination, the officer must consider the request and decide it by a reasoned order, keeping in view whether those statements form the basis of the proposed action.
Cross-examination has not been declared automatic in every case. What the Court requires is reasoned consideration of the request, depending on the evidentiary role of the statement.
Guideline XII: A speaking order is not optional
Flowing from Section 75(6), the final order must:
- state the relevant facts;
- state the basis of the decision;
- deal with the taxpayer’s reply;
- consider the documents produced;
- give a finding on each disputed condition of Section 16(2); and
- where Section 74 is invoked, specifically establish the fraud, wilful misstatement or suppression attributable to the noticee.
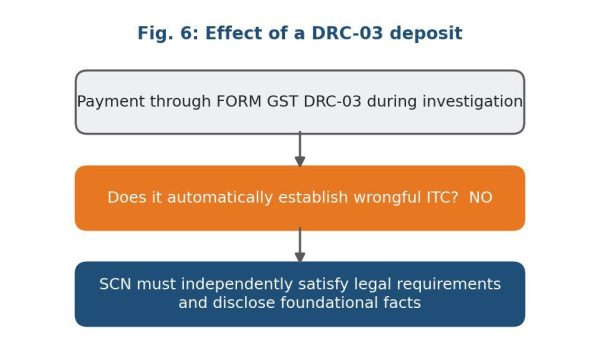
Guideline XIII: DRC-03 payment is not an admission of fraud
A further practical clarification concerns payments made during investigation. A deposit through FORM GST DRC-03, or otherwise, does not relieve the Department of the duty to issue a legally sustainable notice containing foundational facts. The nature and effect of the deposit are to be determined on the facts of each case.
Guideline XIV: Pending and future proceedings
This is perhaps the most consequential direction. The guidelines govern all proceedings pending before proper officers as well as those initiated afterwards.
The principles are therefore not confined to the petitioners in the batch. At least within the territorial jurisdiction of the Punjab & Haryana High Court, pending proceedings under Section 16(2)(c) must be approached within the framework this judgment prescribes.
5. Relief Granted in the Connected Petitions
Interestingly, the High Court did not simply quash every notice and order. It devised a remedial mechanism instead.
| Stage of proceeding | Direction of the Court |
|---|---|
| SCN pending | Taxpayer may file a reply or supplementary reply, with material, within eight weeks |
| SCN lacks particulars or material | Proper officer must supply them |
| New ground introduced through supplementary notice or corrigendum | Taxpayer can object; the objection must be decided |
| Order already passed | Proper officer must revisit the matter after a personal hearing and pass a fresh reasoned order |
| Existing impugned orders | Not formally interfered with, but made subject to fresh orders |
| Amount already deposited or recovered | To abide by the fresh decision; adjustment or refund with admissible interest where warranted |
| Recovery | No fresh coercive action until the fresh decision |
| Merits | All factual and legal pleas kept open |
| Proceedings against supplier | Department remains free to proceed in accordance with law |
A noteworthy feature is that the Court did not decide the genuineness of each transaction itself. It sent that exercise back to the statutory proper officer, while imposing a structured discipline on how the decision is to be reached.
6. Systemic Reforms Suggested by the Court
The judgment looks beyond individual adjudication and identifies several measures that the Government and the GST Council may wish to consider.
| Suggested measure | Objective |
|---|---|
| Immediate portal alert when cancellation proceedings commence against a supplier | Let recipients know supplier risk in real time |
| Invoice-wise real-time verification of tax payment | Enable the buyer to verify Section 16(2)(c) compliance |
| Alerts where a supplier defaults under Rule 86B | Early identification of risk |
| Random physical verification of registrations at threshold | Curb fake registrations |
| Biometric / PAN / Aadhaar authentication | Strengthen identity verification |
| Possible RCM for supplies such as scrap from the unorganised sector | Address recurring tax leakage |
The Court was careful to describe these as policy matters within the domain of the Government and the GST Council, and it issued no mandamus for their implementation. That restraint is itself legally significant.
7. A Practical Framework After Shaurya Alloys
For the Department
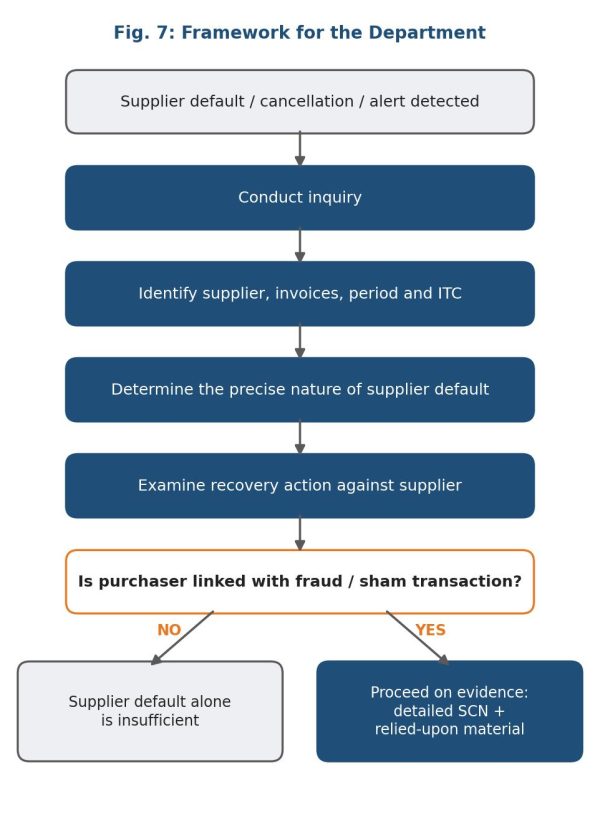
–
For the Taxpayer
8. The Larger Significance
The judgment tries to reconcile two competing considerations.
On one side, ITC is a statutory entitlement subject to conditions. The purchasing dealer continues to carry the burden under Section 155, and bogus transactions remain exposed to the full consequences.
On the other, Section 16(2)(c) cannot serve as a shortcut by which every supplier-side default is passed mechanically to the recipient, without any inquiry into the transaction or the purchaser’s own conduct.
The approach can be put in three propositions:
| Supplier default is relevant evidence; it is not automatic proof of purchaser default. |
–
| Retrospective cancellation may trigger investigation; it does not retrospectively convert every genuine transaction into a sham transaction. |
–
| Fraud must be alleged against the person whose conduct is sought to be penalised, and not borrowed from the conduct of somebody else. (in cases involving Section 74) |
Conclusion
Shaurya Alloys is likely to become an important authority in GST litigation on supplier default and ITC reversal.
Its main contribution is procedural, but a profound one: the Department is required to move from database-driven conclusions to evidence-driven adjudication.
The judgment does not give a purchasing dealer unconditional ITC. Section 16(2)(c), Section 155 and the Department’s power to investigate fraudulent transactions all survive. What the Court insists on is that, before credit is denied, the proper officer must identify the supplier’s default, examine its relevance to the specific transaction, disclose the evidence, weigh the purchaser’s proof, look at recovery against the supplier, apply the law as it stood for the relevant period, and finally pass a reasoned order.
For genuine purchasers, then, the judgment is not an exemption from Section 16(2)(c). It is something more basic: a judicially structured right to have Section 16(2)(c) administered in accordance with the statute and not through presumption alone.