
Kavya Boppana Vs ACIT (ITAT Hyderabad)
ITAT Hyderabad deleted penalty of Rs.74,35,500 levied under Section 271AAB(1A)(b) of the Income Tax Act at 60% of alleged undisclosed income, holding that the penalty proceedings were founded on an invalid show-cause notice. During a search conducted in the Skill Promoters Pvt. Ltd. Group, material indicating cash payments towards purchase of agricultural land was found and the assessee disclosed Rs.1,23,92,500 under “Income from other sources” in her return for AY 2020-21.
The Assessing Officer treated the amount as unexplained investment under Section 69 and sought taxation under Section 115BBE, besides initiating Section 271AAB proceedings. The Tribunal found that the notice issued under Section 274 read with Section 271AAB did not specify the particular clause or category under which penalty was proposed. Following the Madras High Court ruling in PCIT v. R. Elangovan, it held that Section 271AAB contemplates different contingencies carrying different rates and the assessee must be informed of the precise charge to enable an effective response.
The Tribunal also noted that in the assessee’s quantum appeal it had already reversed the treatment of the disputed amount as unexplained investment and directed that it be assessed as “Income from other sources” at the normal rate. It further relied upon Ashok Bhatia v. DCIT, where an unspecified Section 271AAB charge was held to render the notice defective. Since the Assessing Officer failed to identify the applicable charge and category in the show-cause notice, initiation of penalty proceedings itself was invalid and the consequential penalty order stood vitiated. The assessee’s appeal was accordingly allowed.
Cases Discussed
- PCIT-1, Coimbatore v. Shri R. Elangovan, Tax Case Appeal Nos. 770 & 771 of 2018 & CMP No.18581 of 2018, dated 30.03.2021 (Madras High Court) — Directly followed. The High Court held that Section 271AAB contains different contingencies and the Assessing Officer must specify the particular clause under which penalty is proposed; an unspecified and vague notice denies reasonable opportunity and vitiates the penalty.
- Shri Ashok Bhatia v. DCIT, Central-1, Indore, ITA No.869/Ind/2018, dated 05.02.2020 (ITAT Indore) — Followed on the validity of a notice under Section 274 read with Section 271AAB. Failure to specify the applicable charge under Section 271AAB rendered the notice defective and invalid.
- PCIT v. Sandeep Chandak, (2018) 93 taxmann.com 405 / 405 ITR 648 (Allahabad High Court) — Distinguished in R. Elangovan. Admission of undisclosed income during search may attract Section 271AAB, but it does not dispense with the requirement that the Assessing Officer specify the particular clause under which penalty is proposed.
- CIT v. Manjunatha Cotton and Ginning Factory, (2013) 359 ITR 565 (Karnataka High Court) — Relied upon in R. Elangovan in support of the requirement that a penalty notice clearly specify the applicable charge.
- CIT v. SSA’s Emerald Meadows, (2016) 73 taxmann.com 241 (Karnataka High Court) — Relied upon in R. Elangovan on the invalidity of a penalty notice that fails to specify the relevant statutory limb.
- Babuji Jacob v. ITO, Non Corporate Ward 1(2), Chennai, (2021) 124 taxmann.com 363 (Madras High Court) — Relied upon in R. Elangovan as supporting the conclusion that defective specification of the penalty charge vitiates the proceedings.
- PCIT v. Kulwant Singh Bhatia — Referred to in the passage reproduced from Ashok Bhatia regarding validity of an unspecified penalty notice.
- DCIT v. R. Elangovan (ITAT Chennai) — Referred to in Ashok Bhatia in support of the proposition that a vague Section 274 read with Section 271AAB notice cannot sustain penalty.
- Ravi Mathur v. DCIT (ITAT Jaipur) — Referred to in Ashok Bhatia on the requirement that the Section 271AAB penalty notice specify the default and charge.
FULL TEXT OF THE ORDER OF ITAT HYDERABAD
This appeal by the Assessee is directed against the Order dated 07.07.2025 of the learned Commissioner of Income Tax-(Appeals)-12, Hyderabad, arising from penalty order passed by the Assessing Officer u/sec.271AAB of the Income Tax Act [in short “the Act”], 1961, for the assessment year 2020-2021.
2. Brief facts of the case emanating from the record are that the assessee is individual deriving income from house property and income from other sources. For the assessment year 2020-2021, the assessee filed her return of income under section 139(1) of the Act on 10.01.2021, declaring total income of Rs.3,02,28,230/-. A search and seizure operation under section 132 of the Act was conducted on 22.10.2019 in the case of M/s Skill Promoters Pvt. Ltd. Group, in which the assessee was also covered. Pursuant to the search, the jurisdiction of the case was centralized vide order under section 127 of the Act dated 29.11.2019. The case was selected for scrutiny and assessment under section 143(3) was completed on 28.09.2021, determining the total income at Rs.3,02,28,230/-. During the search, incriminating material indicating cash payments for purchase of agricultural land at Mamidipally village was found and seized. The assessee’s father viz., Shri Sarat Gopal Boppana, in his statement recorded under section 132(4) of the Act admitted that cash payments were made by family members, including the assessee, over and above the SRO value. Consequently, the assessee disclosed a sum of Rs.1,23,92,500/- under the Head “Income from other sources” in her return of income. However, the Assessing Officer held that the said income represented unexplained investment under section 69 of the Act and was liable to be taxed under section 115BBE of the Act. Penalty proceedings under section 271AAB were accordingly initiated, and the Assessing Officer ultimately levied a penalty of Rs.74,35,500/- under section 271AAB(1A)(b), being 60% of the alleged undisclosed income. The assessee challenged the penalty order passed u/sec.271AAB of the Act before the learned CIT(A) but could not succeed.
3. The learned Authorised Representative of the Assessee has submitted that the impugned order passed u/sec.271AAB is not sustainable in law as the show cause notice issued by the Assessing Officer u/sec.274 r.w.s.271AAB of the Act is invalid as the Assessing Officer has not specified the charge, under which of the clause of sec.271AAB(1A) of the Act, the penalty was proposed to be levied by the Assessing Officer. In support of this contention, he has relied upon the Judgment of Hon’ble Madras High Court in the case of f Pr. CIT-1, Coimbatore vs. Shri R. Elangovan in Tax Case Appeal Nos.770 & 771 of 2018 & CMP.No.18581 of 2018, Dated 30.03.2021. He has also relied upon decision of ITAT, Indore Bench of the Tribunal dated 05.02.2020 in the case of Shri Ashok Bhatia, Indore vs. DCIT, Central-1, Indore in ITA.No.869/Ind./2018, Dated 05.02.2020 and submitted that the show cause notice issued by the Assessing Officer for initiation of the penalty proceedings u/sec.271AAB of the Act does not specify the default of the assessee attracting the penalty u/sec.271AAB(1) under clauses-(a) (b) and (c) of the said sub- section. The learned Authorised Representative of the Assessee has referred to the show cause notice dated 28.09.2021 issued by the Assessing Officer and submitted that the Assessing Officer has not specified under which clause of sec.271AAB(1)/(1A) of the Act the penalty is proposed to be levied and therefore, in the absence of specific charge and rate of penalty to be levied, the initiation of the penalty is invalid. It also vitiates the impugned order passed u/sec.271AAB of the Act. He has further submitted that in the quantum appeal the Tribunal has converted the addition made by the Assessing Officer u/sec.69A r.w.s.115BBE of the Act and confirmed the addition as income from other sources attracting only normal tax at 30%. Therefore, the penalty u/sec.271AAB is not attracted on the income declared and offered to tax by the assessee in the return of income under the head “Income from other sources”.
4. On the other hand, the learned DR has submitted that the Judgment of Hon’ble Madras High Court in the case ofPr. CIT-1, Coimbatore vs. Shri R. Elangovan (supra),is not applicable in the case of the assessee because in the said case the assessee did not file any return of income u/sec.139 of the Act and the addition was made by the Assessing Officer whereas in the case in hand, there is no dispute about the incriminating material found during the course of search and seizure action and undisclosed income declared and offered to tax by the assessee. He has relied upon the Orders of the authorities below.
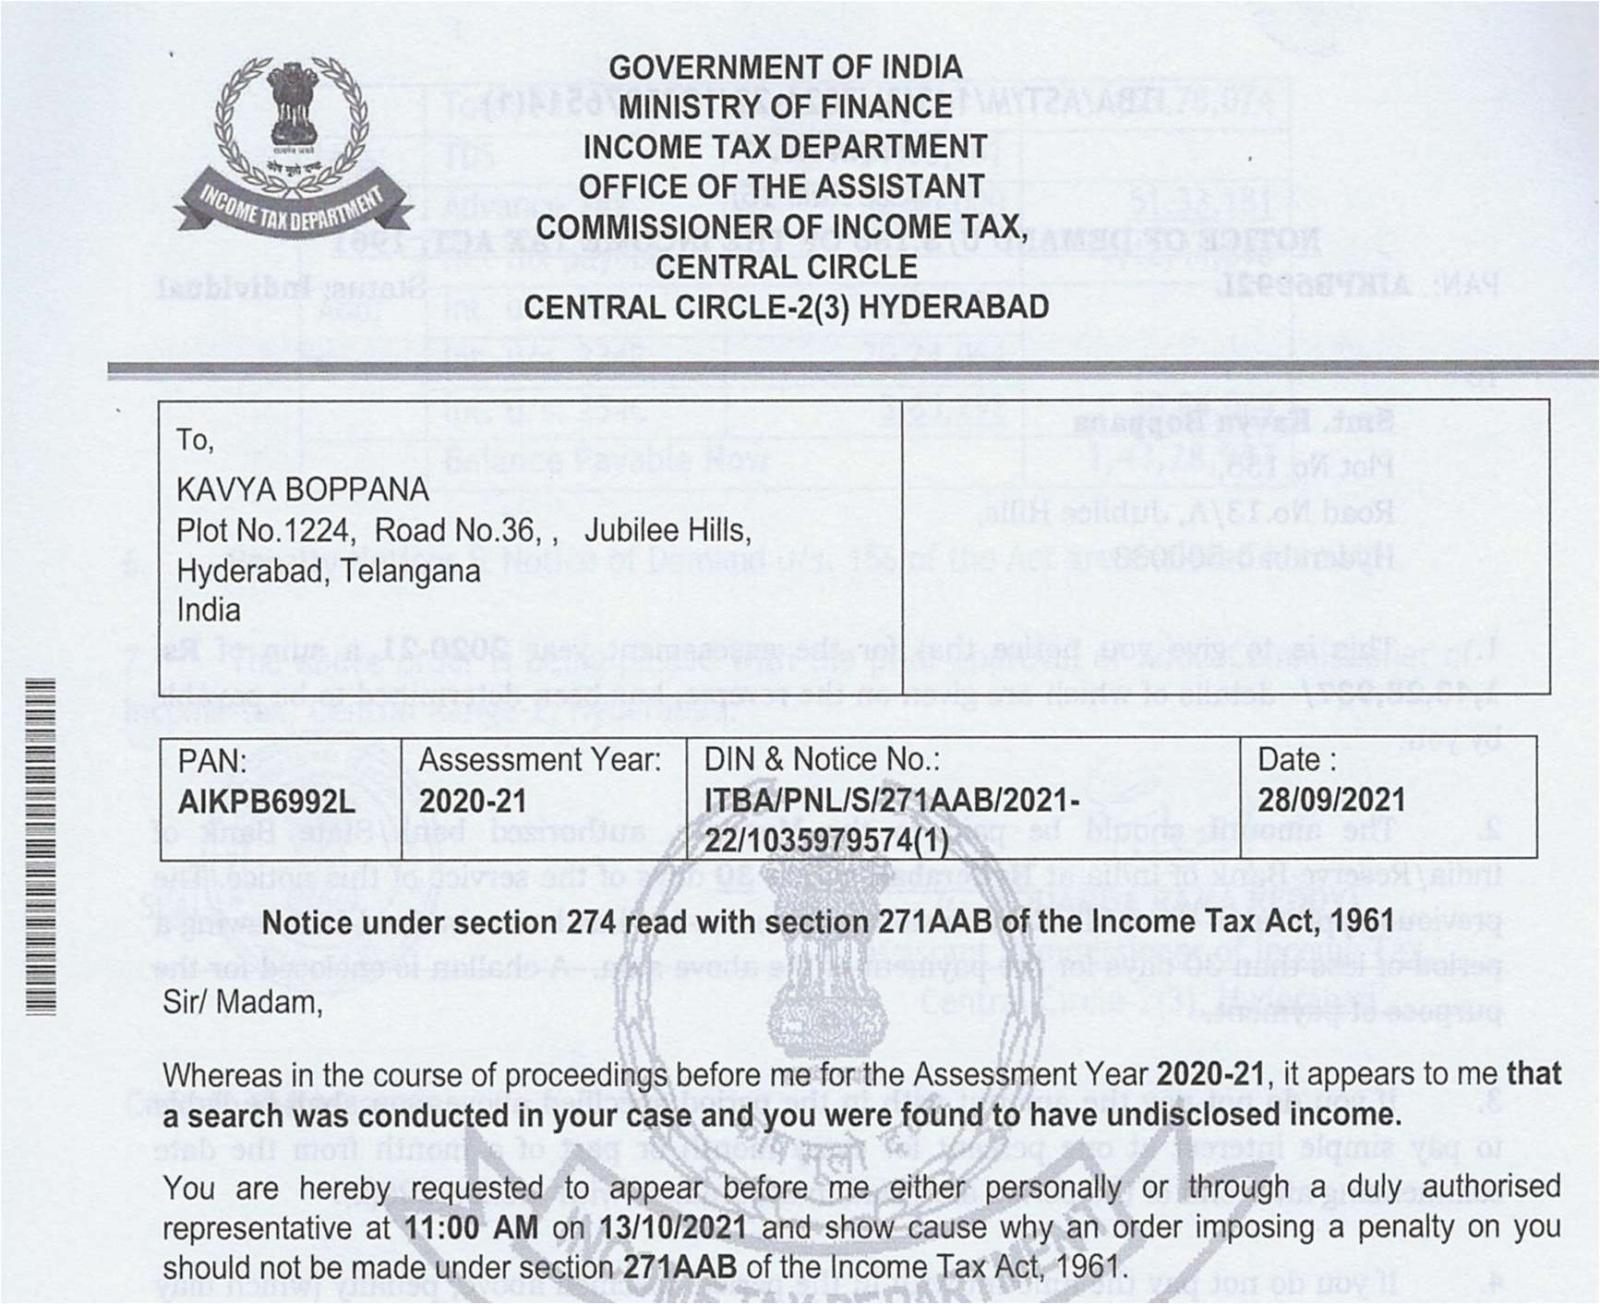
5. We have considered the rival submissions as well as relevant material on record. There is no dispute that during the course of search and seizure action the transactions of cash payments for purchase of property were detected which were also offered to tax by the assessee in the return of income against which the Assessing Officer has initiated the proceedings for levy of penalty u/sec.271AAB of the Act by issuing show cause notice dated 28.09.2021 which reads as under:
–
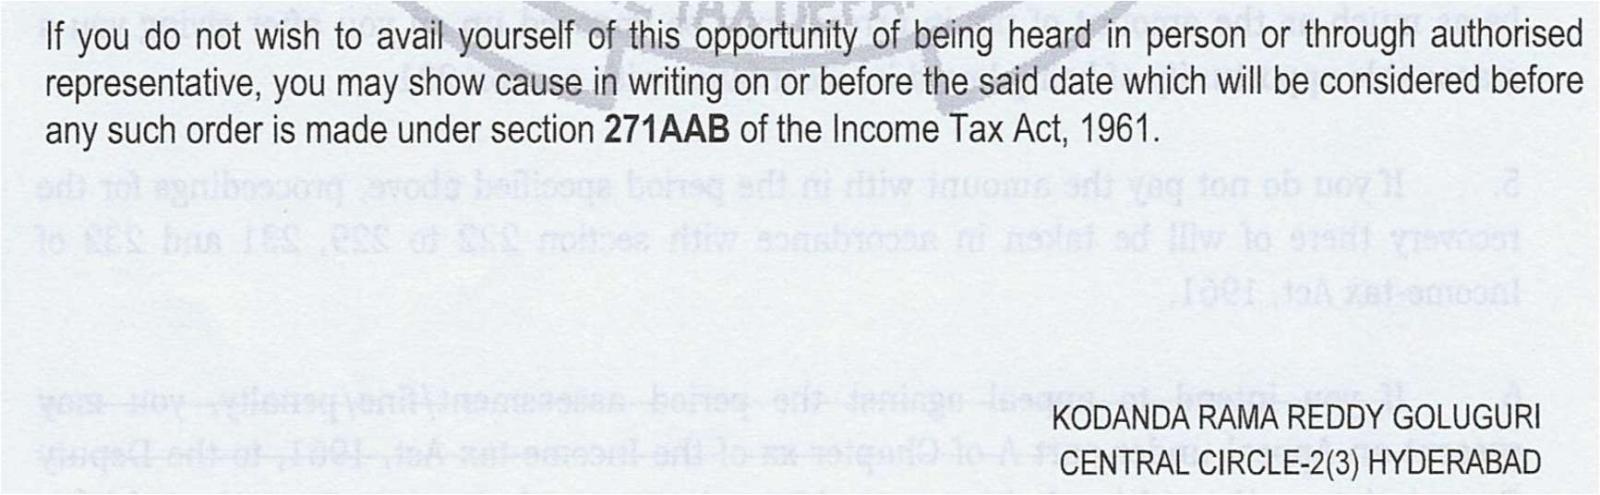
5.1. Thus, it is clear that the Assessing Officer has not specified under which clause of sec.271AAB(1) of the Act the penalty was proposed to be levied in respect of the income offered by the assessee to tax. Sec.271AAB(1A) clause (a) and (b) of the Act contemplates the penalty at 30% and 60% respectively, in respect of two contingencies attracting the penalty u/sec.271AAB of the Act. The Hon’ble Madras High Court in the case of Pr. CIT-1, Coimbatore vs. Shri R. Elangovan (supra), has considered an identical issue and held in Para nos.14 to 17 as under:
“14. In our considered view, the Tribunal is fully right in vacating the penalty on the ground that the notice defective. The provisions of the Act have clearly laid down the procedure to be followed and adhered to while imposing the penalty. The proposal for such penalty proceedings separately initiated upon completion of assessment and there may be cases where the assessee would not even contest the order of assessment. But, that would not preclude the assessee from challenging the penalty proceedings, as penalty proceedings are independent and the procedure required to be followed cannot be dispensed with.
15. As rightly pointed out by the learned counsel appearing for the assessee, Section 271AAB of the Act, which deals with penalty consists of three contingencies. Therefore, Assessing Officer should point out to the assessee as to under which of the three clauses, he chooses to proceed against the assessee so as to enable the assessee to give an effective reply. Since the same has not been mentioned, the assessee has been denied reasonable opportunity to put forth submissions. The Tribunal, in paragraph 5 of the impugned order, has verbatim reproduced the penalty notice and we find that the notice is absolutely vague and none of the irrelevant portions had been struck off nor the relevant portions had been marked or indicated. Hence, the Tribunal is right in observing that the penalty could not have been levied based on such defective notice and more particularly, when the assessee has been strenuously canvassing the jurisdictional issue from inception.
16. In so far as the decision of the Allahabad High Court in the case ofSandeep Chandakis concerned, the factual position is slightly different. This decision is for the principle that where the assessee, in the course of search, makes a statement, in which, he admits the undisclosed income and specifies the manner, in which, such Income has been derived, then the provisions of Section 271AAB of the Act would automatically get attracted. There can be no quarrel over this proposition. But, once the provisions get attracted, it is incumbent on the part of the Assessing officer to specify as to under which clause in Section 271AAB (1) of the Act, he intends to proceed against the assessee. In the instant case, in the absence of such material in the penalty notice, it has to be held that the notice is defective.
17. The decisions of the Karnataka High Court in the cases of Manjunatha Cotton and Ginning Factory and SSA’s Emerald Meadows and the decision of this Court in the case of Babuji Jacob clearly support our above conclusion. For all the above reasons, we find no grounds to interfere with the common order passed by the Tribunal.”
5.2. It is also pertinent to note that in the quantum appeal this Tribunal vide Order dated 27.06.2024 in ITA.No.696/Hyd./2022 has held in Para nos.24.6 to 24.9 as under:
“24.6. Heard both the parties, perused the material available on record and have gone through the orders of authorities below. There is no dispute with regard to the fact that loose sheets found during the course of search revealed cash payment for purchase of the property by the assessee. In fact, Shri Sarat Gopal Boppana, father of assessee has admitted in his statement that cash payment has been made by his children for purchase of property at Mamidipalli Village. It is also an admitted fact that the assessee has declared total income of Rs.3,02,23,230/ which includes sum Rs. 1,23,92,500/- income from other sources for A.Y. 2020-21. The due date for closure of books of accounts or filing of return of income for A.Y. 2020-21 was not due or expired as on the date of search i.e., 22.10.2019. Admittedly, the assessee is deriving income from house property and income from other sources and does not have income from business or profession. Therefore, the income declared by the assessee under the head income from other sources and assessed by the Assessing Officer as unexplained investment u/s 69A of the Act and taxing u/s 115BBE of the Act needs to be examined in light of the above facts. If the assessee is not carrying out any business or specified profession, then the assessee need not to maintain any books of accounts.
24.7. In the present case, the assessee is neither carrying out any business activity nor involved in any specified profession. Therefore, the arguments of the assessee that she needs not to maintain books of accounts for the impugned assessment year is acceptable. Once, the assessee needs not to maintain books of accounts, then the question of recording any investment in books of accounts for any assessment does not arise. Further, when the due date for filing of return of income was not offered or due, then it cannot be presumed that the assessee would not have disclosed the said income for the purpose of tax. Since the assessee is not required to maintain any books of accounts for the impugned assessment year and further, the due date of return of income was not expired as on the date of search, in our considered opinion, the explanation offered by the assessee regarding source for cash payment for the purchase of the property needs to be accepted. The assessee declared income to an extent of Rs.1,23,92,500/-, in respect of cash payment for purchase of property as income from other sources and paid taxes.
24.8. Therefore, in our considered opinion, the Assessing Officer and Id.CIT(A) are erred in treating income declared under the head ‘income from other sources’ as unexplained investment u/s 69 and brought it to tax under Section 115BBE of the Act. Further, the provisions of Section 69 can be invoked whether in the financial year, immediately preceding the assessment year, the assessee has made investments, which are not recorded in the books of accounts, if any, maintained by her from any source of income, and the assessee offers no explanation about the nature and source of investment or the explanation offered by the assessee is satisfactory in the opinion of the Assessing Officer, then the value of the investment may be deemed to be the income of the assessee of such financial year.
24.9. In the present case, the conditions for invoking provisions of section 69 of the Act are not satisfied. Therefore, we have to consider that the Assessing Officer and ld. CIT(A) are erred in invoking the provisions of section 69 r.w.s. 115BBE of the Act, in respect of income declared under the head ‘income from other sources’. Thus, we reverse the findings of the Id.CIT(A) and direct the Assessing Officer to assess the income under the head income from other sources’ as declared by the assessee.”
5.3. Thus, the stand of the Assessing Officer in assessing the income offered by the assessee to tax u/sec.69A r.w.s.115BBE of the Act has been reversed by this Tribunal and considered the said income as taxable at normal rate of 30% under the Head “Income from other sources”.
Therefore, once the Order of the Assessing Officer treating the income as unexplained investment u/sec.69A of the Act is reversed by this Tribunal, then, the Assessing Officer was required to specify the charges and default on the part of the assessee for levy of the penalty u/sec.271AAB of the Act. This issue of validity of show cause notice u/sec.274 r.w.s.271AAB of the Act was also considered by the Indore Bench of the Tribunal in the case ofShri Ashok Bhatia, Indore vs. DCIT, Central-1, Indore in ITA.No.869/Ind./2018 dated 05.02.2020 in Para no.15 as under: “15. We, therefore respectfully following the judgment of jurisdictional High Court in the case of PCIT V/s Kulwant Singh Bhatia (supra), decision of Co-ordinate Bench of Chennai in the case of DCIT V/s R. Elangovan (supra) and Jaipur Bench in the case of Ravi Mathur Vs DCIT (supra) and in the given facts and circumstances of the case wherein the matter written in the body of the notice issued u/s 274 of the Act does not refer to the charges of provision of Section 271AAB of the Act makes the alleged notice defective and invalid and thus deserves to be quashed. Since the penalty proceedings itself has been quashed the impugned penalty of Rs.64,22,348/- stands deleted. Thus assessee succeeds on legal ground challenging the validity of notice issued u/s 274 r.w.s. 271AAB of the Act.”
5.4. Accordingly, in the facts and circumstances of the case, when the Assessing Officer has not specified the charge and the category under which the penalty was proposed to be levied in the show cause notice, then, the said show cause notice suffers from irreparable infirmities and illegalities. Hence, the initiation of the penalty itself is invalid, then the
Order for levy of penalty u/sec.271AAB of the Act also got vitiated. Accordingly, the penalty levied by the Assessing Officer u/sec.271AAB of the Act is not sustainable in law and the same is deleted.
6. In the result, appeal of the Assessee is allowed.
Order pronounced in the open Court on 25.03.2026.








