
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

No Section 56 Addition as Property Value Difference Was Within 10% Tolerance Band

SC Upholds Reassessment Quash Order Due to Mere Suspicion Without ‘Reason to Believe’

Calcutta HC Quashes Reassessment Due to Mere Suspicion Without Independent Inquiry

Section 40(a)(ia) Disallowance Invalid for Mere Short Deduction of TDS: Bombay HC

Agricultural Land Cannot Be Treated as Capital Asset Due to Subsequent Commercial Use by Purchaser: ITAT Hyderabad

Share Premium Received Through Verified Investors Cannot Be Treated as Bogus Cash Credit: ITAT Delhi
Section 69A Addition Upheld Because Assessee Failed to Explain Source of ₹7.5 Cr Cash: ITAT Delhi

ITAT Quashes Section 263 Revision as AO Conducted Detailed Inquiry into Agricultural Income
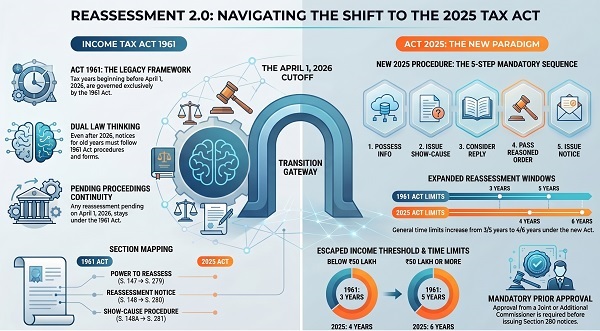
Reassessment 2.0: New Tax Notice Playbook Every Tax Professional Must Decode
ITAT Delhi Deletes Capital Addition as No Liability Cessation Was Proved

ITAT Quashes Assessment Due to Non-Supply of Search Material
Third-Party Loose Papers Cannot Justify Addition Without Cross-Examination: ITAT Delhi
Section 56(2)(x) not Apply to Redevelopment Flats as Transaction Is Exchange of Existing Rights
Bombay HC Quashes Reassessment Due to Approval by Wrong Authority
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

