
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Undisclosed CBEC Import Data Cannot Sustain ₹302.27 Crore Addition: Bombay HC

Vivad Se Vishwas Settlement of Original Assessment Cannot Close Reassessment Appeal: ITAT Mumbai

Who Pays When Agent Earns? Autonomous AI and Attribution Gap in Indian Tax Law

Husband’s Gift, Wife’s Tax: ITAT Rejects Clubbing Claim Over Delayed Disclosure: ITAT Hyderabad

When Does GST Become Payable? Levy, Time of Supply, RCM & Composition
Can WhatsApp Chats, Excel Sheets and Seized Phones Alone Justify a Tax Addition?

Profit Split Method in Transfer Pricing: Applicability, Calculation & Key Cases

Resolving Two-Time PAN Modification Barrier in TDS Returns: Nominal Value Strategy
UK UTPP 2026: When a Transfer Pricing Error Can Turn 25% Corporation Tax Into 31%
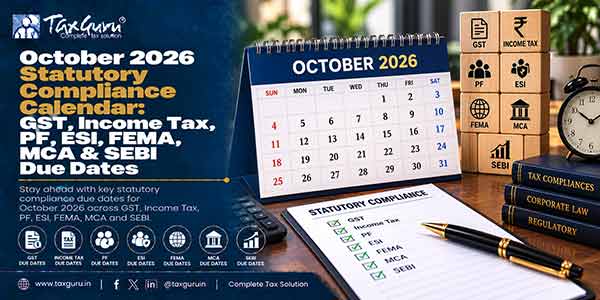
October 2026 Statutory Compliance Calendar: GST, Income Tax, PF, ESI, FEMA, MCA & SEBI Due Dates

Further Investigation Alone Does Not Justify Custodial Interrogation: Telangana HC
Alleged Flat “On-Money”: Show-Cause Notices Cannot Replace Cross-Examination: Agra ITAT
Partner Remuneration Not Gross Receipts for Section 44ADA: ITAT Mumbai
Political Donation Withdrawal Does Not Automatically Justify 200% Section 270A Penalty: ITAT Ahmedabad
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

