Mohammad Fajlur Haque Vs Commissioner of CGST and Central Excise (CESTAT Kolkata)
Summary: The Kolkata Bench of the Customs, Excise and Service Tax Appellate Tribunal allowed the appeal of Mohammad Fajlur Haque against confirmation of service tax of Rs.11,11,528, including cess, together with interest and penalty. The appeal arose from Order-in-Appeal No.34/SLG-ST/2023-24 dated 03.05.2023, which upheld the adjudication order dated 27.01.2022. The dispute related to works contract services rendered during financial year 2014-15. The appellant, registered for works contract services, worked as a subcontractor of Simplex Infrastructure Limited. The principal contract concerned construction of residential accommodation for Junior Commissioned Officers and Other Ranks under the Director General of Married Accommodation Project, Ministry of Defence. The appellant maintained that the construction was covered by the service tax exemption available to the principal contractor and, correspondingly, to an eligible works contract subcontractor. The Revenue initiated proceedings after comparing Form 26AS with the appellant’s ST-3 returns. On receipts of Rs.89,92,942, it alleged non-payment of service tax of Rs.11,11,528 and issued a show cause notice dated 17.10.2019. The lower authorities confirmed the demand. The Revenue argued before the Tribunal that the appellant had not furnished sufficient particulars of the Ministry of Defence work order to the authorities below.
The Tribunal examined Work Order No. WO26252625/120101011 dated 01.01.2012, issued by Simplex Infrastructure Limited for construction of 20 dwelling units for Junior Commissioned Officers and 20 dwelling units for Other Ranks at the Sevoke Road site. It found that the work related to residential accommodation under the Ministry of Defence and that the main contractor qualified for exemption under Serial No.12 of Notification No.25/2012-ST dated 20.06.2012. The Tribunal further applied Serial No.29(h) of the same notification, which extends exemption to a subcontractor providing works contract services to another contractor whose works contract services are exempt. Since the main contractor’s work was exempt, the Tribunal held that the appellant was also eligible for the exemption. The demand was accordingly unsustainable on merits.
Independently, the Tribunal accepted the limitation objection. The notice dated 17.10.2019 concerned FY 2014-15 and invoked the extended period. The demand had been founded on income-tax data and Form 26AS without an independent investigation establishing the taxable nature of the services or corroborating the alleged suppression. No evidence demonstrated wilful misstatement or suppression with intent to evade service tax.
Consequently, the Tribunal set aside the demand both on the exemption ground and as barred by limitation. As the principal demand did not survive, interest and penalty were also set aside. The appeal was allowed with consequential relief, if any, in accordance with law.
FULL TEXT OF THE CESTAT KOLKATA ORDER
The present appeal has been filed against the Order-in-Appeal No. 34/SLG-ST/2023-24 dated 03.05.2023 wherein the Service Tax demand of Service Tax of Rs.11,11,528/- (inclusive of cess), along with interest and penalty, as confirmed in the Order-in-Original No. 01/AC/ST/MLDN/2022 dated 27.01.2022, has been upheld.
2. The facts of the case are that M/s. Mohammad PIN – 732 125 (hereinafter referred to as the “appellant”) is an individual firm, holding Service Tax Registration for the provision of services, namely, works contract services. The appellant was engaged in providing the said works contract services to M/s. Simplex Infrastructure Ltd. who received the contract from the Director General of Married Accommodation Project (DGMAP), Ministry of Defence.
3. On the basis of an enquiry and scrutiny of the Form 26AS vis-à-vis ST-3 Returns of the appellant for the Financial Year 2014-15, it was gathered by the Revenue that although the appellant had received a taxable value amounting to Rs.89,92,942/-, they had not discharged the Service Tax liability on such amount received by them during the said period, resulting in non-payment of Service Tax to the tune of Rs.11,11,528/- (inclusive of cess).
4. Pursuant to the above, a Show Cause Notice dated 17.10.2019 was issued proposing to demand the Service Tax of Rs.11,11,528/- (inclusive of cess) from the appellant, along with interest and penalty under Section 78 of the Finance Act, 1994, by invoking Section 73(1) of the Finance Act, 1994.
4.1. The above Show Cause Notice was adjudicated by the Ld. Assistant commissioner, C.G.S.T. and C.Ex., Malda Division vide the Order-in-Original dated 27.01.2022, wherein the lower adjudicating authority has confirmed the demands of Service Tax, along with applicable interest and penalty, as proposed.
4.2. The appellant challenged the above adjudication order before the Ld. Commissioner of C.G.S.T. and C.Ex. (Appeal), Siliguri Appeal Commissionerate, who vide the impugned order dated 03.05.2023 has upheld the demands confirmed by the ld. adjudicating authority in the Order-in-Original dated 27.01.2022.
4.3. Aggrieved by the confirmation of the above demand of Service Tax, along with interest and penalty, the appellant has filed the instant appeal.
5. It is the case of the appellant that the contract of M/s. Simplex Infrastructure Ltd. for rendering the construction of Block of 20 (twenty) dwelling units for Junior Commissioned Officers (JCOs) and 20(twenty) dwelling units for Other Ranks (ORs) under the Ministry of Defence were exempt from the purview of Service Tax as provided under Notification No. 25/2012-S.T. dated 20.06.2012; that Sl. No. 29(h) of the said Notification provides exemption to the sub- contractor providing the service by way of works contract service when such services are exempted for the main contractor. Accordingly, it is the contention of the appellant that since the services are rendered by them to M/s. Simplex Infrastructure Ltd., who in turn receive the work order from the Ministry of Defence, the said services i.e., construction of dwelling units for officers at Sevoke Road and Sukuna outlet are exempt from the levy of Service Tax in terms of the above Notification.
6. On the other hand, the Ld. Authorized Representative of the Revenue reiterates the findings in the impugned order. He contends that the appellant has not furnished the details regarding the work order received from the Ministry of Defence before the lower authorities and thus, justifies the demands confirmed vide the impugned order.
7. Heard both sides and perused the records of the case.
8. I find that the appellant has received the Work Order No. WO26252625/120101011 dated 01.01.2012from the main contractor, namely, M/s. Simplex Infrastructure Limited, for the construction of Block of 20 (twenty) dwelling units for Junior Commissioned Officers (JCOs) in (S+5) and 20(twenty) dwelling units for Other Ranks (ORs) in (S+5) RCC framed structure in above and below Plinth Level Work, as shown on drawing and as specified in work order at Sevoke Road site. For better appreciation of the facts, the relevant portion of the said Work Order dated 01.01.2012 is reproduced hereinbelow: –
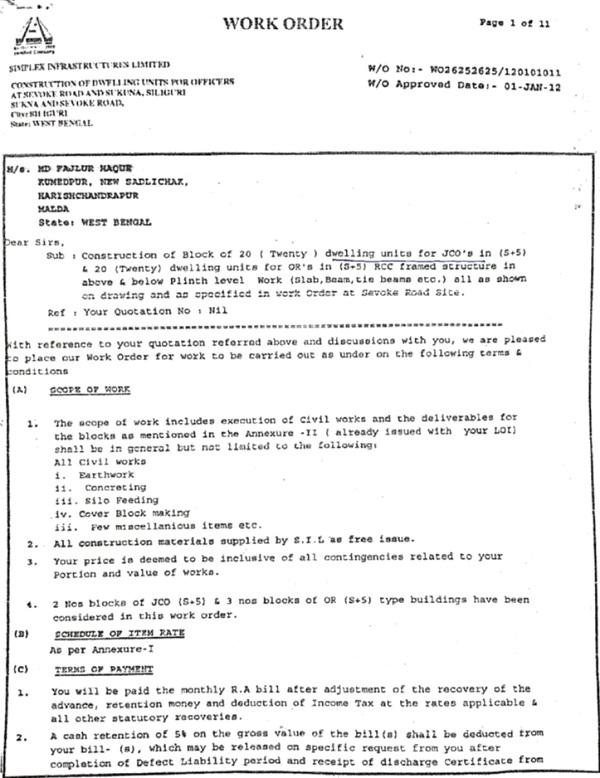
8.1. A perusal of the above indicates clearly that the appellant has rendered the said services to the main contractor, namely, M/s. Simplex Infrastructure Ltd.in relation to construction of dwelling units for JCOs / ORs under the Ministry of Defence. Thus, it is evident that M/s. Simplex Infrastructure Ltd., who has received the contract from the Ministry of Defence, are eligible for exemption from payment of Service Tax, in terms of Sl. No. 12 of Notification No. 25/2012-S.T. dated 20.06.2012, as amended, which grants exemption to the services when provided to the government, a local authority or a governmental authority. Sl. No. 12 of Notification No. 25/2012-S.T. dated 20.06.2012 provides exemption to the following services: –
“Services provided to the Government, a local authority or a governmental authority by way of construction, erection, commissioning, installation, fitting out, repair, maintenance, renovation, or altercation of –
(a) civil structure or any other original works meant predominantly for use other than for commerce, industry, or any other business or profession;
(b) A historical monument, archaeological site or remains of national importance, archaeological excavation, or antiquity specified under the Ancient Monuments and Archaeological Sites and Remains Act, 1958 (24 of 1958)
(c) A structure meant predominantly for use as
(i) an educational,
(ii) a clinical, or
(iii) an art or cultural establishment:
(d) Canal, dam or other irrigation works:
(e) Pipeline, conduit or plant for
(i) water supply,
(ii) water treatment, or
(iii) sewerage treatment or disposal; or
(f) A residential complex predominantly meant for self-use or the use of their employees or other persons specified in the Explanation 1 to clause(44) of section 65 B of the said Act;”
8.2. I find that the exemption provided under Sl. No. 12 of Notification No. 25/2012-S.T. dated 20.06.2012 is available to M/s. Simplex Infrastructure Ltd., who received the contract from Ministry of Defence. I find that M/s. Simplex Infrastructure Ltd. subcontracted the said work to the appellant. In this regard, I find that Sl. No. 29(h) of Notification No. 25/2012-S.T. dated 20.06.2012 allows exemption from payment of Service Tax to the sub-contractor also, when the said exemption is available to the main contractor. The said provision in the above Notification is reproduced below for ease of reference: –
“29. Services by the following persons in respective capacities –
(a) sub-broker or an authorised person to a stock broker;
(b) authorised person to a member of a commodity exchange;
(c) …
(d)…
(e) …
(f) …
(g)…
(ga)…
(gb)…
(h) sub-contractor providing services by way of works contract to another contractor providing works contract services whichare exempt;”
9. From a conjoint reading of the above, it is evident that the works contract services provided to DG MAP, Ministry of Defence by M/s. Simplex Infrastructure Ltd. are exempted and therefore, the appellant, being the sub-contractor, who has rendered the service of construction of dwelling units as per the contract awarded to M/s. Simplex Infrastructure Ltd. by DG MAP, Ministry of Defence, are also eligible for the exemption by virtue of Sl. No. 29(h) of Notification No. 25/2012-S.T. dated 20.06.2012. Since the appellant is eligible for the exemption as provided under Notification No. 25/2012-S.T. dated 20.06.2012, for the services of construction rendered to the Ministry of Defence, I hold that the demand of Rs.11,11,528/- confirmed in the impugned order is not legally sustainable. Consequently, the said demand is set aside.
10. Further, I also find force in the contentions raised by the appellant that the demand confirmed in the impugned order is not sustainable on the ground of limitation. The demand in the present case has been raised for the period 2014-15 whereas the Show Cause Notice came to be issued on 17.10.2019, by invoking the extended period of limitation. Admittedly, the demand has been raised on the basis of the data received from the Income Tax Authorities / Form 26AS, without conducting any independent enquiry so as to ascertain the nature of service being rendered by the appellant. It has been held in a catena of decisions that the data available in Income Tax Returns / Form 26AS loses its evidentiary value in the absence of any corroborative independent evidence. In this case, I do not find that any evidence has been brought on record by the Revenue to show that the appellant has indulged in any activity amounting to suppression or wilful mis-statement with the intent to evade Service Tax. Therefore, the allegation of suppression of facts and wilful mis-statement of facts for invocation of the extended period of limitation only on assumptions and presumptions cannot be sustained. Accordingly, in view of the facts and evidence available on record, I am of the view that the demand confirmed vide the impugned order, by invoking the extended period of limitation, is liable to be set aside. Thus, the impugned demand stands set aside on account of being barred by limitation also.
11. Since the demand itself does not survive, the question of demanding interest or imposing penalty does not arise. The said demands are therefore also set aside.
12. In view of the above, I set aside the impugned order and allow the appeal, with consequential relief, if any, as per law. (Dictated and pronounced in the open court)
(Dictated and pronounced in the open court)