
Dalmia Cement (Bharat) Ltd. Vs Commissioner (CESTAT Kolkata)
Summary: The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Kolkata, examined whether civil work undertaken by a contractor at the railway siding of Dalmia Cement (Bharat) Ltd. could be classified as manpower supply service, attracting Service Tax liability under the Reverse Charge Mechanism (RCM). The proceedings originated from a show cause notice demanding Service Tax of ₹44,81,113. The adjudicating authority dropped ₹40,57,307 but confirmed ₹4,23,806 on the ground that the services supplied by M/s. Shree Durga Enterprises constituted manpower supply. The Commissioner (Appeals) upheld the confirmed demand, leading the assessee to approach the Tribunal.
The appellant contended that the contractor had undertaken civil construction work at the railway siding through its own workers and had not supplied manpower to the appellant. The work order expressly described the activity as civil work and prescribed payment according to the quantity of work executed, including rates per square metre or cubic metre. The Tribunal examined the contractual documents and found that the contractor was not charging according to the number of workers or man-days supplied. Instead, billing was based on the actual volume of civil work completed. The work order also did not specify the number of workers deployed. Accordingly, the Tribunal held that the contract could not be treated as manpower supply service and set aside the demand on merits.
The Tribunal independently examined the question of limitation. It observed that the relevant transactions had been recorded in the appellant’s books of account and that the Department had obtained the information used to quantify the demand from those records. Furthermore, the appellant manufactured dutiable goods and would have been eligible for CENVAT credit of the Service Tax if it had been payable under the reverse charge mechanism. In these circumstances, the Tribunal found no basis for alleging suppression of facts. It therefore held that the confirmed demand was barred by limitation as well.
Consequently, the Tribunal allowed Dalmia Cement (Bharat) Ltd.’s appeal with consequential relief, if any, in accordance with law. The decision establishes, on the facts of the work order examined, that a contract remunerated according to completed civil work cannot be classified as manpower supply merely because the contractor deploys workers to execute it. It also reinforces the significance of disclosed accounting records and availability of corresponding CENVAT credit when examining allegations of suppression and invocation of the extended limitation period.
FULL TEXT OF THE ORDER OF CESTAT KOLKATA
The Appellants were issued a Show Cause Notice demanding Service Tax of Rs.44,81,113/-. After due process, the Adjudicating authority dropped the demand to the extent of Rs.40,57,307/- and confirmed the balance demand of Rs.4,23,806/- The Adjudicating authority held that service provider has provided Manpower Supply Services and therefore the Appellant is required to discharge Service Tax liability on Reverse Charge Mechanism (RCM) basis. Being aggrieved, the Appellant had filed their Appeal before the Commissioner(Appeals), who has dismissed the same. Therefore, the Appellant is before the Tribunal.
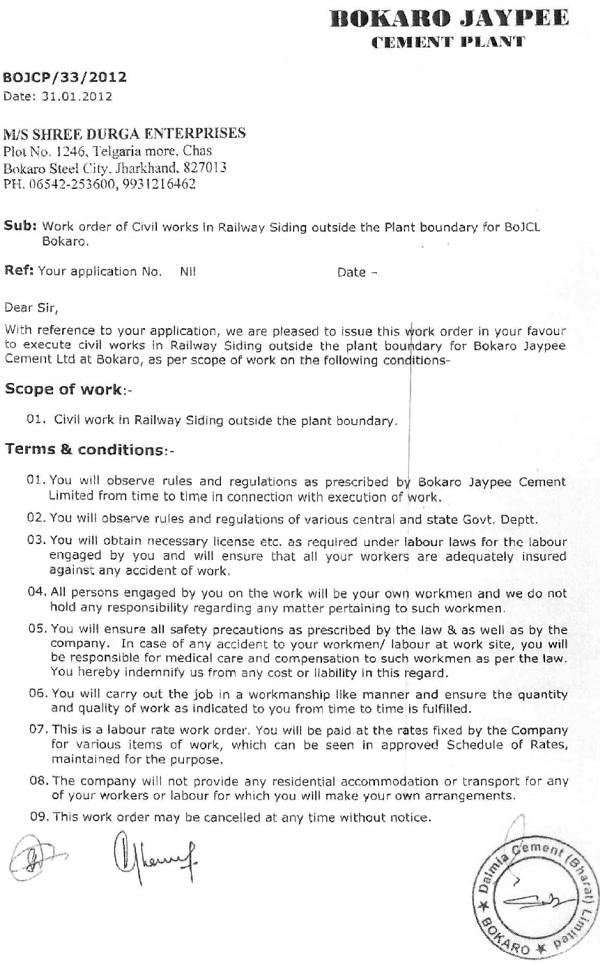
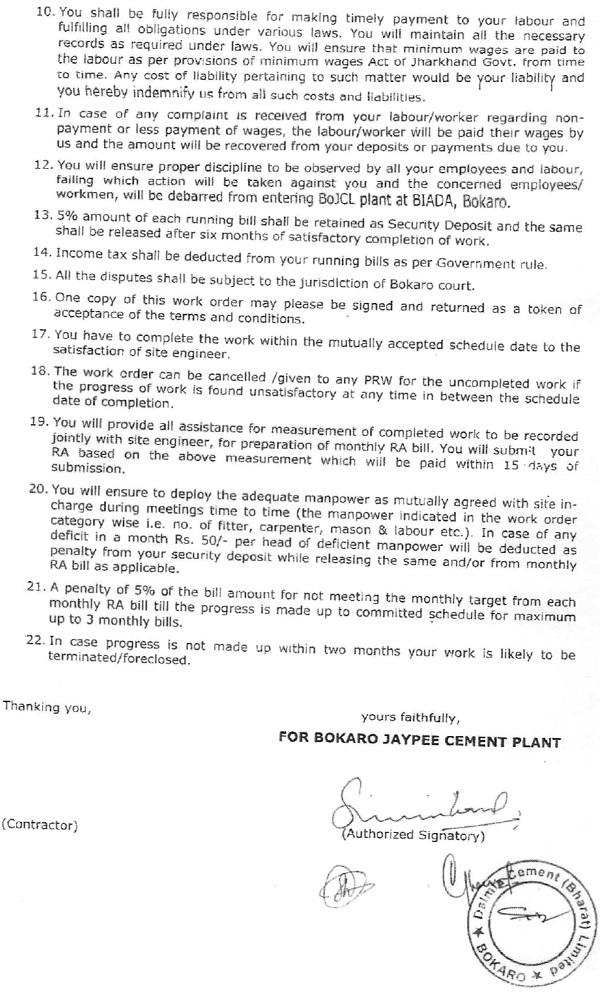
2. The Ld.Advocate appearing on behalf of the Appellant submits that the Adjudicating authority is in error in holding that the services provided by M/s. Shree Durga Enterprises pertain to Manpower Supply service, whereas they were taking up only civil work. She produces copy of the work order issued to Shree Durga Enterprises, wherein it is clearly stated that they will undertake civil work at Railway siding by deploying their own workers. This Work Order also gives the details of rate per square meter/cubic meter of work done. She submits that therefore the service provided by M/s. Shree Durga Enterprises cannot be taken as ‘Manpower Service’.
3. She also submits that the Show Cause Notice issued on 12.06.2017 for the transactions taking place during July 2012 to December 2024 is hit by the aspect of time bar.
4. The Ld.AR for the Department reiterates the findings in the impugned order and justifies the confirmed demand.
5. Heard both sides and perused the Appeal papers and other documentary evidence placed before us.
6. We have gone through the Work Order issued to M/s. Shree Durga Enterprises and the same is reproduced below :
–
–
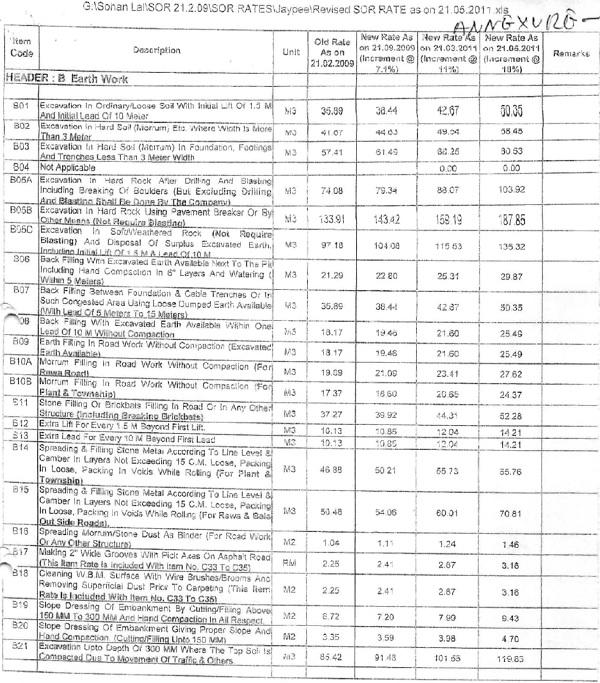
7. From the above Work Order, we find that the service provider is not charging any amount towards ‘Supply of Manpower’ on the number of man days provided by him. It is based on the civil work carried out and the billing is done towards per cubic meter of work done. As a matter of fact, there is no mention about any number of workers deployed for this work. Therefore, based on such factual documentary evidence, the lower authorities have considered the service as ‘Manpower Service’. Therefore, on merits, we set aside the demand.
8. We also find that the demand is time barred since the Appellant has recorded all the transactions in their Books of Accounts, from wherein the data was collected to quantify the demand. Moreover, since the Appellant is manufacturer of dutiable goods, even if the Revenue’s view that the service would be in respect of the ‘Manpower Service’, the same would be eligible as Cenvat credit to the Appellant, if Service Tax were to be paid on RCM basis. Hence, no case of suppression can be made out against the appellant. Therefore, we set aside the confirmed demand even on account of time bar.
9. Accordingly, the Appeal stands allowed with consequential relief, if any, as per law.
(Order pronounced in the open Court on 06.10.2026.)





