
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.
Same Cash Deposits Cannot Be Taxed Twice Under Different PANs: ITAT Chandigarh

Section 263 Valid Where AO Dropped Bogus Purchase Addition Without Enquiry: ITAT Chandigarh

Only Commission Income Taxable on Bogus Purchases; Entire Turnover Cannot Be Added: ITAT Delhi

Interest-Free Loans to Charitable Trusts Do Not Deny Sections 11 & 12 Exemption: ITAT Delhi
Second Section 148 Notice During Pendency of Earlier Reassessment Is Invalid: Delhi ITAT

Delhi HC Quashes Section 153C Proceedings as Seized Documents Did Not Belong to Assessee

HC Condones Delay Under Section 119(2)(b), Allows Carry Forward of Capital Loss

Reassessment on Borrowed Satisfaction Invalid; Section 153C Must Apply: ITAT Ahmedabad

COVID-19 Hardship Justifies Delay Condonation Under Section 119(2)(b): Gujarat HC

Bombay HC Quashes Assessment for Failure to Issue Section 144C Draft Order
Section 12AB Registration Cannot Be Denied Without Proper Verification: ITAT Chandigarh

Mere Possession Cannot Prove Ownership of Seized Gold Jewellery: Mumbai ITAT
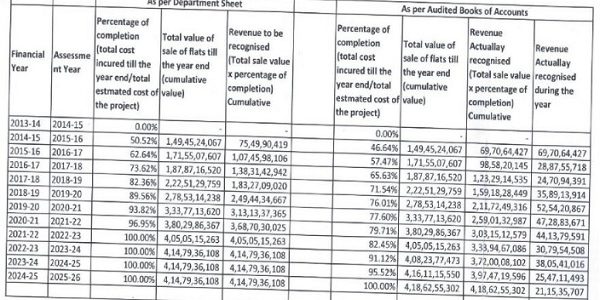
AO Cannot Recompute POCM Profits Without Rejecting Books: Ahmedabad ITAT
Time-Barred Reassessment Under Section 153 Invalid, Entire Addition Fails: ITAT Ahmedabad
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

