
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

Delhi ITAT: Reassessment Beyond 3 Years Invalid Below ₹50 Lakh – AYs 2014-15 & 2015-16 Quashed

Delhi ITAT: Post-1 April 2021 Deemed Search Invalidates Section 153C Notice & Assessment
Delhi ITAT: Ex-Parte U/s 12A & 80G Rejection Set Aside; Trust Gets Fresh Hearing on Irrevocable Clause

Ahmedabad ITAT: ₹18.31 Lakh Cash Deposit Addition Restored for Bank Verification

ITAT Hyderabad Excludes 6 TP Comparables for Turnover and Functional Differences: Infor India

ITAT Bangalore Excludes Infosys and 3 Comparables for TP Benchmarking Differences

ITAT Mumbai Remits TP Issues, Allows Working Capital Adjustment: Red Hat India
Bangalore ITAT Applies Turnover and RPT Filters, Allows Section 10A Deduction

ITAT Hyderabad Excludes TP Comparables, Deletes Receivables Adjustment
ITAT Bangalore Remands Interest on AE Receivables for Fresh TP Benchmarking
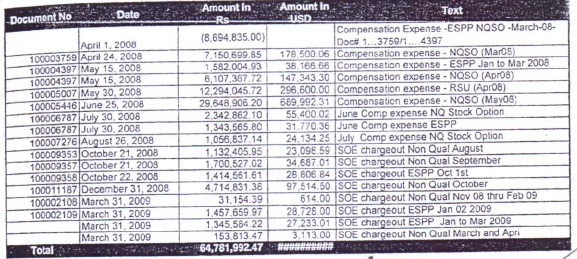
Bangalore ITAT Allows 80JJAA Deduction and Lease Rentals, Remands Software Expenses

Delayed Tax Payment Does Not Constitute Evasion Attempt Under Section 276C(2): Karnataka HC

ITAT Mumbai Excludes Infosys, Wipro and Other Comparables in Software Development ALP
ITAT Bangalore Excludes High-Turnover Comparables in Software Development ALP
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

