Crescent Foundry Company Private Limited Vs Commissioner of Customs (Port) (CESTAT Kolkata)
Summary: CESTAT Kolkata dismissed Crescent Foundry Company Private Limited’s appeal against denial of customs exemption on goods re-imported for repair and re-export. The appellant had exported 300 sets of ductile iron castings to Oman. After the buyer received them in damaged condition, the goods were returned to India and cleared without payment of duty against a bond and bank guarantee under Notification No. 158/95-Cus., dated 14 November 1995.
Instead of exporting the repaired goods, the appellant supplied freshly manufactured goods to meet the overseas buyer’s urgent requirement. It argued that the descriptions and quality matched and that foreign exchange had been received. The Tribunal held that the notification required re-export of the very goods re-imported for repairs or reconditioning and did not permit substitution with freshly manufactured goods. The absence of re-export particulars in the shipping bill also prevented Customs from verifying the identity of the goods.
The Tribunal distinguished the authorities cited by the appellant and upheld the lower authorities’ conclusion that the exemption conditions were not fulfilled. Consequently, the appeal against the order sustaining the duty demand of ₹6,30,272, confiscation with an option to redeem on payment of ₹2 lakh, and penalty of ₹50,000 was dismissed.
Cases Discussed
- In Re Star Wire (India) Ltd., 2011 (272) E.L.T. 448 (G.O.I.) — The appellant relied on this decision. The Tribunal distinguished it as concerning drawback on re-export of scrap, whereas the present dispute concerned failure to re-export the goods imported for repairs and reconditioning.
- Natural Remedies Private Limited v. CCE Bangalore — The appellant cited this decision, but the Tribunal held that its facts were different and that it did not apply to the present case.
FULL TEXT OF THE CESTAT KOLKATA ORDER
The appellant exported ductile iron casting rough of 300 sets in 60 packages against shipping bill No. 6341279 dated 19-08-2019 to CR Casting Sultanate of Oman. On receipt of the goods by the importer, it was seen that the goods were received in damaged condition. Therefore, the foreign buyer vide invoice dated 08-07-2020 sent back the goods to India for necessary rework and return of the goods to them. The appellant vide Bill of Entry No. 8818701 dated 15-09-2020 sought clearance of the imported goods on executing bond and bank guarantee and by availing the duty exemption benefit under Notification No. 158/95 CUS dated 14-11-1995. The appellant got the goods cleared without payment of duty on the condition that they would re-export the goods after taking up the necessary rework.
2. In view of exigency and urgent requirement by the overseas importer, the appellant instead of sending the re-worked goods, exported the freshly manufactured goods vide shipping bill No. 9494753 dated 93-02-21. The appellant got the foreign exchange for the re-exported goods. After this, the appellant sought cancellation of re-export bond and bank guarantee. On verification of the documents, the Assistant Commissioner vide letter dated 28-10-2021 pointed out that there was no mention in the Shipping Bill about the re-exportation of subject goods. The appellant was issued a show-cause notice on 21-03-2022 alleging violation of the conditions specified under Notification No. 158/95 CUS dated 14-11-1995. Therefore, custom duty of Rs 6,30,272/- was demanded along with interest and penalty. The appellant pointed that they have dispatched the same goods once again. However, instead of re-exporting the repaired goods, they had dispatched the normally manufactured goods. Both the goods are of the same quality. Therefore, the shipping bill should be taken as if that was pertaining to the re-export of the goods. However, the adjudicating authority confirmed the demand and also confiscated the goods in question and gave an option to redeem the same on payment of redemption fine of Rs 2 lakhs. He also imposed penalty of Rs 50,000 under Section 112 (a) of Customs Act 1960. Being aggrieved, the appellants filed their appeal before the Commissioner Appeals who has dismissed their appeal. Therefore, the appellant is before the Tribunal.
3. The Learned Counsel submits that in view of the exigency, the appellant dispatched the freshly manufactured goods to the overseas importer. The description of the goods exported and the initially re-imported goods would 100% tally. Therefore, the appellant submits that there was no violation of any condition imposed under Notification 158/95 Cus dated 14-11-1995. He relies on the case law of In Re Star Wire (India) Ltd. [2011(272) E. L. T. 448(G.O.I.)]. He also relies on the case law of Natural Remedies Private Limited v. CCE Bangalore. In view of those submissions, he prays that the appeal may be allowed.
4. The Learned AR, appearing on behalf of the Revenue, submits that Notification 158/95 Cus dated 14-11-1995 clearly specifies that the exports have to be in respect of the same goods after repairs and reconditioning within the period as stipulated. The details should be mentioned in the shipping bill and the same should satisfy the Assistant Commissioner of Customs with regard to identity of the goods. In the present case, in the shipping bill, the appellant has not mentioned anything about the fact of the goods being re-exported. Therefore, the condition mentioned under Notification 158/95 Cus is not satisfied. He justifies the confirmed demand on both sides.
5. Heard both the sides.
6. We have gone through the Notification 158/95 Cus dated 14-11-1995 which is reproduced below:-
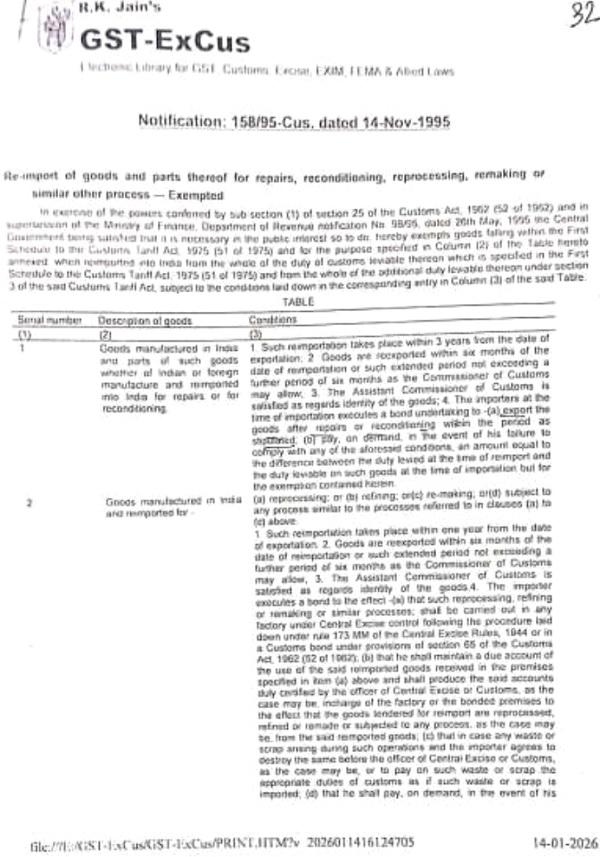
7. From the Notification we find that the condition stipulated is very clear. It says that the importer at the time of importation should execute a bond undertaking to:
a. Export the goods after repairs or reconditioning within the period as specified.
b. Pay on demand in the event of his failure to comply with any of the aforesaid conditions.
8. This condition makes it clear that the goods which are to be re-exported are the ones which have been re-imported in India for which the permission has been granted to take up the repair work and to re-export the same within the specified time. There is nothing mentioned in the Notification that the normal goods which are manufactured can be simply substituted with the re-imported goods and the same can be re-exported against the re-imported goods.
9. We have also gone through the Shipping Bill No. 6341279. We find that there is no mention that the goods in question dispatched are the re-imported goods after rework. Had this fact been mentioned in the Shipping Bill, the Assistant Commissioner at Port would have caused necessary verification as to whether the goods being re-exported are the same ones which are being re-exported after repairs and reconditioning at the factory of the present appellant. This factual evidence could not be verified by the Customs Department since the appellant failed to mention about this fact in the Shipping Bill.
10. Therefore, we hold that the appellant has not fulfilled the requisite condition of the Notification, as has been correctly held by the lower authorities.
11. We find that in the case of Star Wire India Ltd, which has been decided by the Joint Secretary of the Government of India, the issue was completely different. It was a case drawback on account of re-exports in respect of scrap, whereas, in the present case, it is a specific case of re-import of the goods on the ground that it would undergo repairs and reconditioning and the same would be exported which has not been done in this case. So far as the other case law of Natural Remedies Pvt Ltd is concerned, the facts are different and not applicable to the present case.
12. In view of the foregoing, we do not find any merits in the appeal filed by the appellant.
13. Accordingly, we dismiss the Appeal.
(Order Pronounced in Open court on 08.10.2026)