Siemens Financial Services Private Limited Vs Rasik Khandelwal (NCLT Allahabad)
Summary : The National Company Law Tribunal, Allahabad Bench, admitted Siemens Financial Services Private Limited’s application under Section 95 of the Insolvency and Bankruptcy Code, 2016 and initiated the Personal Insolvency Resolution Process against Rasik Khandelwal, personal guarantor to Rasik Products Private Limited. The application, filed on 19 April 2024, concerned unpaid dues of ₹3,81,04,993 arising from four secured loan facilities sanctioned during 2022. The finance agreements contained unconditional and irrevocable guarantees making the guarantor jointly and severally liable with the borrower. Following repayment defaults, the accounts were classified as non-performing assets on 14 December 2023. The creditor invoked the guarantee through a notice dated 16 February 2024 under Section 13(2) of the SARFAESI Act, 2002, followed by a statutory Form B demand notice dated 12 March 2024. The guarantor did not discharge the liability within fourteen days of service of the statutory notice.
The Resolution Professional, appointed on 18 October 2024, submitted a report dated 1 November 2024 recommending admission. He recorded that the application satisfied the statutory requirements, the finance agreements established the personal guarantee, and the guarantor had not produced proof of repayment despite requests for information. The guarantor subsequently challenged maintainability, alleging that repayment dates and the date of default were insufficiently specified, the creditor’s status and computation of approximately ₹3.81 crore were unjustified, additional interest had been improperly charged, and the creditor had proceeded against him without first making substantial recovery efforts against the borrower. He also questioned the timing and contents of the NeSL record and alleged that the Resolution Professional had mechanically recommended admission. In disputing the debt computation, he cited Central Bank of India v. Ravindra & Ors., (2002) 1 SCC 367.
The creditor answered that signed repayment schedules and statements of account established the obligations and default. It stated that the instalment default occurred on 14 September 2023, followed by NPA classification on 14 December 2023, and relied on the contractual acceleration and cross-default clauses. Citing Laxmi Pat Surana v. Union Bank of India & Anr., (2021) 8 SCC 481, it submitted that the borrower and guarantor could be proceeded against simultaneously. It also relied on the NeSL Form D recording default on 14 September 2023 and on communications concerning payment assurances and settlement. The Tribunal held that the application was within the three-year limitation period under Article 137, considering the repayment default, guarantee invocation and filing date.
Rejecting the requirement of prior recovery against the borrower, the Tribunal noted that CIRP against Rasik Products Private Limited had already commenced by an order dated 8 September 2025. It further relied on Mahendra Kumar Jajodia v. State Bank of India, (2022) ibclaw.in 32 SC for the position that commencement of CIRP against the corporate debtor was not a condition precedent to personal guarantor insolvency. It held that detailed computation of the default amount would be undertaken by the Resolution Professional during collation of claims and that, at admission, the default need only prima facie exceed the applicable threshold. The order recorded that the claimed default exceeded ₹1 crore. It also rejected the procedural and default-date objections, finding compliance with Section 95 and the applicable rules. NeSL records were held not to be a prerequisite because debt and default could be established through finance agreements, repayment schedules, statements of account and other documents.
The Tribunal found the guarantee absolute, unconditional and irrevocable and applied the co-extensive liability principle under Section 128 of the Indian Contract Act, 1872. It accepted that the guarantor had failed to pay despite invocation and statutory demand, admitted the petition and continued Amit Ojha as Resolution Professional. A moratorium was declared for 180 days from admission or until an order on the repayment plan under Section 114, whichever occurred earlier. The Tribunal directed publication of notice, invitation and collation of creditor claims, preparation of a repayment plan and compliance with the subsequent statutory process. The Resolution Professional was directed to submit progress reports every thirty days, and the matter was listed for further proceedings on 16 November 2026.
Cases Discussed
- Mahendra Kumar Jajodia v. State Bank of India, (2022) ibclaw.in 32 SC (Supreme Court) — Relied upon by the Tribunal for the position that initiation of CIRP against the principal borrower or corporate debtor is not a condition precedent to insolvency proceedings against its personal guarantor.
- Laxmi Pat Surana v. Union Bank of India & Anr., (2021) 8 SCC 481 (Supreme Court) — Cited by the financial creditor to support simultaneous proceedings against the borrower and guarantor and the co-extensive nature of the guarantor’s liability.
- Central Bank of India v. Ravindra & Ors., (2002) 1 SCC 367 (Supreme Court) — Cited by the personal guarantor while disputing the computation of the outstanding debt and interest; the Tribunal rejected his objection to admission based on the disputed computation.
- Siemens Financial Services Private Limited v. Rasik Products Private Limited, CP (IB) No. 38 of 2023, order dated 08.09.2025 (NCLT Allahabad) — The connected corporate debtor proceeding was referred to while rejecting the objection that remedies against the principal borrower had not been pursued; the Tribunal recorded that CIRP had already commenced.
FULL TEXT OF THE NCLAT JUDGMENT/ORDER
1. This application has been filed on 19.04.2024 under Section 95 of Insolvency and Bankruptcy Code (hereinafter referred to as “the IBC/Code”) r /w Rule 7(2) of the Insolvency and Bankruptcy (Application to Adjudicating Authority for Insolvency Resolution Process for Personal Guarantor to Corporate Debtor) Rules, 2019 (hereinafter referred to as “PIRP Rules”) by Siemens Financial Services Private Limited (hereinafter referred to as “Applicant / Financial Creditor”) The prayer made is to initiate the Personal Insolvency Resolution Process (hereinafter referred to as “PIRP”) in respect of Mr. Rasik Khandelwal (“the Respondent/ Personal Guarantor”), the Personal Guarantor to the Corporate Debtor i.e.,Rasik Products Private Limited. The Date of Default, as mentioned in Part-III of the Petition, is 14.12.2023.
2. Part – I of the Application sets out the details of the Applicant having address at Plot No.2, Sector No. 2, Kharghar Node, Navi Mumbai 410210. Part-II of the Application sets out the details of the Respondent/ Personal Guarantor having address at 141 KM, Delhi Agra Bye Pass near Alwer Railway Bridge – Krishna Nagar, Mathura- 281001 and also at H No. 97, Govind Dev Temple Vrindavan, Mathura(UP)- 281001. The details of the Corporate Debtor, i.e., Rasik Products Private Limited, for which guarantee was given, is having its office at 141 KM, Delhi Agra Bye Pass near Alwer Railway Bridge – Krishna Nagar, Mathura- 281001. Hence, this Tribunal has jurisdiction over this case under Section 60(3) of the IBC.
3. Part – III of the Application provides the particulars of the debt, which in the present case is Rs. 3,81,04,993/- (Rupees Three Crore Eighty-One Lakh Four Thousand Nine Hundred and Ninety-Three Only). As stated, the default is continuing in nature from September 2023, and the account was declared NPA “Non-Performing Asset” on 14.12.2023.
4. The Applicant/ Financial Creditor has submitted that it had sanctioned the following credit facilities to the Corporate Debtor on numerous occasions:
i. On 31.01.2022, the Secured Loan 1 amounting to Rs. 3,65,11,956/- and Secured Loan 2 amounting to Rs. 84,88,404/- were sanctioned vide separate Sanction Letters, both dated 31.01.2022. Pursuant thereto, the respective Finance Agreements, bearing Nos. A9813943 and A9814174, were executed between the parties on 31.01.2022.
ii. On 22.09.2022, the Secured Loan 3 facility of Rs. 1,30,00,000/- was sanctioned vide a Sanction Letter dated 22.09.2022, with the corresponding Finance Agreement, bearing No. A9874677, being duly executed by the parties on the same date.
iii. On 14.11.2022, the Secured Loan 4 facility of Rs.70,00,000/- was sanctioned vide a Sanction Letter dated 14.11.2022, and is governed by the corresponding Finance Agreement, bearing No. A9985776.
5. In respect of all the aforesaid credit facilities, as stipulated under the respective Finance Agreements executed from time to time, the Respondent/Personal Guarantor agreed to be jointly and severally liable for the repayment of the amounts due and payable by the Principal Borrower, i.e., the Corporate Debtor, in respect of the said facilities. The relevant excerpts of Clause 11 of the finance agreement executed are as follows:
“(a) The Guarantor(s) hereby unconditionally and irrevocably guarantee to the Lender the due payment by the Borrower of the Loan and the due payment of amounts which are or which may at any time hereafter become due and payable by the Borrower to the Lender under or in connection with the Loan that may be granted by the Lender (or its assigns) to the Borrower in the future (all of which are hereinafter collectively referred to as the Borrowers Dues).
(b) In event of the Borrower for any reason omitting, failing or defaulting in making the payment of the Borrowers Dues or any part thereof to the Lender, the Guarantor(s) irrevocably agree and undertake that on demand by the Lender, the Guarantor(s) shall without any demur or protest pay to the Lender the Borrowers Dues in full up to the date of payment.
(c) Any such demand made by the Lender on the Guarantor(s) shall be conclusive as regards the correctness of the amount mentioned therein, as having become due and payable by the Borrower to the Lender, and also conclusive as regards default having been committed by the Borrower in payment of the amount to the Lender.
(d) To give effect to this Guarantee, the Lender shall be at liberty to consider and treat the Guarantor(s) as the principal debtors to the Lender in respect of all payments guaranteed by the Guarantor(s) to the Lender (or its assigns) hereunder.
(e) The Guarantors liability hereunder is joint and several along with the liability of the Borrower and co-extensive with that of the Borrower.
(f) This Guarantee shall be enforceable against the Guarantor(s) notwithstanding that any negotiable instrument may be outstanding at the time when demand is made or proceedings are taken against the Borrower or any security is available for the Borrowers Ducs with the Lender or is sold or sought to be sold by the Lender.”
6. Thereafter, the loan amounts were disbursed to the Corporate Debtor from time to time, and the disbursements are evidenced by the respective Statements of Accounts annexed hereto as Exhibits ‘R’, ‘S’, ‘T’ and ‘U’, respectively. However, the Corporate Debtor failed to repay the aforesaid loan amounts in accordance with the repayment schedules agreed upon between the parties. Consequently, owing to such defaults in repayment, the loan accounts of the Corporate Debtor were classified as Non-Performing Assets (NPAs) on 14.12.2023
7. After the classification of the loan accounts of the Corporate Debtor/Principal Borrower as NPA, the Applicant /Financial Creditor issued a Notice dated 16.02.2024 under section 13(2) of the SARFAESI Act, 2002 to the Corporate Debtor/Principal Borrower as well as to the Personal Guarantor, demanding a total outstanding payment of Rs. 3,81,21,244/- as on 14.02.2024 within 60 days from the date of notice. Accordingly, the guarantee of the present Respondent/Personal Guarantor was invoked vide this Notice.
8. Since no payment was made by the Corporate Debtor as well as the Personal Guarantor pursuant to the aforesaid notice under Section 13(2), the Applicant issued a Form-B Demand Notice dated 12.03.2024 under Rule 7(1) of the Insolvency and Bankruptcy (Application to Adjudicating Authority for Insolvency Resolution process of Personal Guarantors to Corporate Debtors) Rules, 2019 to the Respondent/Personal Guarantor, calling upon him to unconditionally pay the outstanding sum of Rs. 3,81,04,993/- as on 14.02.2024 due to the Corporate Debtor.
9. The Personal Guarantor, however, also failed to clear the outstanding debt due to the Applicant within 14 days from the receipt of the Demand Notice in Form B, as mandated under the IBC,2016.
10. Consequently, the Application under Section 95 of the Code read with Rule 7(2) of PIRP Rules has been filed by the Applicant/ Financial Creditor against the Respondent Personal Guarantor with a prayer to initiate PIRP against the Respondent/ Personal Guarantor.
11. On filing of the Application under Section 95 on 19.04.2024, this Tribunal, vide order dated 18.10.2024, appointed Mr Amit Ojha with Registration No. IBBI/IPA-002/IPN01005/2020-2021/13275, as Resolution Professional and ordered him to examine whether the Company Petition is as set out in Section 97(6) of IBC, 2016 and recommend on acceptance or rejection of the application, as the case may be.
REPORT BY RESOLUTION PROFESSIONAL
12. The Resolution Professional (hereinafter referred as ‘RP’) has filed an Interlocutory Application bearing IA No. 646/2024 on 01.11.2024 for submitting a report under Section 99(1) of the Code.
13. The Resolution Professional submitted his report under Section 99 before this Tribunal dated 01.11.2024 with the following prayers:
“a. Accept and take on record the report under section 99 for acceptance of the application under Section 95 of Insolvency and Bankruptcy Code, 2016; and/or,
b. Pass any other or further Order/s as this Hon’ble Tribunal may deem fit and proper in the facts and circumstances of the case in the interest of Justice, Fair-Play and Equity.”
14. Further, it is stated that the report is filed in compliance with Section 99 of the Code. It is apparent that the report is filed recommending initiation of PIRP against the Personal Guarantor, Mr. Rasik Khandelwal.
15. A perusal of the Report filed under Section 99 of the Code submits the following observations: –
| S. No. | Requirements under the relevant provisions of Section 99 of the Code | Submissions of the RP | Compliance with the requirements of Section 99 of the Code (Yes/No) |
|---|---|---|---|
| 1. | Section 99(1):
The resolution professional shall examine the application referred to in section 94 or section 95, as the case may be, within ten days of his appointment, and submit a report to the Adjudicating Authority recommending for approval or rejection of the application. |
The RP submits that the present Report is being prepared in compliance with the requirements of Section 99(1) of the Code. | Yes |
| 2. | Section 99(2):
Where the application has been filed under section 95, the resolution professional may require the debtor to prove repayment of the debt claimed as unpaid by the creditor by furnishing—(a) evidence of electronic transfer of the unpaid amount from the bank account of the debtor; (b) evidence of encashment of a cheque issued by the debtor; or (c) a signed acknowledgment by the Creditor accepting receipt of dues. |
That a Letter dated 23.10.2024 along with order dated 18.10.2024 was sent to Personal Guarantor to submit relevant documents within 7 days and the same was sent by way of Speed Post, E-Mail and Courier on 23.10.2024, 23.10.2024 and 24.10.2024 respectively. Mr. Rasik Khandelwal, Personal Guarantor was required to prove repayment of the debt claimed as unpaid by the Financial Creditor i.e., Siemens Financial Services Pvt. Ltd., That till date the Personal Guarantor has not provided any details/ documents to prove repayment of debt. That in absence of any reply from the Personal Guarantor, the Resolution Professional has concluded that the Personal Guarantor has not repaid the debt claimed by the Financial Creditor. | Yes |
| 3. | Section 99(3):
Where the debt for which an application has been filed by a creditor is registered with the information utility, the debtor shall not be entitled to dispute the validity of such debt. |
The Creditor has not filed the record available with the information utility (NeSL), alongwith the application under Section 95 of the Code, showing record of default. | No. |
| 4. | Section 99(4):
For the purposes of examining an application, the resolution professional may seek such further information or explanation in connection with the application as may be required from the debtor or the creditor or any other person who, in the opinion of the resolution professional, may provide such information. |
Information and explanation were sought in connection with the application from the Personal Guarantor. Copy of the Letter dated 23.10.2024 alongwith its postal and courier Receipts and respective tracking reports have been annexed along with the present application. | Yes |
| 5. | Section 99(5):
The person from whom information or explanation is sought under sub-section (4) shall furnish such information or explanation within seven days of receipt of the request. |
Mr. Rasik Khandelwal, Personal Guarantor was required to prove repayment of the debt claimed as unpaid by the Financial Creditor i.e., Siemens Financial Services Pvt. Ltd., That till date the Personal Guarantor has not provided any details/ documents to prove repayment of debt. | Yes |
| 6. | Section 99 (6):
The resolution professional shall examine the application and ascertain that- (a) the application satisfies the requirements set out in section 94 or 95 (b) the applicant has provided information and given explanation sought by the resolution professional under sub-section (4). |
RP submits that the present application satisfied the requirements of provisions of Section 95 as has been provided in detail hereinabove. | Yes |
| 7. | Section 99(7):
After examination of the application under sub-section (6), he may recommend acceptance or rejection of the application in his report. |
RP Submits that the Present application satisfies the requirements of provisions of Section 95 as is required to be examined under Section 99(6) of the Code. | Yes
The RP submits that based on his examination the present application deserves to be admitted under Section 100 of the Code and this Hon’ble Tribunal may pass appropriate Orders. |
| 8. | Section 99(8):
Where the resolution professional finds that the debtor is eligible for a fresh start under Chapter II, the resolution professional shall submit a report recommending that the application by the debtor under section 94 be treated as an application under section 81 by the Adjudicating Authority. |
No information has been received from the Debtor/ Personal Guarantor in this regard in compliance of provisions of Section99(8). Moreover, the relevant sections are not yet notified and hence, the same cannot be applied in the present case. | Not Applicable; The RP submits that the provisions of Section 99(8) of the code does not apply to the present case. |
| 9. | Section 99(9):
The resolution professional shall record the reasons for recommending the acceptance or rejection of the application in the report under sub-section (7). |
As per Section 99(7) and 99(9) of the code, the RP has duly examined the application filed by the Financial Creditor against the Personal Guarantor under Section 95 of the Code and concludes as under:
A. The application is complete in all context and satisfies the requirements set out under Section 95(4) of the Code. B. The Application of the Financial Creditor reflects that the said loan advanced still remains unpaid, even after delivery of Demand Notice. Same has also not been rebutted by the Personal Guarantor. C. The Personal Guarantor has failed to produce any proof of repayment, hence, debt is due and payable. D. Further, the personal guarantor has not responded with any material acts/ evidentiary documents to rebut the claims made out by the Applicant/Financial Creditor. E. That I had also perused one Demand Notice dated 12.03.2024 in Form B Rule 7(1) of the Insolvency and Bankruptcy (Application to Adjudicating Authority for Insolvency Resolution Process of Personal Guarantors to Corporate Debtors) Rules, 2019 sent on behalf of the Financial Creditor through his counsel upon the personal Guarantor Mr. Rasik Khandelwal through Speed Post requesting the Personal Guarantor to unconditionally pay the unpaid debt in default in full within 14 days from the receipt of the notice failing which insolvency resolution process would be initiated against him. That the said demand notice dated 12.03.2024 has been duly delivered to the Personal Guarantor however the Personal Guarantor neither replied to the said demand notice nor any payment has been made to the Financial Creditor after delivery of the said Demand Notice. F. That it is evident from the application under section 95 as filed by the Financial Creditor that the agreement(s) contains the Clause of Hypothecation and Guarantee which was signed and duly executed between the Applicant / Financial Creditor and the Corporate Debtor/ Personal Guarantors, and Mr. Rasik Khandelwal stood guarantor in his personal capacity in consideration of the loan/credit facilities and the same has not been rebutted by the Personal Guarantor. |
Yes |
| 10. | Section 99(10):
The resolution professional shall give a copy of the report under sub-section (7) to the debtor or the creditor, as the case may be. |
The Resolution Professional submits that he has complied with the requirement of filing a copy of the present report prepared under section 99(7) of the Code to the Financial Creditor as well as to the Personal Guarantor. | Yes |
16. The Resolution Professional in his Report recommended to initiate PIRP against Mr Rasik Khandelwal, the Personal Guarantor and the relevant portion is extracted below:
“1. That in view of the above-mentioned facts, circumstances and grounds, the Resolution Professional by way of this report recommends to the Hon’ble Adjudicating Authority for acceptance of the Application bearing CP (IB) – 79/ALD/2024 filed by the Applicant / Financial Creditor herein under Section 95 of the IBC, 2016.
2. That the said report has been filed within the stipulated period as directed by the Hon’ble Court.”
17. After filing of the above report of RP, a copy of the same was served to the Respondent/Personal Guarantor. Thereafter, vide order dated 19.11.2024, this Tribunal directed the Respondent to file its reply/objections, if any, to the RP’s report within a period of two weeks. Subsequently, vide order dated 18.12.2024, this Tribunal took the RP’s report on record, and I.A. No. 646/2024 was accordingly disposed of. The relevant excerpts of order dated 18.12.2024 has been reproduced as follows:
“1. Ld. Counsel representing the RP states that the RP report has been filed vide IA No.646 of 2024. The same is taken on record. He also states that the advance copy of the RP report has already been supplied to the Personal Guarantor. It has also been so observed in para no.1 of the order dated 19.11.2024.
2. Accordingly, IA No.646/2024 stands disposed off. ”
REPLY OF THE RESPONDENT/ PERSONAL GUARANTOR
18. The Respondent/ Personal Guarantor has filed its reply dated 15.04.2025, wherein he has denied all the averments made by the Applicant/ Financial Creditor as well as RP in his report under Section 99 and submits as follows:
a. The Respondent at the outset contends on the ground of maintainability of the present petition and states that the loan facilities bearing Nos. A9813943, A9874677, and A9874677 do not prescribe any specific due date for repayment as per the repayment schedule. In the absence of a specified due date, the Applicant cannot allege default in repayment since, as per the Code, a “default” is said to occur only when a debtor fails to pay the debt on the due date.
b. The Respondent contends that the requirements prescribed under Rule 7(2) of the Application to Adjudicating Authority for Insolvency Resolution Process for Personal Guarantors to Corporate Debtor Rules, 2019, as Part III of the present petition, fail to disclose a clear and specific date of default.
c. The Respondent further contends that by relying on Sections 5(7) and 5(8) of the Code, the Applicant cannot be treated as a Financial Creditor. Subsequently, it is also contended that the Applicant has failed to justify the computation of defaulted debt, i.e., Rs. 3.81 crores; thus, the claim amount is arbitrary, inflated and unsustainable. Further relying on the principles settled by the Hon’ble Supreme Court in the matter of Central Bank of India v. Ravindra & Ors. [(2002) 1 SCC 367].
d. It is also contended that the Applicant’s direct invocation of the personal guarantee, without making any bona fide or substantial efforts to recover the dues from the principal borrower, amounts to an abuse of the legal process and is violative of the principles of natural justice.
e. It is contended that there is an unexplained delay in the filing of the NeSL (National E-Governance Services Ltd.) certificate, which records the date of default as 14.09.2024, whereas as per Part III of the present petition, no specific default date is mentioned.
f. The Respondent also alleges the levying of additional interest pursuant to the alleged date of NPA.
g. With respect to the RP’s report, the Respondent/Personal Guarantor contends that the RP has failed to undertake a proper examination of the Petition in light of the contentions raised hereinabove. The Respondent further submits that, without conducting any examination or assigning any reasons, the RP has mechanically and erroneously recommended the admission of the Petition.
REJOINDER FILED BY THE APPLICANT/FINANCIAL CREDITOR
19. The Applicant, in response to the Respondent’s reply, filed a rejoinder on 19.08.2025, wherein the following submissions were given:
a. With respect to the non-stipulation of a specific date of default, the Applicant submits that the Repayment Schedules for all four loan facilities executed by the Corporate Debtor/Principal Borrower (bearing Nos. A9813943, A9814174, A9874677 and A9985776) are duly placed on record in the present Petition and they clearly outline the payment terms. The Respondent’s denial of the existence of a specified due date is, therefore, baseless and appears to be an afterthought intended to evade liability under the Personal Guarantee. The Applicant further submits that all the Repayment Schedules were duly acknowledged at the time of disbursal of the respective loan facilities and form an integral part of the contractual documents executed between the parties.
b. The Applicant also submits that the default in repayment under Agreement No. A9813943 occurred on 14.09.2023 and was declared NP A on 14.12.2023, which has clearly been reflected in the records annexed to the Company Petition, including the Statement of Accounts. The Respondent has not produced any document disputing the fact of the default. The invocation of the acceleration and cross-default clauses thereafter was in strict accordance with contractual terms and was necessitated by the default committed by the Corporate Debtor, which the Respondent has guaranteed. The relevant acceleration as well as cross-default clauses is reproduced below for ready reference:
i. Acceleration Clause:
“On and at any time at the occurrence of an Event of Default, the Lender may, by notice to the Borrower declare that all or part of the loan, together with, all amounts outstanding under the Repayment Schedule be immediately due and payable, whereupon they shall become immediately due and payable.”
ii. Cross default Clause:
“Notwithstanding anything to the contrary contained in this Agreement or the other related documents, a breach or default by the Borrower of any covenant or other term or condition contained in any of the Finance Schedule, shall, at the option of the Lender, be considered a default under all the Finance Schedules, in which even the Lender shall be entitled (but in no event required) to apply all rights and remedies of the Lender under the terms of this Agreement to all other Finance Schedules. Each of the Finance Schedules will be cross defaulted with each other Finance Schedule and all other existing and future Finance Schedules contracted by the Borrower with the Lender.”
c. With respect to the contention that the Applicant ought to proceed against the Principal Borrower/Corporate Debtor in the first instance, the Applicant relies upon the judgment of the Hon’ble Supreme Court in Laxmi Pat Surana v. Union Bank of India & Anr (2021)8 SCC 481, wherein it was held that, the right of cause of action would ensure the financial creditor to proceed against the principal borrower and guarantor in equal measure in case of default of debt acting jointly and severally. The obligation of the guarantor is coterminous and coextensive with that of the principal borrower to defray the debt as stated in section 128 of the Indian Contract Act, 1872. Accordingly, there is no legal impediment to the Applicant initiating proceedings against the Corporate Debtor and the Personal Guarantor simultaneously, as the liability of the Personal Guarantor arises from the guarantee executed in favour of the Applicant and is enforceable in accordance with the terms thereof, independently of the liability of the Corporate Debtor.
d. With respect to the objections raised regarding the maintainability of the present Petition, the Applicant submits that the Petition has been filed in compliance with the applicable provisions of the Insolvency and Bankruptcy Code, 2016, and the rules and regulations framed thereunder. The Applicant further submits that a detailed computation of the outstanding dues payable by the Corporate Debtor has been duly annexed to the Petition, substantiating the amount claimed by the Applicant.
e. The Applicant, relying upon the guarantee clause, already reproduced hereinabove, submits that the Respondent/Personal Guarantor became liable to discharge the payment obligations upon the Corporate Debtor’s failure to repay the instalment falling due on 14.09.2023 in full. Further, the Form-D issued by NeSL, filed along with the Section 7 petition against the Principal Borrower/Corporate Debtor, also records the date of default as 14.09.2023. The relevant excerpt of Form D issued by NeSL is reproduced below:
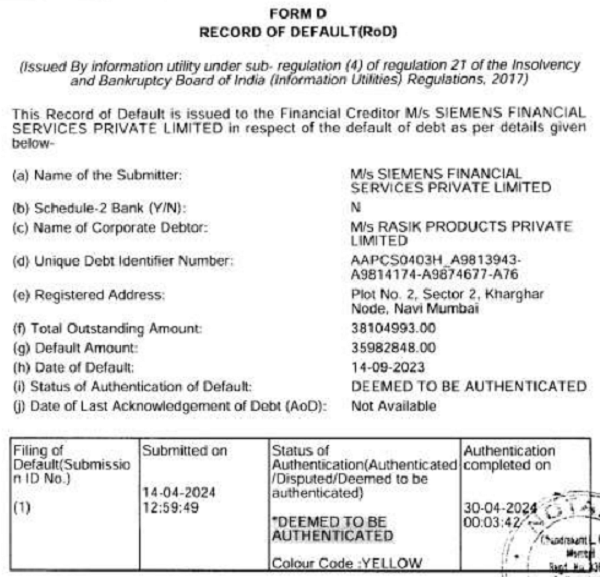
f. With respect to the objections raised by the Respondent/Personal Guarantor regarding the Statements of Accounts, the Applicant submits that the said objections are misconceived and devoid of merit. The allegation of illegal levy of interest has been raised without any supporting documentary evidence. The Applicant submits that the outstanding dues have been calculated transparently in accordance with the agreed contractual terms and the applicable provisions of the Finance Agreements, and the same have been duly communicated to the Respondent/Personal Guarantor.
g. The Applicant further submits that, vide email dated 27.06.2023, the Corporate Debtor had assured the Applicant that the outstanding dues would be cleared within a week. Thereafter, subsequent to the filing of the present Petition, the Corporate Debtor sought a meeting with the Applicant to discuss the settlement of the outstanding dues. Further, vide email dated 28.05.2025, the Respondent/Personal Guarantor assured the Applicant that the outstanding dues would be paid. The Applicant submits that the Respondent/Personal Guarantor had, on multiple occasions after the filing of the present Petition, approached the Applicant for settlement of the outstanding dues. The Applicant relies upon the aforesaid communications and take them as acknowledgements of the subsisting debt and submits that the same are relevant for determining the limitation period under Section 18 of the Limitation Act, 1963, subject to the applicable legal requirements.
FINDINGS OF THE TRIBUNAL
20. Heard the submissions made by the Learned Counsel for the Applicant, Resolution Professional, Respondent/ Personal Guarantor and perused the report submitted by the Resolution Professional.
21. As regards the issue of limitation, the date of default, as mentioned in Part III, pertains to September 2023, and the Principal Borrower/Corporate Debtor was classified as NPA on 14.12.2023. Further, the Personal Guarantee was invoked vide notice dated 16.02.2024 issued under Section 13(2) of the SARFAESI Act, 2002, in terms of Clause 11 of the finance agreements. Since no payment was made thereafter, the Applicant, owing to the continued default in repayment of the entire outstanding debt, filed the present Application on 19.04.2024, which is well within the period of three years prescribed under Article 137 of the Limitation Act, 1963, applicable to proceedings under the IBC, 2016.
22. As regards the objection of the Respondent/ Personal Guarantor, with respect to exhaustion of remedies against the Corporate Debtor, we find that this objection is not factually correct as in the present case, CIRP against the Corporate Debtor has already been initiated in CP(IB) No.38 of 2023 vide order dated 08.09.2025. However, it has also been settled law that for initiation of insolvency resolution process against the personal guarantor, initiation of CIRP against the Principal Borrower/ Corporate Debtor is not a condition precedent, as laid down by the Hon’ble Supreme Court in the case of Mahendra Kumar Jajodia v. State Bank of India, (2022) ibclaw.in 32 SC.
23. With respect to the second leg of the contention of the Respondent/ Personal Guarantor on the transparency in computation of default amount, we cannot accept the argument of the Respondent, as the computation of default amount is to be made by the RP itself at the stage of collation of claims of creditors after initiation of PIRP. At the stage of considering the application for admission it has to be only seen whether default amount is prima-facie more than the threshold limit. In the present case, we find that the default amount is over and above the threshold limit as prescribed under the Code, 2016, being more than Rs. 1 Crore.
24. With respect to the third leg of the contention of the Respondent/ Personal Guarantor on procedural irregularities in filing Form-C and subsequently not specifying date of default in the present Petition, we find that this argument of the Respondent/ Corporate Debtor is vague and cannot be accepted, as upon perusal of the present petition, it has been found, that it has fulfilled all the procedural requirements as specified under Section 95 of the Code, 2016 and corresponding Rules and Regulations.
25. Regarding the Contention of Respondent with respect to the specific date of default in the petition, we observe that the manner in which the date of default is stipulated in Form C does not constitute a valid ground for the rejection of a petition filed under Section 95 of the IBC, 2016. Furthermore, it is evident that the Applicant has duly satisfied the mandatory procedural prerequisites by invoking the guarantee against the Personal Guarantor vide Notice dated 16.02.2024 prior to the issuance of the statutory demand notice in Form B dated 12.03.2024 for the initiation of the PIRP.
26. With respect to the contention of the Respondent/ Personal Guarantor on delay and ambiguity in filing NeSL Records, this contention cannot be accepted as the NeSL records is not a condition precedent for filing a petition under Section 95 of IBC, 2016. It has already been settled that debt and default can be established through other documents in a Petition under Section 95 of IBC, 2016. Furthermore, in the present petition, the Financial Creditor has relied on establishing debt and default through Finance Agreements dated 31.01.2022, 31.01.2022, 22.09.2022 and 14.11.2022, Repayment Schedules annexed as Exhibits ‘H’, ‘K’, ‘N’ and ‘Q’, respectively, Statement of Accounts annexed hereto as Exhibits ‘R’, ‘S’, ‘T’ and ‘U’, respectively, and by further classifying the account of the Corporate Debtor as NPA on occurrence of default.
27. Having regard to the above, we are satisfied that the Application is filed well within limitation and maintainable in law.
28. As regards the debt and default, the report filed by the RP under Section 99 and material submitted by the Financial Creditor under section 95 have been considered.
29. As per the submissions and records placed before us through the present Application filed under Section 95, it is evident that the Personal Guarantor, viz., Mr. Rasik Khandelwal, executed personal guarantee in favour of the Financial Creditor through four Finance Agreements dated 31.01.2022, 31.01.2022, 22.09.2022 and 14.11.2022, thereby securing the loan facilities aggregating to Rs. 6.50 crores availed by the Corporate Debtor/Principal Borrower. The relevant Clause 11 of the Finance Agreements has already been reproduced in para 5 above, which stipulates the joint and several liability of the Respondent/Personal Guarantor in respect of the obligations secured thereunder.
30. The record further reflects that the Corporate Debtor failed to maintain financial discipline and failed to clear the remaining outstanding debt due to the Financial Creditor. Hence, the Financial Creditor issued a Section 13(2) Notice dated 16.02.2024 calling upon the Corporate Debtor and the Guarantor to jointly and severally repay outstanding dues of Rs. 3,81,04,993/- (including interest), thereby invoking the guarantee. However, neither was any payment made towards the outstanding dues nor was any reply received to the said notice; thereby, the outstanding debt remained due and payable.
31. Consequently, the Financial Creditor thereafter issued a statutory demand notice in Form B dated 12.03.2024 under Section 95(4)(b) of the Code to the Respondent /Personal Guarantor, demanding payment of Rs. 3,81,04,993/- due as on 14.02.2024. The Guarantor again failed to discharge the liability within 14 days of service of notice as mandated under the Code.
32. The RP has categorically recorded in its report that the defaulted amount, as prayed by the Applicant, remains due and payable, and that the Guarantor has committed default in making the payment despite service of notices. Considering these documents, and making further enquiries, as provided under section 99 of the Code, the RP u/s 99 has submitted the report vide I.A. No. 646/2024 recommending initiation of insolvency against the Respondent/ Personal Guarantor, which is considered by us while passing this order.
33. The provisions of Section 128 of the Indian Contract Act, 1872 render the liability of the guarantor co-extensive with that of the principal debtor, unless otherwise provided. The personal guarantee executed by the Respondent herein is absolute, unconditional, and irrevocable. Further, we find that the Respondent had undertaken to pay forthwith, upon demand, all sums payable by the Corporate Debtor/Principal Borrower under the facility documents. In the present case, despite the demand notice issued under section 95(4)(b) of the IBC, the Guarantor has failed to discharge his liability.
34. We have gone through the report dated 01.11.2024, filed by the RP, and we find that:
i. The Insolvency Petition satisfies the requirement of Section 95 of IBC, 2016 and has been filed in the requisite form, in terms of Section 95(1) read with Rule 7(1) and Rule 7(2) of the PIRP Rules, 2019, supported by requisite fee and documents.
ii. The Respondent Guarantor after being duly served with a demand notice dated 12.03.2024, has committed default in repayment of his debts; therefore, the requirement as set out under Section 95(4)(b) is satisfied.
iii. That the debts mentioned in the application are not excluded debts.
iv. That the Personal Guarantor is not eligible for a fresh start process provided under Chapter II of IBC, 2016.
35. Considering the above facts and circumstances and upon perusal of the documents on record, the CP (IB) No. 79/ALD/2024 filed under Section 95 of the IBC, 2016 is hereby admitted, and the Personal Insolvency Resolution Process (PIRP) stands initiated against Mr. Rasik Khandelwal viz. the Respondent herein. We hereby direct as under:
i. Initiate Insolvency Resolution Process against the Respondent/Personal Guarantor. The moratorium in relation to all the debts is declared, from today i.e. date of admission of the application, and shall cease to have effect at the end of the period of 180 days, or this Tribunal passes order on the repayment plan under Section 114 whichever is earlier as provided under Section 101 of IBC, 2016. During the moratorium period,
a. Any pending legal action or proceeding in respect of any debt shall be deemed to have been stayed, and
b. The creditors of the debtor shall not initiate any legal action or proceedings in respect of any debt; and
c. The debtor shall not transfer, alienate, encumber, or dispose of any of his assets or his legal rights or beneficial interest therein:
d. The provisions of this section shall not apply to such transactions as may be notified by the Central Government in consultation with any financial sector regulator.
ii. The Insolvency Professional viz. Mr. Amit Ojha (e-mail: [email protected] and Contact No.) having IBBI Registration No. IBBI/IPA-002/IPN01005/2020-2021/13275 with valid AFA till 30.06.2027 is further appointed as Resolution Professional for carrying out PIRP against the Personal Guarantor, Mr. Rasik Khandelwal. Accordingly, he is directed to cause a public notice to be published on behalf of the Adjudicating Authority within 7 days of passing this Order on the website of the NCLT Allahabad Bench, inviting claims from all Creditors, within 21 days of such issue The notice under Sub-Section (2) of Section 102 shall include: –
a. Details of the order admitting the application;
b. Particulars of the resolution professional with whom the claims are to be registered; and
c. The last date for submission of claims.
iii. The publication of notice shall be made in two newspapers, one in English and other in Vernacular, which have wide circulation in the State where the Corporate Debtor and Personal Guarantor resides. The Resolution Professional shall furnish two spare copies of the notice to the Registry for the record.
iv. The Resolution Professional, in exercise of the powers conferred under Section 104, shall prepare a list of creditors on the basis of:
a. The information disclosed in the application filed by the debtor under Sections 94 or 95 as the case may be, and
b. Claims received by the Resolution Professional under Section 102 within 30 days from the date of the notice. The debtor shall prepare a repayment plan under Section 105, in consultation with the Resolution Professional, containing a proposal to the Creditors for restructuring of his debts or affairs.
v. The repayment plan may authorize or require the Resolution Professional to:
a. Carry on the debtor’s, business or trade on his behalf or in his name: or
b. Realise the assets of the debtor; or
c. Administer or dispose of any funds of the debtor.
vi. The repayment plan shall include the following, namely;
a. Justification for preparation of such repayment plan and reasons based on which the creditors may agree upon the plan;
b. Provision for payment of fee to the Resolution Professional;
c. Such other matters as may be specified.
vii. The Resolution Professional shall submit the repayment plan along with her report on the plan to this Authority within a period of 21 days from the last date of submission of claims, as provided under Section 106.
viii. In case the Resolution Professional recommends that a meeting of the creditors is not required to be called, she shall record the reasons thereof. If the Resolution Professional is of the opinion that a meeting of the creditors should be summoned, she shall specify the details as provided under Section 106(3) of IBC, 2016. The date of meeting should not be less than 14 days or more than 28 days from the date of submission of the Report under subsection (1) of Section 106 of IBC, 2016, for which at least 14 days’ notice to the creditors (as per the list prepared) shall be issued by all modes. Such notice must contain the details as provided under the provisions of Section 107 of IBC, 2016.
ix. The meeting of the creditors shall be conducted in accordance with Sections 108, 109, 110 & 111 of IBC, 2016. The Resolution Professional shall prepare a report of the meeting of the creditors on repayment plan with all details as provided under Section 112 of IBC, 2016 and submit the same to this Tribunal, copies of which shall be provided to the Debtor and the Creditors. It is made clear that the Resolution Professional shall perform his functions and duties in compliance with the Code of Conduct provided under Section 208 of IBC, 2016.
x. The Resolution Professional shall submit his periodic reports before this Tribunal every 30 days.
xi. The Registry is directed to communicate the copy of order, to the concerned parties within seven working days and upload the same on the website immediately after the pronouncement of order.
36. In view thereof, the present CP(IB) No. 79/ALD/2024 is admitted, and PIRP is initiated against the Respondent/Personal Guarantor.
37. List CP(IB) No. 79/ALD/2024 on 16.11.2026 for filing of the progress report/further proceedings.