Aditya Birla Capital Limited Vs Unique Autosales Private Limited (NCLT Allahabad)
Summary: The National Company Law Tribunal, Allahabad Bench, admitted the Section 7 insolvency application filed by Aditya Birla Capital Limited, formerly Aditya Birla Finance Limited, against Unique Autosales Private Limited. The financial creditor had sanctioned a working-capital facility of Rs. 5 crore on 26 July 2023 under a loan agreement dated 27 July 2023. It alleged an outstanding default of Rs. 3,99,92,915 with a stated default date of 16 December 2024. The borrower admitted availing the facility and defaulting but attributed the failure to unforeseen financial difficulties, pandemic-related disruption and liquidity constraints, and referred to its efforts towards settlement or restructuring and the consequences of CIRP for business continuity and employment.
Addressing limitation, the Tribunal held that the petition filed on 23 September 2025 was within three years of the 16 December 2024 default, under Article 137 of the Limitation Act, 1963. It examined the sanction letter, facility agreement, repayment stipulations, account statement and the respondent’s express admissions. It held that the creditor–borrower relationship and repayment obligation established financial debt involving consideration for the time value of money under Section 5(8) of the IBC. Relying on the Supreme Court ruling in Innoventive Industries Ltd. v. ICICI Bank, the Bench found debt and default sufficiently established and the Section 7 application complete for admission.
The Tribunal commenced the corporate insolvency resolution process against Unique Autosales, declared a Section 14 moratorium and directed public announcement. Ms. Babita Jain was appointed interim resolution professional after verification of her authorisation and absence of pending disciplinary proceedings. The order also requires cooperation from the suspended board, auditors and public authorities, preservation and delivery of accounts and digital records, constitution of the committee of creditors, monthly progress reporting and a Rs. 1 lakh deposit by the financial creditor towards initial IRP expenses. The matter was listed for further proceedings on 30 October 2026.
Cases Discussed
- Innoventive Industries Ltd. v. ICICI Bank (Supreme Court of India) – (2018) 1 SCC 407. Relied upon for admission of a Section 7 petition where financial debt and default are established.
FULL TEXT OF THE ORDER OF NCLT ALLAHABAD
This Application has been filed on 23.09.2025 by ADITYA BIRLA CAPITAL LIMITED (hereinafter referred to as “Financial Creditor/Applicant”) under Section 7 of Insolvency and Bankruptcy Code, 2016 (hereinafter referred as “IBC/Code”) read with Rule 4 of the Insolvency and Bankruptcy (Application to Adjudicating Authority) Rules 2016 seeking to initiate Corporate Insolvency Resolution Process (hereinafter referred to as “CIRP”) against UNIQUE AUTOSALES PRIVATE LIMITED (hereinafter referred to as ‘Corporate Debtor/Respondent’) in Form 1 containing all the information as required in Part I, II, III, IV and V of the Form showing a total financial debt of Rs. 3,99,92,915/- with date of default specified as 16.12.2024.
2. The Part-I of the Application contains details of the Financial Creditor/Applicant and it is a company incorporated under the provisions of the Companies Act, 1956 with date of incorporation as 15.10. 2007 bearing CIN: L64920GJ2007PLC058890. The Address of the Registered office of the Financial Creditor is at Indian Rayon Compound, Veraval, Gujrat-362266, also having Branch Office at: D-17, Sector-03, Noida, Uttar Pradesh 201301 and at 1st Floor, Vijaya Building, Barakhambha Road, New Delhi-110001.
3. The Part-II of the Application contains details of the Corporate Debtor/Respondent and it is a company incorporated under the provisions of the Companies Act, 1956 with date of incorporation as 26.03.2011 bearing CIN: U74900UP2011PTC044182. The Address of the registered office of the Corporate Debtor is 180, Pura Pitai. Kotwali Nagar, Pratapgarh, Uttar Pradesh-230001.
4. In Part – III of the application, the Financial Creditor/Applicant has proposed Ms. Babita Jain having Registration No. IBBI/IPA002/IP-N00321/2017-18/10926 to act as the Interim Resolution Professional (“IRP”).
5. In Part – IV of the Application, the Financial Creditor/Applicant stated that the amount in default is Rs.3,99,92,915/-. The Date of Default is mentioned as 16.12.2024.
6. In Part V of the application, the following documents have been referred to substantiate the debt disbursed to the Corporate Debtor/Respondent.
a. Record of Default issued by information utility dated 16.12.2024.
b. Copy of the sanction letter dated 26.07.2023 along with loan facility agreement dated 27.07.2023 entered between the parties.
c. Copy of legal demand notice dated 27.03.2025 issued by the Financial Creditor.
d. Copy of loan recall notice dated 27.07.2025 issued by the Financial Creditor to the Corporate Debtor along with Mr. Rakesh Kumar Shukla and Smt. Pushpanjali Shukla.
e. Copies of the statement of accounts of the Respondents maintained with the Financial Creditor.
7. It is submitted that Corporate Debtor/Respondent, as the borrower sought financial assistance in the form of a term loan from the Financial Creditor/Applicant. Pursuant to the request made, the Financial Creditor issued Sanction Letter dated 26.07.2023 wherein a financial facility for a total amount of Rs. 5,00,00,000/- was sanctioned.
8. As per the terms and conditions of the Sanction Letter, the financial facility so sanctioned was to be utilized for the purpose of working capital requirements. Thereafter, the parties entered into a Loan Facility agreement dated 27.07.2023 wherein the terms including regular and timely repayment of the Loan Amount were agreed.
9. Subsequently, due to the financial indiscipline and failure to abide by the repayment terms and conditions, the Financial Creditor/Applicant issued a Legal Demand Notice dated 27.03.2025 to the Corporate Debtor/Respondent thereby demanding the repayment of the amount Rs. 3,78,53,194.96/-. Further, aggrieved by the conduct of the Corporate Debtor/Respondent, the Financial Creditor/Applicant classified the loan account of the Corporate Debtor/Respondent as Non-Performing Asset (“NPA”) on 31.03.2025. However, neither any response nor any payment was received from the Corporate Debtor/Respondent.
10. The Financial Creditor/Applicant further relies on the statement of accounts to show that that the Corporate Debtor/Respondent had stopped paying the Equated Monthly Installments (“EMI”) which at present remains payable and outstanding. Consequently, a Loan Recall notice was issued by the Financial Creditor/Applicant dated 23.07.2025 to pay the entire outstanding of Rs. 3,99,92,915/- as on 18.07.2025. However, neither any response nor any payment was received from the Corporate Debtor/Respondent.
11. In light of the continuing default, the Financial Creditor/Applicant has filed the present application seeking initiation of the CIR Process against the Corporate Debtor/Respondent.
REPLY ON BEHALF OF THE CORPORATE DEBTOR/RESPONDENT.
12. The Corporate Debtor/Respondent filed a Reply dated 02.04.2026, in the present application as discussed in foregoing paras, making the following submissions in response to the averments made:
a. At the outset, the Corporate Debtor/Respondent admits that a financial facility of Rs. 5 crores was availed from the Financial Creditor/Applicant and subsequent default had occurred in repayment of the said facility.
However, the default occurred was unintentional and non-wilful but has occurred due to unprecedented and unavoidable circumstances beyond their control. Further the impact of Covid-19 pandemic worsened the business operations of the Corporate Debtor/Respondent resulting into severe liquidity crunch.
b. The Corporate Debtor/Respondent also contends that they had been making continuous efforts to regularize the account and explore options i.e., restructuring/settlement.
c. The Corporate Debtor/Respondent lastly contends that the initiation of the CIRP in the present matter would adversely affect the running of the business, resulting into loss of employment and ultimately value erosion of the assets of the Corporate Debtor/Respondent.
REJOINDER FILED BY THE FINANCIAL CREDITOR/APPLICANT
13. The Financial Creditor/Applicant, in response to the Reply, filed a Rejoinder dated 30.05.2026, wherein it was submitted that the Corporate Debtor/Respondent itself has admitted the existence of the debt and default, which are the essential pre-requisites for adjudication of an application under Section 7 of the Code. It was further submitted that the pleas relating to the COVID-19 pandemic or business losses cannot constitute a valid legal defence to an application under Section 7 of the Code. The Financial Creditor/Applicant also denied the alleged efforts made by the Corporate Debtor towards restructuring and settlement. Further, through the said Rejoinder, the Financial Creditor/Applicant placed on record the valid Authorization for Assignment (“AFA”) certificate of the proposed IRP.
FINDINGS OF THIS TRIBUNAL:
14. We have heard the submissions of Ld. Counsels of both the parties and perused the documents on record. After considering the arguments advanced by the respective learned counsels, the main issues to be decided are as follows:
a. Whether the application is filed within the period of limitation.
b. Whether there is debt and default within the meaning of the under Section 7 of the Code.
15. With respect to Issue I, upon consideration of the material placed on record, it is observed that the present Petition has been filed on 23.09.2025. The date of default, giving rise to the cause of action for filing the present Application, is 16.12.2024, when the Corporate Debtor/Respondent failed to repay the overdue amount, and its loan account was subsequently classified as NPA on 31.03.2025. Thus, reckoning the period of limitation from the date of default, i.e., 16.12.2024, the present Application has been filed well within the period of three years prescribed under Article 137 of the Limitation Act, 1963.
16. With respect to Issue II, upon perusal of the material on record, in order to establish debt and default, the Financial Creditor/Applicant relies on the Sanction Letter dated 26.07.2023 along with loan agreement dated 27.07.2023. Pursuant to the said Loan Agreement, a Loan Facility of Rs. 5,00,00,000/- was sanctioned to the Corporate Debtor/Respondent on 26.07.2023. The relevant clauses of the loan agreement along with its Schedule I thereto, are reproduced below:
“3. Grant of Facility
…
3.2 The disbursement under this Facility will happen in the following manner:
3.2.1 (a) Where the Debt in relation to such Invoice(s) or
Disbursement Request with all other amounts oustanding under the Facility is within the Permitted Limit, the Lender shall disburse the entire Invoice Payment.
(b) Where the Debt in relation to such Invoice(s) or Disbursement Request together with all other amounts outstanding under the Facility exceeds the Permitted Limit, the Lender, shall disburse part of the Invoice Payment or Disbursement Request as it deems fit and the balance payment comprising the invoice payment shall be made by the Buyer directly to the Seller, or in the altemate, the balance payment comprising the Invoice payment or Disbursement Request shall be payable to the Seller immediately upon the Buyer paying the Debt amount to the Lender. Provided that in the event where the Debt is not repaid in full by the Buyer along with any interest and/or charges that may be levied thereon, the Lender shall not be under any obligation to disburse such balance amount of the Invoice payment or Disbursement Request to the Seller.
….
3.2.3 The Buyer agrees that the physical or scanned copies of the Approved Invoice(s) or Disbursement Request with respect to the Buyer will be sent by the Seller/Buyer directly to the Lender whenever demanded by the Lender at its sole discretion. The Buyer hereby authorizes the Lender to make payment to the Seller at the request of Seller for invoices raised on the Buyer without referring the invoices to Buyer or a written Disbursement Request from the Seller and the Buyer will be bound to repay the same on or before the due date to the Lender-as provided for herein. The Buyer also agrees that it/he/she will not dispute any such payment by Lender to the Seller without referring to Buyer. The Buyer further agrees that the Seller will not be referring the Invoice(s) to the Buyer before or after sending the same to the Lender.
4. DUE DATE FOR PAYMENT
In the case of Invoice(s) which has been approved or Disbursement Request in respect of which any disbursement has been made, the amount of Debt as Indicated therein shall fall due and be payable by the Buyer upto the last date of the credit period as set out in Item 4(ii) of schedule 1* or such other day as deemed fit by Lender and communicated by the Lender to the Buyer.
*Item 4(ii) of Schedule 1 is reproduced herein fore ready reference:
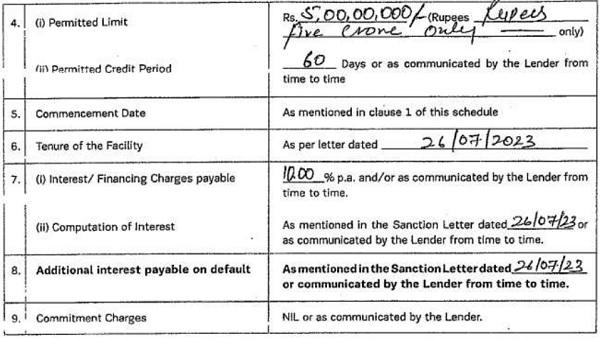
5. REPAYMENT AND RECOVERY
5.1. Subject to the other provisions of this Agreement, the method of recovery of the amounts due under the Facility shall be as follows:
5.1.1. The Buyer hereby confirms and acknowledges that he/she/it has been irrevocably and unconditionally instructed by the Seller (in terms of the Letter of Intent) to deposit the amounts due under the relevant Invoice(s) or under the Disbursement Request to the Lender in the manner designated by the Lender for this purpose. The Buyer hereby furnishes his/its unconditional and irrevocable acceptance of these instructions by virtue of signing this Agreement;
5.1.2. The Lender shall forthwith on such deposit by the Buyer be entitled to appropriate the same towards the dues under the Disbursement Request or under Invoice Payment on a first in first out basis towards settlement of principal amounts, interest or additional Interest due from the Buyer to the Lender at the Lender’s discretion;
5.1.3. In payment of the dues to the Lender, the Buyer agrees that all payments to be made by the Buyer to the Lender shall be by way of ECS mandate by the Buyer in favour of the Lender on a scheduled bank at the city in which the office of the Lender is situated unless any other place or such other account has been notified by the Lender to the Buyer in advance in writing. Provided however, payment made directly to the Lender by real time gross settlement (RTGS) to the account of the Lender may be accepted as a mode of payment.
5.1.4. The Buyer agrees and understands that it/he will be required to make payment to the Lender under the Approved Invoices, even if: (a) the Goods supplied by the Seller to the Buyer are returned by the Buyer to the Seller or the Goods were damaged/lost in transit; or (b) the Services are deficient in any way or are not satisfactory or do not confirm to the requirements of the Buyer.”
17. The Financial Creditor/Applicant also substantiates the existence of the debt and default, by relying upon the statement of account for the period from 01.04.2024 to 06.08.2025, which records the disbursal of the sanctioned loan amount to the Corporate Debtor/Respondent. As reflected in the said statement of account, the sanctioned loan amount was disbursed on 31.03.2024 and the said amount continues to remain outstanding, due and payable by the Corporate Debtor/Respondent as on 06.08.2025.
18. In light of the aforesaid contractual provisions and statement of accounts, we are of the considered view that the contractual arrangement entered into between the parties, i.e., the Financial Creditor/Applicant and the Corporate Debtor/Respondent, unequivocally establishes the creditor–borrower relationship between them. The corresponding obligation of the Corporate Debtor/Respondent to repay the amounts disbursed under the Loan Facility within the stipulated period further demonstrates that the amounts disbursed by the Financial Creditor/Applicant constitute a financial obligation of the Corporate Debtor/Respondent to repay the same as per the stipulated terms and conditions. Additionally, the said transaction, being a financial facility advanced against the consideration for the time value of money, falls within the ambit of “financial debt” as defined under Section 5(8) of the Code, thereby evidencing the subsisting debt and default on the part of the Corporate Debtor/Respondent.
19. We further observe that the existence of the financial debt and the occurrence of default are further fortified by the categorical admissions made by the Corporate Debtor/Respondent in its Reply. The Corporate Debtor/Respondent has, inter alia, admitted as follows:
“3. That The Corporate Debtor admits that a financial facility of approximately Rs. 5,00,00,000/- was availed from the Financial Creditor and that a default has occurred in repayment of the said financial debt.
…
15. That in reply to para no 9 to 12 It is admitted that there has been delay/default in repayment and that the account was classified as NPA and demand/recall notice was issued.”
20. The stand taken by the Respondent/Corporate Debtor was further recorded in the order passed during the hearing held on 09.09.2026. The relevant extract of the said order is reproduced hereinbelow for ready reference:
“2. Ld. Counsel representing the Respondent/ Corporate Debtor at the outset states that due to unforeseen circumstances, the Respondent/ Corporate Debtor is undergone some financial distress, and therefore incurred losses, due to which the default has occurred.”
21.The aforesaid admissions are material and unequivocally acknowledge both the availing of the financial facility and the occurrence of default in repayment. The admission regarding classification of the account as NPA and issuance of the demand/recall notice further corroborates the default. Hence, in our considered opinion the Sanction Letter, the Loan Agreement, the statement of account evidencing disbursal and the outstanding amount, coupled with the categorical admissions made by the Corporate Debtor/Respondent in its Reply, the existence of the financial debt and the occurrence of default stand established.
22. After considering the entire facts and circumstances of the case so far discussed and taking into account the decision of the Apex Court in the case of Innoventive Industries Ltd. v. ICICI Bank (2018) 1 SCC 407 in which it has been already held that a petition under Code be admitted if there is clear debt and default, we are of the considered opinion that in the present case, default on repayment of the debt has occurred and the Section 7 Petition filed by the Financial Creditor is complete in all aspects providing all the details of debt and default as required in Part IV of the Application in Form-I and attaching all the necessary supporting documents as required in Part V of the Application. Considering that all the above criteria are fulfilled as required under the Code, we find that this Application deserves to be admitted u/s 7 for initiating CIRP against the Corporate Debtor/Respondent. Accordingly, this Tribunal admits this petition and orders to initiate the Corporate Insolvency Resolution Process against the Corporate Debtor i.e., M/s Unique Autosales Private Limited.
23. We note that the Financial Creditor has proposed the name of Ms. Babita Jain having Registration No. IBBI/IPA002/IP-N00321/2017-18/10926, Email ID: [email protected] as the IRP, who has also filed her consent annexed at Annexure A-15. The Law Research Associate of this Tribunal, Ms. Shriya Pandey, has checked the credentials of Ms. Babita Jain, and found that there are no disciplinary proceedings pending against the proposed Insolvency Professional and also there is nothing adverse against her. Upon verification from the website of IBBI, it is found that Insolvency Professional holds valid authorization till 31.12.2026. After considering these details, we appoint Ms. Babita Jain having registration No. IBBI/IPA002/IP-N00321/2017-18/10926, as IRP.
24. Accordingly, this application is admitted u/s 7 of the Code, 2016, under the following terms and conditions.
i. The Application filed by the Financial Creditor under Section 7 of the Code for initiating the Corporate Insolvency Resolution Process against the Corporate Debtor i.e., M/s Unique Autosales Private Limited is hereby admitted.
ii. We hereby declare a moratorium and public announcement in accordance with Sections 13 and 15 of the Code.
iii. This Adjudicating Authority hereby appoints Ms. Babita Jain to act as the IRP under Section 13(1)(c) of the Code as decided by us in para 23 above.
iv. The IRP shall cause a public announcement for the initiation of the CIRP against the Corporate Debtor and call for the submission of claims under Section 15. The public announcement referred to in clause (b) of subsection (1) of Section 15 of the Code shall be made immediately.
v. Moratorium under Section 14 of the Code has commenced from the date of this order prohibiting the following:
a. The institution of suits or continuation of pending suits or proceedings against the Corporate Debtor including execution of any judgment, decree or order in any court of law, tribunal, arbitration panel or other authority;
b. Transferring, encumbering, alienating or disposing of by the Corporate Debtor any of its assets or any legal right or beneficial interest therein;
c.Any action to foreclose, recover or enforce any security interest created by the Corporate Debtor in respect of its property including any action under the Securitization and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 (54 of 2002);
d. The recovery of any property by an owner or lessor where such property is occupied by or in the possession of the Corporate Debtor.
vi. Apart from above prohibitions in respect of the corporate debtor, it is further directed that the supply of essential goods or services to the corporate debtor as may be specified, shall not be terminated or suspended or interrupted during the moratorium period.
vii. The provisions of Section 14(3) shall, however, not apply to such transactions as may be notified by the Central Government in consultation with any financial sector regulator and to a surety in a contract of guarantee to a corporate debtor.
viii. The order of moratorium shall have effect from the date of this order till completion of the CIRP or until this Bench approves the resolution plan under sub-section (1) of Section 31 or passes an order for liquidation of the corporate debtor under Section 33 as the case may be.
ix. The IRP is directed to take steps as mandated under section 13 and 15 of the Code for making public announcement about the commencement of CIRP against the Corporate Debtor and moratorium against it u/s 14, and also take necessary actions as per sections 17, 18, 20 and 21 of Code, 2016.
x. The IRP shall after collation of all the claims received against the Corporate Debtor and the determination of the financial position of the Corporate Debtor and to constitute a Committee of Creditors (hereinafter referred as “COC”) and shall file a report certifying the constitution of the COC to this Tribunal on or before the expiry of thirty days from the date of his appointment, and shall convene the first meeting of the COC within seven days of filing the report of the constitution of the COC.
xi. As the IRP appointed herein is proposed by this Tribunal, she will ensure that her written consent in Form-2 shall be duly submitted before this Tribunal.
xii. The COC in its first meeting shall appoint a Resolution Professional (hereinafter referred as “RP”) as per the provision of section 22(2).
xiii. The Suspended Board of Directors of the corporate debtor is directed to give to IRP/RP complete access to the Books of Accounts of the corporate debtor maintained under section 128 of the Companies Act. In case, the books are maintained in the electronic mode, the Suspended Board of Directors are to share with the IRP/RP all the information regarding maintaining the Backup and regarding service provider kept under Rule 3(5) and Rule 3(6) of the Companies Accounts Rules, 2014 respectively as effective from 11.08.2022, especially the name of the service provider, the internet protocol of the service provider and its location, and also address of the location of the Books of Accounts maintained in the cloud. In case, accounting software for maintaining the books of accounts is used by the corporate debtor, then IRP/RP is to check that the audit trail in the same is not disabled as required under the notification dated 24.03.2021 of the Ministry of Corporate Affairs.
xiv. The Statutory Auditor is directed to share with the RP the audit documentation and the audit trails, which they are mandated to retain pursuant to SA-230 (Audit Documentation) prescribed by the Auditing and Assurance Standards Board ICAI.
xv. The IRP/RP is directed to take custody and control of all the records of information relating to assets of the Corporate Debtor, its Books of Account in physical form or the computer systems storing the electronic records at the earliest in accordance with the provision of Regulation 3A of IBBI (Insolvency Resolution Process for Corporate Persons) Regulations, 2016 (hereinafter referred to as “CIRP Regulations, 2016”).
xvi. The Financial Creditor shall also provide necessary assistance to IRP/RP in obtaining the necessary information about the Corporate Debtor as envisaged in Regulation 4(3) of the CIRP Regulations, 2016.
xvii. In case of any non-cooperation by the Suspended Board of Directors or the Statutory Auditors, IRP/RP may take the help of the police authorities to enforce this order. The concerned police authorities are directed to extend help to the IRP/RP in implementing this order for the retrieval of relevant information from the systems of the corporate debtor.
xvii. The IRP/RP may take the assistance of Digital Forensic Experts empanelled with this Bench/IBBI/MCA for this purpose.
xix. The Suspended Board of Directors is also directed to hand over all user IDs and passwords relating to the corporate debtor, particularly for government portals, for various compliances.
xx. The IRP/RP is also directed to make a specific mention of noncompliance, if any, in this regard in his status report filed before this Adjudicating Authority immediately after a month of the initiation of the CIRP.
xxi. The IRP/RP is directed to approach the Government Departments, Banks, Corporate Bodies and other entities with requests for information/documents available with those authorities’/institutions/others pertaining to the Corporate Debtor which would be relevant in the CIR proceedings.
xxii. The IRP/RP is directed to approach all the concerned Government Departments and authorities as discernible from the books of account of the Corporate Debtor requesting them to file claims if any amount is outstanding against the Corporate Debtor.
xxiii. The Government Departments, Banks, Corporate Bodies and other entities are directed to render the necessary information and cooperation to the IRP/RP to enable him to conduct the CIR Proceedings as per law.
xxiv. The IRP/RP shall collate the data obtained from (a) the claim(s) made before it and (b) information gathered from the records including those maintained by the Corporate Debtor.
xxv. The IRP/RP is further directed to send regular progress reports to this Tribunal every month.
25. We direct the Financial Creditor to deposit a sum of Rs. 1,00,000/-with the
IRP, to meet out the expenses to perform the functions assigned to him in accordance with Regulation 6 of CIRP Regulations, 2016. The amount, however, is subject to adjustment by the CoC as accounted for by the IRP on the conclusion of CIRP.
26. A certified copy of the order shall be communicated to both the Financial Creditor/Applicant and the Corporate Debtor/Respondent. The Ld. counsel for the Financial Creditor/Applicant shall deliver a certified copy of this order to the IRP forthwith. The Registry is also directed to send a certified copy of this order to the IRP at his e-mail address forthwith.
27. Accordingly, CP (IB) No. 109/ALD/2025 stands admitted for initiating CIRP against the Corporate Debtor i.e., M/s Unique Autosales Private Limited.
28. List the matter on 30.10.2026 for filing of the progress report/further proceeding.