
Income Tax
Log in to FollowLatest Income Tax news, articles, notifications, circulars and case laws covering ITR, assessments, deductions, TDS, capital gains, tax audit, appeals and compliance.

ITAT Mumbai: Accommodation Entry Commission Rate Cut to 0.47% in Section 153C Cases
ITAT Mumbai: R&D Deduction Allowed Without DSIR Quantification for AY 2016-17

Income Tax Rules 2026: Key Changes in Advance Pricing Agreements
CBDT Prescribes Forms 154 & 155 for ITCC of Non-Domiciled Persons
TRC for Resident Taxpayers: Form 42 Application, Form 43
DTAA Benefits: Form 41 and TRC Required for Non-Residents

Reassessment Void Without Mandatory Section 143(2) Notice: Karnataka HC
ITAT Raipur: Reassessment Quashed for Non-Service of Section 143(2) Notice
ITAT Mumbai: Estate’s Taxation at Individual Slab Rates Remanded to Verify Sole Executor Under Will
ITAT Mumbai: Estate of Deceased Taxable at Normal Slab Rates, Not Maximum Marginal Rate
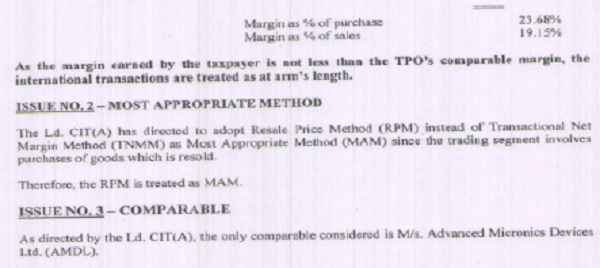
ITAT Bangalore: Trading & Software TP Adjustments Deleted Due to Comparability & 3% Range

ITAT Bangalore: Turnover & RPT Filters Applied, Functionally Dissimilar Comparables Excluded

Final Assessment Without Draft Order under Section 144C Is Void: Bombay HC
Demonetisation Cash Deposits from Recorded Sales Not Taxable under Section 115BBE: ITAT Chennai
Income Tax is TaxGuru’s extensive resource for developments under India’s direct tax laws. This category covers Income-tax provisions, rules, notifications, circulars, instructions, judicial decisions and practical compliance issues. Readers can explore articles and case laws on income-tax returns, assessments, reassessment, deductions, exemptions, capital gains, business income, TDS and TCS, tax audit, penalties, appeals, international taxation and other direct tax matters. The category also covers important CBDT announcements, tax deadlines, return filing developments and changes affecting individuals, businesses and other taxpayers. Chartered Accountants, advocates, tax professionals, companies and taxpayers can use this section to follow legislative, administrative and judicial developments and research important Income Tax issues and precedents.

