
Blueview Tradevin Pvt. Ltd. Vs ITO (ITAT Kolkata)
Summary: In Blueview Tradevin Pvt. Ltd. Vs ITO, the Income Tax Appellate Tribunal, Kolkata Bench, considered an appeal filed by the assessee against the order dated 4 April 2017 passed by the Commissioner of Income Tax (Appeals)-23, Kolkata, under Section 250 of the Income Tax Act, 1961, for Assessment Year 2012-13. The assessee filed its appeal before the Tribunal on 13 August 2024, resulting in a delay of 2,628 days. Although the Registry issued a defect notice identifying the delay, the assessee did not submit a petition seeking condonation. The Tribunal also found that Column No. 6 of the appeal was incorrectly completed and that the date of service or communication of the appellate order had not been correctly entered in Column 3(c).
The appeal had been listed for hearing on 14 October 2024, 11 December 2024 and 12 February 2025. Instead of rectifying the defects, the assessee submitted adjournment applications. One application dated 7 January 2025 was filed by Shri Raj Kumar Gupta, described as Director/Authorised Representative, while another dated 9 December 2024 was filed by Shri Kunal Goswami, also described as Director/Authority of the assessee company. The appeal itself had been verified by Shri Raj Kumar Gupta. For the hearing scheduled on 26 March 2025, another adjournment application dated 24 March 2025 was filed, citing the non-availability of the authorised representative. No representative appeared for the assessee, while the Revenue was represented by Shri Anindya Kumar Bandopadhyay, Additional Commissioner of Income Tax, Senior Departmental Representative.
The Tribunal examined the adjournment applications and observed that the signature of Shri Kunal Goswami on the latest application appeared prima facie different from the signature on the earlier application. This raised doubts concerning the adjournment request itself. More importantly, despite repeated opportunities, the assessee had neither explained the substantial delay nor filed the required condonation petition or corrected the defects identified by the Registry. The Tribunal therefore found no basis for admitting the appeal and dismissed it in limine, without examining the underlying tax dispute on merits. The order was pronounced in open court on 26 March 2025.
FULL TEXT OF THE ORDER OF ITAT KOLKATA
This is an appeal filed by the assessee against the order of the Ld. Commissioner of Income Tax (Appeals)-23, Kolkata [hereinafter referred to as “the Ld. CIT(A)”] vide Appeal No. 121/CIT(A)-23/Tech-2/16-17 dated 04.04.2017 passed u/s. 250 of the Income Tax Act, 1961 (hereinafter referred to as “the Act”) for AY 2012-13.
2. None appeared on behalf of the assessee (adjournment application has been filed) and Shri Anindya Kumar Bandopadhyay, Addl. CIT, Sr. DR appeared on behalf of the revenue.
3. An application for adjournment dated 24.03.2025 has been placed on file mentioning the following grounds:
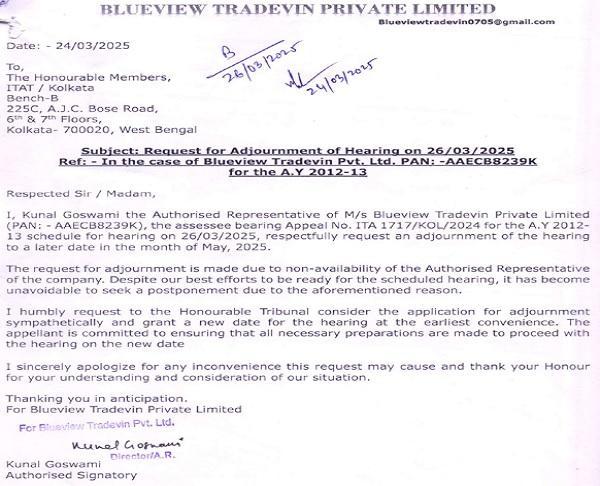
4. A perusal of the said application shows that the appeal is time barred by 2628 days. No condonation of delay petition has been filed. It was mentioned here that the Ld. CIT(A) has passed the order on 04.04.2017. The assessee has filed his appeal on 13.08.2024. Defect notice has been issued to the assessee mentioning that the appeal is time barred by 2628 days. We find that Column No. 6 is also wrongly filled. Also, condonation petition for delay is not filed. Furthermore, the date of service or communication of order in column 3 (c) is not correctly filled in. The appeal has been posted on multiple occasions for 14.10.2024, 11.12.2024 and 12.02.2025. Adjournment application has been filed on 07.01.2025 by one Shri Raj Kumar Gupta as the Director/A.R for the assessee company. Adjournment application has been filed on 09.12.2024 by one Shri Kunal Goswami as the Director/Authority of the assessee company. The appeal has been verified by Shri Raj Kumar Gupta. The present adjournment application dated 24.03.2025 is also signed by one Shri Kunal Goswami, Director/A.R. It would be worthwhile herein to extract the adjournment application dated 09.12.2024 which is as follows:
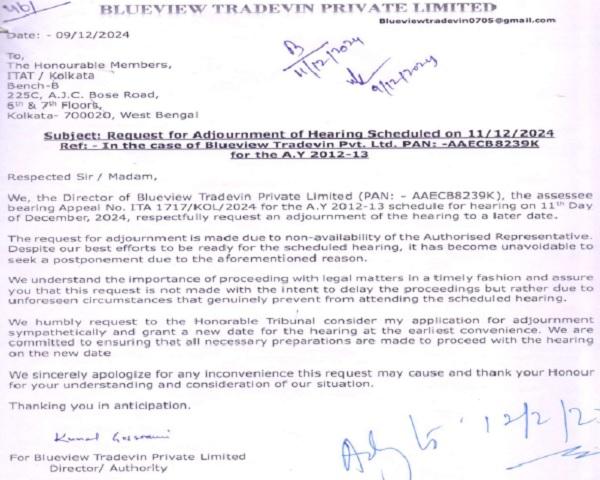
5. The adjournment letter filed dated 23.03.2025 prima facie shows that the signature of the said Kunal Goswami differs. Thus, firstly, the adjournment application itself is in question and secondly even after multiple opportunities have been granted, the assessee has not rectified the defects in the appeal filed and, therefore, as the delay has not been explained nor has any defect been rectified, the appeal filed by the assessee is dismissed in limine.
6. In the result, the appeal of the assessee stands dismissed.
Order dictated and pronounced in the open court.




