
Kaizen Motoventures Private Limited Vs ACIT (ITAT Raipur)
The Income Tax Appellate Tribunal, Raipur, allowed the appeal of Kaizen Motoventures Private Limited for Assessment Year 2019-20 against the order of the CIT(A)/NFAC dated 13 March 2026. The assessee challenged the validity of the show-cause notice issued under Section 148A(b) of the Income-tax Act, 1961, on 3 March 2023, requiring compliance by 10 March 2023. The assessee argued that, when both the date of issue and the compliance date were excluded, the notice afforded only six clear days rather than the mandatory minimum of seven clear days. The challenge therefore concerned the jurisdictional validity of the notice and the reassessment founded upon it.
The Tribunal referred to its earlier decision in DCIT-1(1), Raipur Vs Avani Ferro Alloys Pvt. Ltd., ITA Nos. 88 to 91/RPR/2025, decided on 6 August 2026. In that matter, the Assessing Officer had issued a notice on 16 March 2022 calling for a response by 23 March 2022. The Revenue maintained that seven days had been granted, whereas the assessee argued that the first and last dates must be excluded. The Bench accepted the requirement of seven clear intervening days and held the defective notice invalid.
The quoted ruling in Avani Ferro Alloys drew support from PCCIT Vs Smt. Komarla Yogendra Keertana, reported at (2025) 307 Taxman 106 (Karnataka High Court), Bijendra Singh Vs PCCIT, reported at (2025) 478 ITR 493 (Rajasthan High Court), and Atul Mahavirprasad Paldecha Vs ITO, reported at (2025) 307 Taxman 331 (Gujarat High Court). The Rajasthan High Court had applied the Supreme Court ruling in Pioneer Motors (Private) Ltd. Vs Municipal Council, Nagercoil, AIR 1967 SC 684, explaining that when legislation requires a period of “not less than” a specified number of days, both terminal dates are excluded from the computation. The Tribunal also referred to the coordinate Bench decision in Atal Agrawal Vs ITO-1, Raigarh, dated 3 September 2026.
Following those authorities and examining the notice in the present appeal, the Tribunal held that the mandatory statutory response period had not been afforded. It declared the Section 148A(b) notice invalid and void ab initio, quashed the assessment order arising from that notice, and held the subsequent proceedings non-est in law. The other grounds were treated as academic and were not adjudicated. The assessee’s appeal was allowed, and the order was pronounced in open court on 22 September 2026.
Cases Discussed
- DCIT-1(1), Raipur Vs Avani Ferro Alloys Pvt. Ltd. — ITA Nos. 88 to 91/RPR/2025, ITAT Raipur, 06.08.2026. Followed on the seven-clear-day requirement.
- PCCIT Vs Smt. Komarla Yogendra Keertana — (2025) 307 Taxman 106 (Karnataka High Court). Cited for invalidity of a notice allowing insufficient response time.
- Bijendra Singh Vs PCCIT — (2025) 478 ITR 493 (Rajasthan High Court). Followed on excluding both terminal dates.
- Pioneer Motors (Private) Ltd. Vs Municipal Council, Nagercoil — AIR 1967 SC 684 (Supreme Court). Interpreted statutory periods expressed as “not less than” a specified duration.
- Atul Mahavirprasad Paldecha Vs ITO — (2025) 307 Taxman 331 (Gujarat High Court). Cited for the mandatory minimum response period.
- Atal Agrawal Vs ITO-1, Raigarh — ITA No. 231/RPR/2026, ITAT Raipur, 03.09.2026. Coordinate Bench decision applying the same principle.
FULL TEXT OF THE ORDER OF ITAT RAIPUR
The present appeal preferred by the assessee emanates from the order of the Ld.CIT(Appeals)/NFAC, Delhi dated 13.03.2026 for the assessment year 2019-20 as per the grounds of appeal on record.
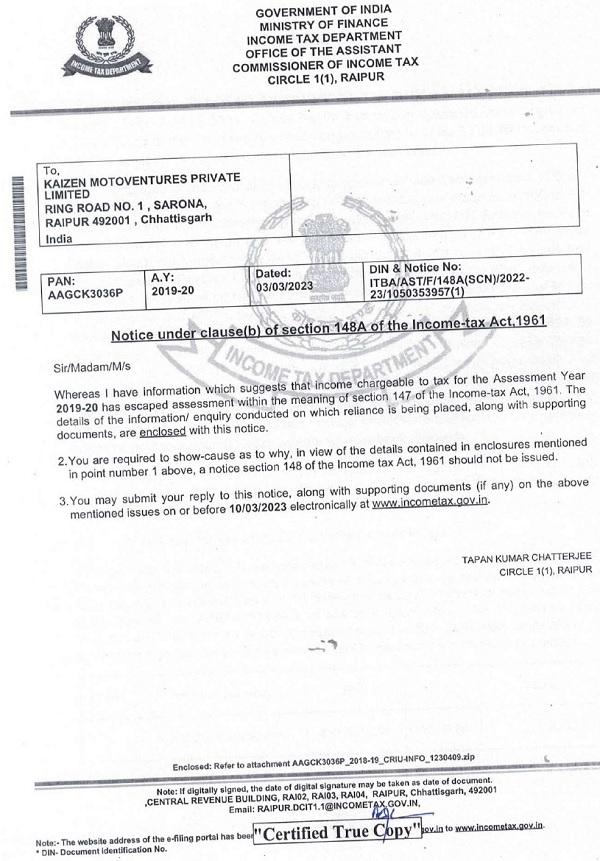
2. The contention in law assailed by the Ld. Counsel for the assessee is that notice u/s.148A(b) of the Income Tax Act, 1961 (for short ‘the Act’), dated 03.03.2023 does not provide mandatory clear cut 7 days time to the assessee for his response. That in effect, the date of issuance of notice i.e. 03.03.2023 and date of compliance sought from the assessee i.e.10.03.2023, therefore, in between there is only clear cut 6 days which is 1 day short of mandatory requirement of clear cut 7 days time in the notice issued u/s.148A(b) of the Act. For the sake of completeness, notice u/s.148A(b) of the Act, dated 03.03.2023 is extracted as follows:
3. We find that similar issue has been dealt with by this Bench in favour of the assessee and against Revenue recently in the case of DCIT-1(1), Raipur Vs. Avani Ferro Alloys Pvt. Ltd, ITA Nos.88 to 91/RPR/2025, dated 06.08.2026 wherein it was held and observed as follows:
“60. The Ld. Counsel for the assessee submitted that the notice issued u/s 148A(b) on 16.03.2022 is void ab initio. He submitted that the notice called for a response on or before 23.03.2022 which does not constitute a clear 7 days as required by the mandatory provisions of section 148A(b). He submitted that the statutory mandate requires a period of ‘not less than seven days’ to be provided for compliance. He submitted that in computing this period, both the date of issuance and the date of compliance must be excluded. Consequently the jurisdictional notice is rendered void and all subsequent proceedings emanating from it are a ‘nullity and non-est in the eyes of law’.
61. Referring to the decision of Hon’ble Karnataka High Court in the case of PCCIT vs. SmtKomarla Yogendra Keertana reported in (2025) 307 Taxman 106 (Kar), he submitted that the Hon’ble High Court in the said decision has held that where impugned notice issued u/s 148A(b) did not provide the assessee minimum statutory period of seven days to respond, same was rightly quashed.
62. Referring to the decision of Hon’ble Rajasthan High Court in the case of Bijendra Singh vs. PCCIT reported in (2025) 478 ITR 493 (Raj), he submitted that the Hon’ble High Court in the said decision following the decision of Hon’ble Supreme Court in the case of Pioneer Motors (Private) Ltd. vs. Municipal Counsel, Nagrecoil reported in AIR 1967 SC 684 has held that both the terminal dates have to be excluded for the purpose of complying with the requirement of words ‘not less than .. days”.
63. The Ld. DR on the other hand submitted that the Assessing Officer has issued notice u/s 148A(b) on 16.03.2022 asking the assessee to submit its details on or before 23.03.2022. Thus, a period of 7 days have been given. Therefore, the arguments advanced by the Ld. Counsel for the assessee are liable to be rejected and the notice issued is to be held as valid notice.
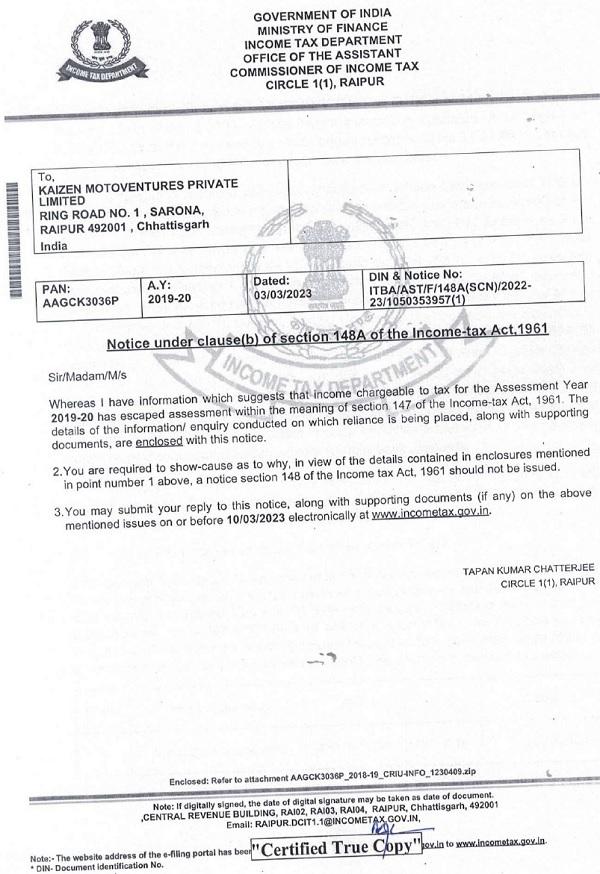
64. We have heard the rival arguments made by both the sides, perused the orders of the Assessing Officer and the Ld. CIT(A) / NFAC and the paper book filed on behalf of the assessee. We have also considered the various decisions cited before us. We find the Assessing Officer issued a notice under clause (b) of section 148A on 16.03.2022 by asking the assessee to submit the details in the portal on or before 23.03.2022, the details of which are as under:
65. Under these circumstances, we have to see as to whether a period of 7 days as mandated by the provisions of section 148A(b) are fulfilled or not. We find an identical issue had come up before Hon’ble Rajasthan High Court in the case of Bijendra Singh vs. PCCIT (supra). The Hon’ble High Court in the said decision while deciding the aspect of calculating the days in a case where the provision requires a notice of ‘not less than particular days’, following the decision of Hon’ble Supreme Court in the case of Pioneer Motors (Private) Ltd. vs. Municipal Council (supra) has observed as under:
“10. Section 148A(b) of the Act requires providing opportunity of being heard to the assessee by serving upon him/her notice to show cause within such time, as may be specified in the notice being ‘not less than seven days’ but not exceeding thirty days from the date, on which such notice is issued.
11. The aspect of calculating the days in a case where the provision requires a notice of ‘not less than particular days’, has been dealt with by the Hon’ble Supreme Court in the Pioneer Motors (Private) Ltd. vs. The Municipal Council, Nagrecoil : AIR 1967 SC 684, wherein it has, inter-alia, been laid down as under:
“The words “not being less than one month” do imply that clear one month’s notice was necessary to be given, that is, both the first day and the last day of the month had to be excluded. To put it in the language used by Maxwell on Interpretation of Statutes, 10th Edition, p. 351 :-
“..when…….. ‘not less than’ so many days are to intervene, both the terminal days are excluded from the computation.”
12. It has been laid down by the Hon’ble Supreme Court that both the terminal days have to be excluded for the purpose of complying with the requirement of words ‘not less than …. days “. Admittedly, in the present case, the notice dated 16.03.2022 was issued/posted on 17.03.2022 and the date fixed for response was 23.03.2022. Excluding two days i.e. the date of sending of the notice as well the last date indicated, even if the notice was received by the petitioner, the same falls short of seven days’ period, as envisaged by provisions of Section 148A(b) of the Act; and as such, for violation of mandatory provisions of Section 148A(b) of the Act, the notice issued to the petitioner cannot be sustained.”
66. We find the Hon’ble Karnataka High Court in the case of PCCIT vs. Smt.Komarla Yogendra Keertana (supra) has held that where impugned notice issued u/s 148A(b) did not provide the assessee minimum statutory period of seven days to respond, the same is liable to be quashed.
67. Similar view has been taken by Hon’ble Gujarat High Court in the case of Atul Mahavirprasad Paldecha vs. ITO reported in (2025) 307 Taxman 331 (Guj). Since in the instant case the Assessing Officer has not given the mandatory period of clear 7 days for replying to the notice issued under clause (b) of section 148A, therefore, such notice being not in accordance with law is liable to be quashed. We, accordingly, hold that the notice issued by the Assessing Officer on 16.03.2022 under clause (b) of section 148A is not in accordance with law and therefore, the same is quashed. Since the assessee succeeds on this legal ground, the appeal filed by the Revenue becomes infructuous and the same is dismissed.
68. In the result, all the 4 appeals filed by the Revenue are dismissed”
4. Similar view has been held by this Bench in the case of Atal Agrawal Vs. ITO-1, Raigarh (C.G.), ITA No.231/RPR/2026, A.Y.2018-19, dated 03.09.2026.
5. Resultantly, following the same party of reasoning and upon examination of the notice u/s.148A(b) of the Act, we hold that the said notice being non-compliant of the said legal position, it is invalid, void ab initio and such invalid, void ab initio notice cannot give rise to a valid assessment order. Hence, the assessment order in pursuant of void ab initio notice is therefore, quashed. That all other subsequent proceedings are non-est as per law. Rest other grounds stands academic only.
6. In the result, appeal of the assessee is allowed.
Order pronounced in the open court on 22nd September, 2026.








