
Sushil Tiwari Vs ITO (ITAT Chandigarh)
Summary: ITAT Chandigarh allowed the assessee’s appeal for AY 2018-19 concerning deductions under sections 54F and 54B following verification of the nature of the properties and the supporting purchase deeds. The assessee had sold ancestral agricultural land for ₹8 crore on 18 September 2017 and computed capital gains of ₹7,72,80,000. The Assessing Officer disallowed ₹2,63,71,500 under section 54F and ₹3,72,56,500 under section 54B, making an aggregate addition of ₹6,36,28,000. The CIT(A) granted partial relief under section 54B but sustained the section 54F disallowance on the premise that the assessee owned more than one residential house.
The assessee contended that SCO No. 7, Dhakoli, Zirakpur, treated as a residential house by the CIT(A), was a commercial shop-cum-office. On the Tribunal’s direction dated 13 August 2026, the Assessing Officer examined the documents and obtained physical verification. The factual report confirmed that the property was commercial. The Tribunal held that it could not be counted as a residential house when applying the ownership restriction under section 54F. It consequently deleted the disallowance of ₹2,63,71,500 and allowed the claim, subject to satisfaction of the remaining statutory conditions, if any.
For section 54B, the assessee relied particularly on agricultural-land purchase deeds dated 2 July 2018 for ₹80 lakh and 1 August 2018 for ₹45 lakh. Verification confirmed the agricultural character of the purchased properties. The Tribunal held that their location in an urban area could not, by itself, justify denial of relief where their agricultural character was established. It allowed deduction to the extent of eligible investment established by the purchase deeds and other material, including these two purchases, and deleted the sustained disallowance to that extent.
The Tribunal condoned the three-day delay in filing the appeal. Interest under sections 234A, 234B and 234C was treated as consequential and directed to be modified according to the final income computation. The challenge to initiation of penalty proceedings under section 270A was premature and required no independent adjudication. The appeal was allowed.
FULL TEXT OF THE ORDER OF ITAT CHANDIGARH
This appeal filed by the assessee is directed against the order passed by the learned Commissioner of Income-tax (Appeals) [hereinafter referred to as “the learned CIT(A)”] and arises out of the assessment order passed by the Assessing Officer under section 143(3) read with section 144B of the Income-tax Act, 1961 (“the Act”) for the Assessment Year 2018-19.
2. At the outset, the ld. AR submitted that the appeal filed by the assessee is barred by limitation by 3 days for which affidavit explaining the delay has been placed on record. It was submitted that the delay was neither intentional nor deliberate and occurred due to unavoidable circumstances. The ld. DR did not seriously object to the condonation of delay. Considering the contents of the affidavit and the totality of facts and circumstances, we are satisfied that the assessee was prevented by sufficient cause from filing the appeal within the prescribed limitation period. Accordingly, the delay of 3 days in filing the appeal is condoned and the appeal is admitted for adjudication on merits.
3. The facts of the case are that the assessee is an individual deriving income under the heads “Income from House Property”, “Business or Profession”, “Capital Gains” and “Other Sources”. During the year under consideration, the assessee sold ancestral agricultural land for a consideration of ₹8,00,00,000 vide sale deed dated 18.09.2017. Against the resultant capital gains, the assessee claimed deduction/exemption under sections 54F and 54B of the Act.
3.1 The assessee computed the capital gain at ₹7,72,80,000 after reducing the indexed cost of acquisition and claimed deduction under section 54F of ₹2,63,71,500 on account of investment in a residential property and deduction under section 54B in respect of investment made in agricultural land. The assessment proceedings were taken up under the Limited Scrutiny scheme on the issue of capital gain deduction claimed by the assessee.
4. During the assessment proceedings, the Assessing Officer required the assessee to furnish details and supporting evidence in respect of the deductions claimed under sections 54F and 54B. The assessment order records that although the assessee furnished certain documents, the Assessing Officer considered that sufficient supporting evidence in respect of the claims had not been furnished. Consequently, the claims under sections 54F and 54B were disallowed and an aggregate addition of ₹6,36,28,000 was made to the returned income. The assessment was accordingly completed determining the assessed income at ₹6,69,79,260, after making disallowance of ₹2,63,71,500 under section 54F and ₹3,72,56,500 under section 54B.
5. Aggrieved by the assessment order, the assessee preferred an appeal before the learned CIT(A). The assessee contended that the relevant documents had been furnished and that the disallowance was made without properly considering the documentary evidence.
6. In the appellate proceedings, the assessee furnished, inter alia, the sale deed of the agricultural land sold, purchase deeds of the agricultural properties acquired for claiming deduction under section 54B, documents relating to the residential property purchased for claiming deduction under section 54F and the relevant bank statement relating to the Capital Gains Accounts Scheme.
7. The learned CIT(A) partly accepted the claim under section 54B. In respect of investment of ₹2,20,00,000, the learned CIT(A) found that the investment in agricultural land had been made within the prescribed time and allowed the claim to that extent. The remaining claim of ₹1,72,56,500 was not accepted for want of supporting documentary evidence.
8. As regards the amount of ₹1,36,52,000 deposited in the Capital Gains Accounts Scheme, the learned CIT(A) accepted the deposit as eligible for exemption for the year under consideration, subject to verification of subsequent utilisation in accordance with section 54B/54EC. With regard to the claim under section 54F, the learned CIT(A) noted that the assessee had shown income from more than one property under the head “Income from House Property”, including the property situated at SCO-7, Dhakoli, Zirakpur. Proceeding on the basis that the assessee owned more than one residential house on the date of transfer of the original asset, the learned CIT(A) held that the assessee failed to satisfy the condition prescribed under the proviso to section 54F and accordingly upheld the disallowance of ₹2,63,71,500.
9. The assessee has challenged the order of the learned CIT(A), inter alia, on the following grounds:
1. That the order of the Assessing Officer is defective both in law and on facts.
2. That the addition/disallowance made under section 54B is unjustified.
3. That the addition/disallowance made under section 54F is unjustified.
4. That the charging of interest under sections 234A, 234B and 234C is not justified.
5. That the initiation of penalty proceedings under section 270A is not justified.
6. The assessee has also raised a general ground seeking permission to raise additional grounds, if any.
10. Since the controversy before us essentially concerns the eligibility of the assessee’s claims under sections 54B and 54F, we proceed to adjudicate these issues. The matter was elaborately argued by both sides, namely, the learned AR for the assessee and the learned DR for the Revenue.
11. On the issue of deduction under section 54B, the learned AR submitted that the assessee had furnished copies of the purchase deeds in respect of three agricultural lands purchased against the agricultural land sold. It was submitted that, despite the relevant documents having been furnished, the benefit of deduction was not allowed in respect of two purchase deeds, namely:
- purchase deed dated 02.07.2018 for ₹80,00,000; and
- purchase deed dated 01.08.2018 for ₹45,00,000.
12. The learned AR submitted that the aforesaid documents established the purchase of agricultural land within the prescribed period and, therefore, the corresponding investment was eligible for deduction under section 54B.
13. As regards section 54F, the learned AR submitted that the learned CIT(A) had denied the benefit on the premise that the assessee owned more than one residential house, principally because SCO No. 7, Dhakoli, Zirakpur had been treated as a residential property. It was submitted that the said property was a Shop-cum-Office and was commercial in nature. The learned AR therefore submitted that the said property could not be treated as a residential house for applying the restriction contained in section 54F. The assessee also relied upon the documentary material furnished in support of both claims. The record shows that before the appellate authority the assessee had specifically furnished purchase deeds and other documents in support of the deductions claimed.
14. Upon considering the rival submissions, this Tribunal, vide order dated 13.08.2026, found that the issues under sections 54B and 54F required verification of the relevant documents and factual position. Accordingly, in the interest of justice, the Tribunal directed the Assessing Officer to examine the relevant documents and submit a comprehensive report on both issues after providing due opportunity to the assessee. The assessee was granted liberty to place before the Assessing Officer copies of the relevant sale/purchase deeds concerning the two agricultural lands in respect of which deduction under section 54B had not been allowed, as well as the sale deed/documents relating to SCO No. 7, Dhakoli, Zirakpur, for determining the nature and status of the said property for purposes of section 54F. The matter was accordingly adjourned to 01.09.2026, with the hearing continuing as Part Heard.
15. The ld. DR had placed on record copy of the Remand Report filed by the AO which is to the following effect:
Govt. of India
Income Tax Department
O/o the Income Tax Officer, Ward-3, Aayakar Bhawan, Sector-2, Panchkula
F.No: ITO/Ward-3/PKL/2026-27/767
Dated: 28.08.2026
To
The Income Tax Officer (Hq.)
O/o The Commissioner of Income Tax (DR),
ITAT, Chandigarh
Sir,
Sub: Remand report in Appeal Number ITA21/Chandi/2025 Titled as Sushil Tiwari, Panchkula Vs. ITO, Ward-3, Panchkula, for the A.Y. 2018-19 and Appeal Number ITA350/Chandi/2025 Titled as Sushil Tiwari, Panchkula Vs. ITO, Ward-3, Panchkula, for A.Y. 2017-18, PAN-AFNPT9971M, – Regarding –
Respected Sir,
The Hon’ble ITAT vide its daily order dated 13.08.2026 in Appeal Number ITA21/Chandi/2025 Titled as Sushil Tiwari, Panchkula Vs. ITO, Ward-3, Panchkula directed the AO to examine the Sale deed in respect of two Agricultural Land for which deduction u/s 54B has not been allowed, as well as nature/status of SCO No.7, Dhakoli, Zirakpur for the purpose of section 54F in F.Y. 2017-18, after providing due opportunity to the assessee.
Further, the Hon’ble ITAT vide its daily order dated 13.08.2026 in Appeal Number ITA350/Chandi/2025 Titled as Sushil Tiwari, Panchkula Vs. ITO, Ward-3, Panchkula directed the AO to ascertain the nature and character of the land as it existed on the date of its sale.
The AO issued letter dated 19.08.2026 to the assessee (which was served on the assessee same day), requesting him to provide the Fard/Girdawari of the Land sold by the assessee in the F.Y. 2016-17 and document indicating the usage of the property SCO No. 7, Dhakoli, Zirakpur. A letter dated 19.08.2026 has also been issued to the Registrar, Tehsil Zirakpur, requesting him to provide the Fard/Girdawari of the Land sold by the assessee in the F.Y. 2016-17 and F.Y. 2017-18. Further, the AO has also deputed Sh. Vijender Kumar, ITI to get the physical verification of the properties in question.
In response to the letter issued to the assessee, the assessee submitted the Fard of the Land sold by him for the F.Y. 2016-17.
Further, the Registrar, Tehsil Zirakpur has not responded to the queries raised by this office.
Sh. Vijender Kumar, ITI has also submitted his report of the physical verification of the properties in question, which is appended as under:
Date: 19/08/2026
Inspector Report in the case of Sh. Sushil Tiwari
As per your direction, I visited the location -SCO No. 07, Dhakoli Zirakpur today, i.e. 19/08/2015 to verify the nature and status of the property. The said property is situated on National Highway i.e. Kalka-Shimla Highway. The property is in the right adjacent to the Mandarin Hotels, SCO- 04-05-06 Dhakoli and the properties situated adjacent to said property are mostly in the business of Hotel and Restaurant. On enquiry, it was gathered that there was a restaurant named Grill Inn at the said SCO-07 from the year 2017 to 2021. Currently, the property was lying vacant and some renovation work was going on the property. From the neighbors of the said property the information was collected that the said property had been used for commercial purpose from last 8-9 years. One more thing pertinent to mention here that the property is situated in a commercial hub of around 20 to 25 properties. All the properties near to this property are presently used for commercial purpose.
Further, I also visited the 4 bigha land sold by the assessee at village Chhat, Sub tehsil Zirapur. There is a residential tower named “Sushma Joynest” as of now. The google map coordinates of the corner toward Chandigarh tricity are 30.617692, 76.796596. Assessee has still some land in his name attached with the property. The 4 bigha of land was very near to the PR-7, Road which is called airport road. Some inquiries has been collected from the old age person situated near the land and it was found that this was agriculture land and land near to this land was also agriculture land.
Thereafter, I visited the two parcels of land situated at Sanoli which is in Municipal area of Zirakpur. At the time of purchase by the assessee in F.Y. 2017-18, it was an agriculture land and was used for agriculture purpose and as of now, this land is used for agriculture purposes.
[Signature]
Vijender Kumar
Inspector
O/o ITO, Ward-3, Panchkula
during the year 2018. The inspector report also indicates that property was used for commercial purpose in year 2018. Other older pictures were also examined from the Google Maps of nearer establishments and it was gathered that the said property was a commercial even before the “Grill Inn” restaurant started. In view of the above, it is evident that the SCO 7, Dhakoli, Zirakpur was a commercial property and not a residential one.
2. Land at Sanoli Village: The purchase deed dated 02.07.2018 and the purchase deed dated 01.08.2018 in respect of the properties purchased by the assessee as provided by the assessee have been examined and it was found that the type of Land was mentioned as Chahi/Khetibadi (in Punjabi in both the purchase deeds. Further, the inspector of this office has also reported that the land is situated in the Municipal Limit of Zirakpur and is being used for agricultural purpose till now. The land qualifies as Urban Agricultural Land.
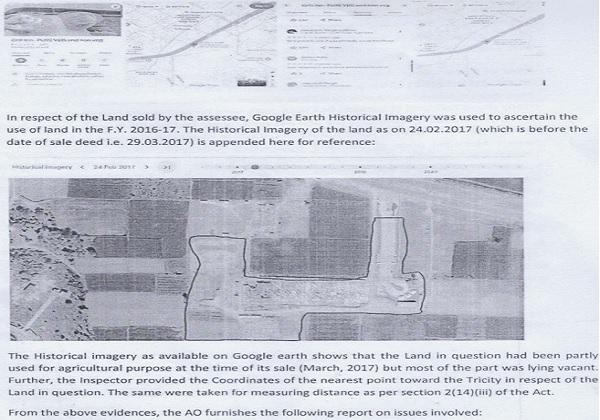
3. Land at Village Chhat, Sub-Tehsil Zirakpur: The Historical imagery as available on google earth clearly shows that Land in question had been partly used for agricultural purpose at the time of its sale (March, 2017) but most of the part was lying vacant. Further, the Inspector provided the Coordinates of the nearest point toward the Tricity in respect of the Land in question. The Nearest Municipal Areas of the Land are Zirakpur (population 95553), Mohali(population 146213) and Chandigarh(population 970602). Ariel distance from all these three municipal boundary has been measured on google map and it was found that the land is well outside the limit prescribed in the section 2(14)(iii) of the Act from the Mohali and Chandigarh Municipal limits. The land in very close to the Aerocity but the Aerocity Mohali was brought into the Jurisdiction of MC Mohali only in year 2025.
The map for municipal limit of Zirakpur has been called from the Sub-registrar, Zirakpur and the same has not been received so far. The information is expected to received by 31.08.2026 as per telephonic conversion with the Assistant Town planner, MC Zirakpur. The Land is within 2KM ariel distance of Maya Garden Zirakpur, but the MC Limit of Zirakpur are yet to be ascertained from the official records of MC Zirakpur. The supplementary report on this issue will be sent once the information collected from the Sub Registrar, Zirakpur.
The remand report is submitted for your kind perusal, and the appeal may kindly be decided on merits.
Yours faithfully,
16. Pursuant to the aforesaid direction, the Assessing Officer, along with the learned CIT-DR, appeared before us and confirmed the factual position concerning the properties. In respect of SCO No. 7, Dhakoli, Zirakpur, it was confirmed that the property was commercial in nature. In respect of the other two properties, it was confirmed that the properties were urban agricultural properties purchased by the assessee. The Revenue, however, submitted that two of the agricultural properties were situated in an urban area and, therefore, the relevant statutory requirements required examination. The learned DR accordingly relied upon the factual report and the orders of the authorities below, while leaving the matter to be decided on the basis of the material and verification carried out pursuant to the Tribunal’s direction.
17. We have carefully considered the rival submissions, the orders of the authorities below, the material available on record and the factual report furnished pursuant to our order dated 13.08.2026. The assessee had invested ₹2,63,71,500 in the purchase of a new residential property and claimed exemption under section 54F. The purchase deed and other supporting material were placed on record. The learned CIT(A), however, denied the claim on the ground that the assessee owned more than one residential house on the date of transfer of the original asset.
The aforesaid finding of the learned CIT(A) was materially based upon the treatment of SCO-7, Dhakoli, Zirakpur, as a residential property. However, pursuant to the specific direction issued by this Tribunal on 13.08.2026, the factual position has been examined and the Assessing Officer has confirmed that the said property is commercial in nature. Once the said property is found to be commercial in nature, it cannot be taken into account as a residential house for the purpose of determining whether the assessee owned more than one residential house on the date of transfer of the original asset. The very factual foundation on which the learned CIT(A) denied the benefit under section 54F, therefore, does not survive.
18. We accordingly hold that the assessee cannot be denied the benefit of section 54F merely by treating SCO-7 as a residential property when the factual verification undertaken pursuant to the direction of this Tribunal establishes that the said property is commercial in nature. Accordingly, the disallowance of ₹2,63,71,500 under section 54F is deleted and the assessee’s claim is allowed, subject to satisfaction of the remaining statutory conditions, if any.
19. The assessee claimed deduction under section 54B on account of investment in agricultural land purchased after the sale of the original agricultural land. The learned CIT(A) had allowed the claim only to the extent of ₹2,20,00,000 and denied the balance claim for want of supporting documentary evidence.
20. Before us, the learned AR specifically relied upon the purchase deeds dated 02.07.2018 for ₹80,00,000 and 01.08.2018 for ₹45,00,000, which, according to the assessee, had not been given due consideration by the lower authorities. Pursuant to our order dated 13.08.2026, the relevant documents and factual position were examined. It has been confirmed before us that the properties in question were agricultural properties and were purchased by the assessee. The Revenue has pointed out that two of the properties are situated in an urban area. However, the report furnished pursuant to the direction of the Bench confirms their agricultural character. Mere location of an agricultural property in an urban area, in the absence of material establishing that the property was not agricultural in character, cannot by itself be a sufficient basis for denying the benefit claimed under section 54B.
21. The documentary evidence regarding the purchase of agricultural land having been examined and the agricultural nature and purchase by the assessee having been confirmed, we find that the assessee has established the factual basis of the claim. Accordingly, the claim under section 54B is allowable to the extent of the eligible investment established by the purchase deeds and other material placed on record, including the investments covered by the purchase deeds dated 02.07.2018 and 01.08.2018. The disallowance sustained by the learned CIT(A) under section 54B is, therefore, deleted to the extent of the eligible investment duly established on record.
22. The grounds relating to levy of interest under sections 234A, 234B and 234C are consequential in nature and shall stand modified in accordance with the final computation of income pursuant to this order.
23. As regards initiation of penalty proceedings under section 270A, the same is premature at this stage and does not require independent adjudication.
24. In view of the foregoing discussion, and particularly having regard to the factual verification undertaken pursuant to the Tribunal’s order dated 13.08.2026, we hold as under:
1. SCO No. 7, Dhakoli, Zirakpur, has been confirmed to be commercial in nature and, therefore, cannot be treated as a residential house for determining the assessee’s eligibility under section 54F.
2. The assessee is, accordingly, entitled to deduction under section 54F in respect of the investment of ₹2,63,71,500, subject to the other statutory conditions being satisfied.
3. The properties relied upon for the purposes of section 54B have been confirmed to be agricultural properties purchased by the assessee.
4. The assessee is entitled to deduction under section 54B to the extent of the eligible investment established by the documentary evidence, including the purchase deeds dated 02.07.2018 for ₹80,00,000 and 01.08.2018 for ₹45,00,000.
5. The consequential ground relating to interest is allowed for statistical purposes, and the issue of penalty is left open in accordance with law.
25. Accordingly, the grounds relating to sections 54B and 54F are allowed and the corresponding disallowances sustained by the learned CIT(A) are deleted to the extent indicated above.
26. In the result, the appeal of the assessee is allowed. Order pronounced on 1s t Sept.,2026.








