
EMC Software and Services India Pvt. Ltd. Vs JCIT (ITAT Bangalore)
Summary: The Income Tax Appellate Tribunal, Bangalore Bench, in EMC Software and Services India Pvt. Ltd. v. Joint Commissioner of Income Tax, IT(TP)A No.3375/Bang/2018, decided on 18 December 2019 for Assessment Year 2014-15, partly allowed the assessee’s appeal for statistical purposes in a dispute relating to transfer pricing adjustments for software development services and information technology-enabled services (ITeS). The assessee challenged the selection and rejection of several comparable companies, the application of functional and financial filters, the treatment of foreign-exchange gains, and working-capital adjustments. The Tribunal directed the exclusion of four comparables in the software development segment and three comparables in the ITeS segment, remitted multiple requests for inclusion to the Transfer Pricing Officer (TPO), and directed reconsideration of certain computational issues. The original decision was subsequently modified through limited recall proceedings, particularly in relation to I2T2 India Limited and tax credits.
EMC Software and Services India Pvt. Ltd. provided software development and related services to its associated enterprises, including the EMC group in the United States. It operated from a special economic zone and was remunerated on a cost-plus basis. For Assessment Year 2014-15, the assessee filed its return on 27 November 2014 declaring total income of ₹1,04,44,44,710 after claiming applicable deductions, including under Section 10AA of the Income-tax Act, 1961. The TPO examined the benchmarking of the assessee’s software development and ITeS activities using the Transactional Net Margin Method (TNMM). The TPO’s analysis led to a combined proposed transfer-pricing adjustment of ₹136,35,28,807, comprising ₹63,83,43,680 for software development services and ₹72,51,85,127 for ITeS. Following directions of the Dispute Resolution Panel dated 12 September 2018, the final assessment order dated 29 October 2018 assessed total income at ₹239,45,82,870.
For the software development services segment, the assessee sought exclusion of Infosys Limited, Larsen & Toubro Infotech Limited, Persistent Systems Limited and Thirdware Solutions Limited. The Tribunal accepted the exclusions because the companies’ functions, ownership of valuable intangibles, software products, intellectual-property activities, scale, and lack of suitable segmental information made them unsuitable comparables for a captive software development service provider. It followed the coordinate Bench’s decisions in LG Soft India Pvt. Ltd. v. DCIT and other authorities, including 3DPLM Software Solutions, CGI Information Systems and PCIT v. Saxo India Pvt. Ltd..
The assessee also sought inclusion of Akshay Software Technologies Limited, Sasken Communication Technologies Limited, Maveric Systems Limited, I2T2 India Limited, Kireeti Soft Technologies Limited, Exilant Technologies and Celstream Technologies Limited. In its original order, the Tribunal remanded most of these companies for verification of financial information, export revenue, related-party transactions, research and development activities and functional comparability. It originally rejected I2T2 India Limited for inclusion. However, this particular finding was reopened in subsequent proceedings. On 1 October 2020, following a limited recall, the Tribunal directed the AO/TPO to include I2T2 India Limited in the comparable set. Accordingly, the original exclusion of I2T2 India Limited is not the final operative position.
In the ITeS segment, the Tribunal directed exclusion of Infosys BPO Limited, E-Clerx Services Limited and Crossdomain Solutions Pvt. Ltd. It held that Infosys BPO had diversified high-end service operations, substantial brand value, intangibles and a business model not comparable with routine captive ITeS services. E-Clerx rendered knowledge process outsourcing services and lacked appropriate segmental information separating the relevant functions. Crossdomain provided specialised payroll processing, technology-enabled business solutions and KPO services that differed materially from routine ITeS operations. The Tribunal relied on Ocwen Financial Solutions Pvt. Ltd., Hyundai Motor India Engineering Pvt. Ltd., Symphony Marketing Solutions India Pvt. Ltd. and PCIT v. BNY Mellon International Operations (India) Pvt. Ltd., among other decisions.
For companies proposed for inclusion in the ITeS segment, the Tribunal directed inclusion of Jindal Intellicom Limited and Informed Technologies Limited, following coordinate Bench decisions addressing their functional profiles and service-revenue characteristics. The question of Accentia Technologies Limited was remitted to the TPO to verify whether related-party transactions exceeded the prescribed 25% filter. The Tribunal also remitted issues relating to treatment of foreign-exchange gains and working-capital adjustment, including the assessee’s contention concerning adjustments relating to non-associated-enterprise transactions.
The original order further treated interest under Sections 234B and 234C as consequential. The assessee’s appeal was partly allowed for statistical purposes. Importantly, the subsequent order dated 1 October 2020 in the same appeal, following M.P. No.33/Bang/2020, also remitted the claims for proper credit of advance tax, self-assessment tax, TDS and MAT credit under Section 115JAA. This subsequent development is relevant when reporting the operative outcome of the litigation. The 2019 order should not be characterised as having finally rejected I2T2 India Limited or as conclusively determining the tax-credit issues.
Cases Discussed
1. LG Soft India Pvt. Ltd. v. DCIT, IT(TP)A No.3122/Bang/2018, order dated 28.05.2019, and M.P. No.95/Bang/2019, order dated 27.09.2019 (ITAT Bangalore) — Followed for exclusion of Infosys, Larsen & Toubro Infotech, Persistent Systems and Thirdware Solutions based on functional differences and intangible assets. The same reasoning is discussed in TaxGuru’s coverage of software comparability disputes.
2. 3DPLM Software Solutions Ltd. v. DCIT, IT(TP)A No.1303/Bang/2012, order dated 28.11.2013 (ITAT Bangalore) — Cited in the quoted LG Soft India decision for exclusion of companies with software-product activities, intangibles and unavailable segmental information.
3. Trilogy E-Business Software India Pvt. Ltd., ITA No.1054/Bang/2011 (ITAT Bangalore) — Cited in the quoted coordinate Bench analysis on functional comparability.
4. CIT v. Agnity India Technologies Pvt. Ltd., Delhi High Court — Cited regarding exclusion of large, functionally diversified technology companies as comparables.
5. CGI Information Systems & Management Consultants Pvt. Ltd. v. ACIT, [2018] 94 taxmann.com 97 (ITAT Bangalore) — Relied upon for functional comparability of software development and ITeS providers.
6. Pitney Bowes Software India Pvt. Ltd. v. ACIT, [2018] 101 taxmann.com 350 (ITAT Delhi) — Cited concerning Larsen & Toubro Infotech Limited.
7. MetricStream Infotech Pvt. Ltd., IT(TP)A Nos.1418 and 2735/Bang/2017 (ITAT Bangalore) — Cited in the quoted LG Soft India rectification order concerning exclusion of L&T Infotech.
8. Electronics for Imaging India Pvt. Ltd., IT(TP)A No.1506/Bang/2016 (ITAT Bangalore) — Cited regarding the same comparable-company exclusion.
9. PCIT v. Saxo India Pvt. Ltd., [2016] 74 taxmann.com 88 (Delhi High Court), as cited in the order — Considered in the analysis of Persistent Systems and other companies with product development and intellectual-property functions.
10. Lime Labs (India) Pvt. Ltd. v. ITO, [2018] 101 taxmann.com 201 (ITAT Delhi) — Cited concerning Thirdware Solutions.
11. Ocwen Financial Solutions Pvt. Ltd. v. JCIT, [2019] 108 taxmann.com 306 (ITAT Bangalore) — Extensively followed regarding Infosys BPO, Jindal Intellicom and Informed Technologies. Related treatment is discussed in TaxGuru-hosted ITAT order on ITeS comparables.
12. Hyundai Motor India Engineering Pvt. Ltd. v. ACIT, [2019] 109 taxmann.com 429 (ITAT) — Followed in excluding E-Clerx Services Limited as a functionally distinct KPO provider.
13. Symphony Marketing Solutions India Pvt. Ltd. v. ITO, [2013] 38 taxmann.com 55 (ITAT Bangalore) — Relied upon regarding Crossdomain Solutions and the absence of segmental information separating specialised payroll and technology services from routine ITeS.
14. PCIT v. BNY Mellon International Operations (India) Pvt. Ltd., [2018] 93 taxmann.com 363 (Bombay High Court) — Relied upon for exclusion of Crossdomain Solutions because of its KPO characteristics.
15. EMC Software and Services India Pvt. Ltd. v. JCIT — Subsequent Order, IT(TP)A No.3375/Bang/2018, order dated 01.10.2020 (ITAT Bangalore) — Subsequent limited-recall decision in the same litigation. Directed inclusion of I2T2 India Limited and verification of advance-tax, self-assessment-tax, TDS and MAT credits. Full subsequent order hosted on TaxGuru.
FULL TEXT OF THE ORDER OF ITAT BANGALORE
The assessee has filed an appeal against the order of final assessment order under Section 143(3) r.w.s. 144C(1) of the Income Tax Act, 1961 dt.29.10.2018 passed in pursuance to the directions of Dispute Resolution Panel (DRP) under Section 144C(5) of the Act Dt.12.09.2018.
2. The assessee has raised the following grounds of appeal :
1. Assessment and reference to Ld. Transfer Pricing Officer are bad in law and on facts
a) The order issued by the Joint Commissioner of Income-Tax, Special Range -2 [‘JCIT’ or ‘Ld. AO’], under section 143(3) read with section 144C, pursuant to the directions issued by the Hon’ble Dispute Resolution Panel [‘DRP’ / Ld. Panel], is bad in law and on facts and is in violation of the principles of natural justice.
Without prejudice to the generality of the above, the order passed by the Ld.AO is bad in law insofar as the fact that the Ld. AO did not issue to the Appellant a show cause notice, as per proviso to section 92C(3) of the Act.
b) The Ld. AO has erred in law in making a reference to the learned Deputy Commissioner of Income Tax [Transfer Pricing (1)(2)(1)] [‘Ld. TPO’]. The Ld. Panel erred in upholding the actions of the Ld. AO/ TPO.
c) The directions issued by the Ld. Panel did not take cognizance of the objections raised by the Appellant while issuing the directions under section 144C(5).
d) The order passed by the Ld. AO is without jurisdiction, inter alia, in so far as it purports to give effect to invalid directions of the Ld. Panel.
e) The directions issued by the Ld. Panel and the order passed by the Ld.AO is without jurisdiction, inter alia, in so far as it purports to give effect to an invalid order of the Ld. TPO.
2. The Ld. Panel and Ld. AO/ Ld. TPO has erred in justifying the motive of shifting profits
On the facts and in the circumstances of the case and in law, the Ld. Panel and Ld.AO / TPO erred in not demonstrating that the motive of the Appellant was to shift profits outside India by manipulating the prices charged in the international transaction, which is a pre-requisite condition to make any adjustment under the provision of Chapter X of the Act. The Ld. Panel erred in upholding the same.
3. Comparability Analysis adopted by the Ld. TPO for determination of arm’s length price for the software development services segment
a) The Ld. AO / Ld. TPO erred in rejecting the value of international transaction of provision of software development services, as recorded in the books of account as the arm’s length price. The Ld. Panel erred in upholding the same.
b) The Ld. AO / Ld. TPO erred in determining a new arm’s length price in substitution of the arm’s length price determined by the Appellant. The Ld. Panel erred in upholding the same.
c) The Ld. Panel and the Ld. AO erred in law in upholding the fresh comparability analysis using non-contemporaneous data conducted by the Ld. TPO and further substituting the Appellant’s analysis with fresh benchmarking analysis on his own conjectures and surmises. Thus, the Appellant prays that the fresh benchmarking analysis conducted by the Ld. TPO is liable to be quashed.
d) The Ld. AO/ Ld. TPO grossly erred on facts in benchmarking the transactions of the software Development services Segment of the Appellant with companies operating as full-fledged entrepreneurs without considering the differences in the functions performed, assets employed and risk undertaken by the Appellant vis-a-vis comparable companies. The Ld. Panel erred in upholding the actions of the Ld. AO/ Ld. TPO.
e) The Ld. AO/ Ld. TPO erred on facts in rejecting the comparable companies arrived at in the Transfer Pricing Study without considering the functional and risk analysis of the Appellant and the Ld. Panel also erred in confirming the same.
f) The Ld. AO/ Ld. TPO erred in law and the Ld. Panel further erred in confirming non-application of multiple-year data while computing the margin of alleged comparable companies as such data had an influence in determining the transfer pricing policy of the Appellant.
g) The Ld. AO/ Ld. TPO erred in law in rejecting the quantitative filters applied by the Appellant in its TP Study such as (i) use of multiple year data (ii) rejecting companies with R&D to Sales of more than 3% (iii) rejecting companies with net fixed assets to sales of less than 200% (iv) rejecting companies with advertisement, marketing and distribution (AMD) expenses to sales less than 3% and Ld. Panel erred in upholding the actions of the Ld. AO / Ld. TPO.
h) The Ld. Panel grossly erred in upholding the rejecting of the positive net worth filter applied by the Appellant, when in fact, the Ld. TPO had accepted the application of the said filter.
i) The Ld. AO / Ld. TPO erred in law in applying arbitrary filters as criterion for rejection of companies identified by the Appellant in the Transfer Pricing Study such as (i) Companies whose data for financial year (‘FY’) 2013-14 was not available (ii) Companies with different financial year ending (i.e., other than 31 March 2014) (iii) Companies with employee cost less than 75% of its total operating revenues (vi) companies who have export services income less than 75% of the sales (v) Companies with employee cost less than 25% of turnover (vi) Companies with persistent loss (Companies reporting loss for any 2 years out of last three years (vii) Companies having related party transactions greater than 25% of the sales. The Ld. Panel also erred in upholding the actions of the Ld. AO/Ld. TPO.
j) The Ld. AO/Ld. TPO erred in considering data obtained u/s 133(6) of the Act. The Ld. Panel erred in confirming the same.
k) The Ld. AO/ Ld. TPO erred in rejecting (1) Akshay Software Technologies Ltd, (2) E-Zest Solutions Limited (3) Sasken Communications Technologies Limited, despite these companies being functionally comparable. The Ld. Panel also erred in confirming the same.
l) The Ld. AO/ Ld. TPO erred in rejecting following companies from its own search which are otherwise functionally comparable and passes all the filters applied in the transfer pricing order (1) Evoke Technologies Limited (2) Maveric Systems Limited (3) Daffodils Software Limited (4) I2T2 India Limited and (5) Kireeti Soft Technologies Limited. The Ld. Panel also erred in confirming the same.
m) The Ld. AO/ Ld. TPO erred in rejecting (1) Exilant Technologies Pvt. Limited (2) Celstream Technologies Limited on the ground that financial data were not available in public domain. The Ld. Panel also erred in confirming the same, and erred in failing to appreciate that the companies are otherwise functionally comparable to the Appellant and pass all filters applied by the Ld. TPO.
n) The Ld. AO/ Ld. TPO erred in including (1) Infosys Limited, (2) Larsen & Toubro Infotech Limited, (3) Mindtree Limited, (4) Persistent Systems limited (5) Thirdware Solutions Limited as comparable despite these companies being functionally dissimilar to the Appellant. The Ld. Panel also erred in confirming the same.
o) The Ld. AO/ Ld. TPO, while applying the turnover filter at the lower limit so as to reject companies having turnovers less than INR 1 crore in FY 2013-14, erred in not applying the said filter at the upper end so as to reject high turnover companies as well. The Ld. Panel also erred in confirming the same.
p) The Ld. AO/ Ld. TPO erred on facts in arbitrarily accepting companies without considering the turnover and size of the Appellant and comparables. The Ld. Panel also erred in confirming the same.
q) The Ld. AO /Ld. TPO erred in not applying the turnover range at the lower and upper limit so as to reject high/low turnover companies.
r) The Ld. AO /kl. TPO erred in not applying the abnormal profit earning filter to reject companies which had earned abnormal profits, indicating the existence of peculiar economic circumstance having an impact on the margin of the companies. The Ld. Panel erred in upholding the same.
4. Comparability Analysis adopted by the Ld. TPO for determination of arm’s length price for the Information Technology Enabled (‘ITe’) services segment
a) The Ld. AO/ Ld. TPO erred in rejecting the value of international transaction of provision of Information Technology Enabled services, as recorded in the books of account, as the arm’s length price. The Ld. Panel erred in upholding the same.
b) The Ld. AO/ Ld. TPO erred in determining a new arm’s length price in substitution of the arm’s length price determined by the Appellant. The Ld. Panel erred in upholding the same.
c) The Ld. AO/TPO, contrary to the provisions of the Act and rules made thereunder, erred in computing the arm’s length price of the ITe service segment by adopting the operating cost and operating income of both the international transaction and the domestic transaction. The Ld. Panel erred in upholding the same.
d) The Ld. AO/TPO, while adopting the operating revenue earned by the ITe service segment of the Appellant, grossly erred in not taking into consideration the foreign exchange gain arising from provision of the said services. The Ld. Panel erred in upholding the same.
e) The Ld. Panel and the Ld. AO erred in law in upholding the fresh comparability analysis using non-contemporaneous data conducted by the Ld. TPO and further substituting the Appellant’s analysis with fresh benchmarking analysis on his own conjectures and surmises. Thus, the Appellant prays that the fresh benchmarking analysis conducted by the Ld. TPO is liable to be quashed.
f) The Ld. AO/ Ld. TPO grossly erred on facts in benchmarking the transactions of the ITe Services Segment of the Appellant with companies operating as full-fledged entrepreneurs without considering the differences in the functions performed, assets employed and risk undertaken by the Appellants vis-à-vis comparable companies. The Ld. panel erred in upholding the actions of the Ld.AO/ Ld. TPO.
g) The Ld. AO/ Ld. TPO erred on facts in rejecting the comparable companies arrived at in the Transfer pricing Study without considering the functional and risk analysis of the Appellant and the Ld. panel also erred in confirming the same.
h) The Ld. AO/ Ld. TPO erred in law and the Ld. panel further erred in confirming non-application of multiple-year data while computing the margin of alleged comparable companies as such data had an influence in determining the transfer pricing policy of the Appellant.
i) The Ld. AO/ Ld. TPO erred in law in rejecting the quantitative filters applied by the Appellant in its TP Study such as (i) use of multiple year data (ii) rejecting companies with R&D to Sales of more than 3% (iii) rejecting companies with net fixed assets to sales of less than 200% (iv) rejecting companies with advertisement, marketing and distribution (AMD) expenses to sales less than 3% and the Ld. Panel erred in upholding the actions of the Ld. AO/ Ld. TPO.
j) The Ld. AO / ld. TPO erred in law in applying arbitrary filters as criterion for rejection of companies identified by the Appellant in the Transfer pricing Study such as (i) Companies whose data for financial year (‘FY’) 2013-14 was not available (ii) Companies with different financial year ending (i.e., other than 31 March 2014) (iii) Companies whose ITeS income is less than 75% of its total operating revenues (iv) Companies who have export service income less than 75% of the sales (v) Companies with employee cost less than 25% of turnover (vi) Companies with persistent loss (Companies reporting loss for any 2 years out of last three years (vii) Companies having related party transactions greater than 25% of the sales. The Ld. panel also erred in upholding the actions of the Ld. AO/ Ld. TPO.
k) The Ld. AO/ Ld. TPO erred in considering data obtained u/s 133(6) of the Act. The Ld. Panel erred in confirming the same.
l) The Ld. AO/ Ld. TPO erred in rejecting Jindal Intellicom limited despite being functionally comparable. The Ld. panel also erred in confirming the same.
m) The Ld. AO/ Ld. TPO erred in rejecting Tech Mahindra Business Services Limited, from its own search which is otherwise functionally comparable and passes all the filters applied in the transfer pricing order. The Ld. Panel also erred in confirming the same.
n) The Ld. AO/ Ld. TPO erred in rejecting Ace BPO Services Pvt. Ltd on the ground that RPT information was not available in public domain. The Ld. Panel also erred in confirming the same, and erred in failing to appreciate that the company is otherwise functionally comparable to the Appellant.
o) The Ld. AO/ Ld. TPO erred in rejecting Informed Technologies Limited on the ground that the company fails service revenue income to Sales filter of 75%. The Ld. Panel also erred in confirming the same and erred in failing to appreciate that the company is otherwise functionally comparable to the Appellant.
p) The Ld. Panel erroneously erred in rejecting Accentia Technologies Ltd on the ground that the RPT of the Company exceeds 25%, and failed to appreciate the company is otherwise functionally comparable to the Appellant.
q) The Ld. AO/ Ld. TPO erred in including (1) Infosys BPO Limited, (2) Microland Limited, (3) Eclerx Services Limited, (4) Crossdomain Solutions Private Limited, as comparable despite these companies being functionally dissimilar to the Appellant. The Ld. Panel also erred in confirming the same.
r) The Ld. AO/ Ld. TPO, while applying the turnover filter at the lower limit so as to reject companies having turnovers less than INR 1 Crore in FY 2013-14, erred in not applying the said filter at the upper end so as to reject high turnover companies as well. The Ld. Panel also erred in confirming the same.
s) The Ld. AO/ Ld. TPO erred on facts in arbitrarily accepting companies without considering the turnover and size of the Appellant and comparables. The Ld.Panel also erred in confirming the same.
t) The Ld. AO /Ld. TPO erred in not applying the turnover range at the lower and upper limit so as to reject high turnover companies.
5. Erroneous data used by the Ld. AO / Ld. TPO
a) The Ld. AO/ Ld. TPO erred in law in using data, which was not contemporaneous and which was not available in the public domain at the time of conducting the transfer pricing study by the Appellant. The Ld. Panel erred in upholding the same.
b) The Ld. AO/ Ld. TPO erred in law and on facts in disregarding the application of multiple-year data while computing the margins of comparable companies. The Ld. Panel erred in upholding the same.
6. Non-allowance of appropriate adjustments to the comparable companies, by the Ld. TPO
The Ld. AO/ Ld. TPO erred in law and on facts in not allowing appropriate adjustments under Rule 10B of the Rules to account for, inter alia, differences in (a) accounting practices, (b) Working capital adjustment (c) Risk profile between the Appellant and the comparable companies. The Ld. Panel erred in confirming the same.
7. Variation of 3% from the arithmetic mean
The Ld. AO/Ld. TPO erred in law in not granting the benefits of proviso to section 92C(2) of the Income Tax Act, 1961 (‘Act’) available to the Appellant. The Ld. Panel erred in upholding the actions of the Ld. AO/ Ld. TPO.
8. The Ld. AO/Ld. TPO erred in law in erroneously not granting complete credit for advance tax and self-assessment tax paid by the Appellant, as claimed in the return of income.
9. The Ld. AO/Ld. TPO erred in law in erroneously not granting credit for Minimum Alternate Tax (MAT), as claimed in the return of income under section 115JAA of the Act.
10. The Ld. AO/Ld. TPO erred in law in not granting consequential relief in the computation of interest under section 234B and 234C of the Act.
The Appellant craves leave to add to or alter, by deletion, substitution or otherowse, the above grounds of appeal, at any time before or during the hearing of the appeal.
Relief
a) The Appellant prays that the appeal be allowed.
b) The Appellant prays that directions be given to grant all such relief arising from the above grounds and also all relief consequential thereto.
The Appellant further prays that the adjustment in relation to Transfer Pricing matters made by the Ld. AO/Ld. TPO and upheld by the Hon’ble DRP be deleted.
3. The assessee is engaged in the business of software development and related services to its Associated Enterprises (AEs), SSIPL, wholly subsidiary of EMC Corporation, USA and the assessee was registered under SEZ on 14th August, 2008 for rendering IT and ITES to EMC Group of Companies and is compensated on mark up on cost basis for services provided and know how, copy rights etc. and other commercial and marketing services owned by EMC. The assessee has filed the Return of Income for Assessment Year 2014-15 on 27.11.2014 with total income of Rs.1,04,44,44,710 after claiming deduction under Chapter VIA and deduction under Section10AA of the Act. The case was selected for scrutiny. Subsequently, Notice under Section 143(2) along with enclosure has been issued. In compliance, the learned Authorised Representative of the assessee appeared from time to time and the case was discussed. The Assessing Officer on perusal of the financial statements found that the assessee has international transactions and with prior approval of Prin. CIT, a reference has been made to Transfer Pricing Officer to determine the Arm’s Length Price. The assessee has international transactions with its AE as per TP document in the F.Y. 2013-14 referred at para 2.2 of the TPO order and also financial profile of the assessee on software product development and ITES referred at para 2.3 which is read as under :
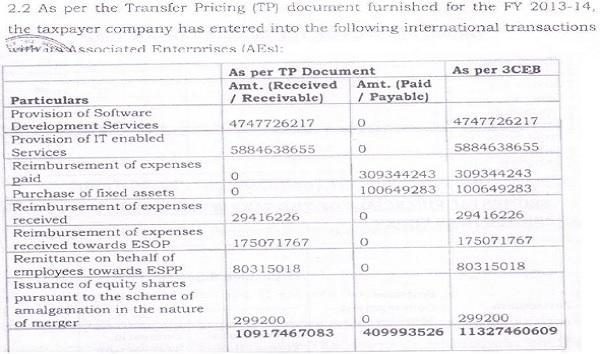
–
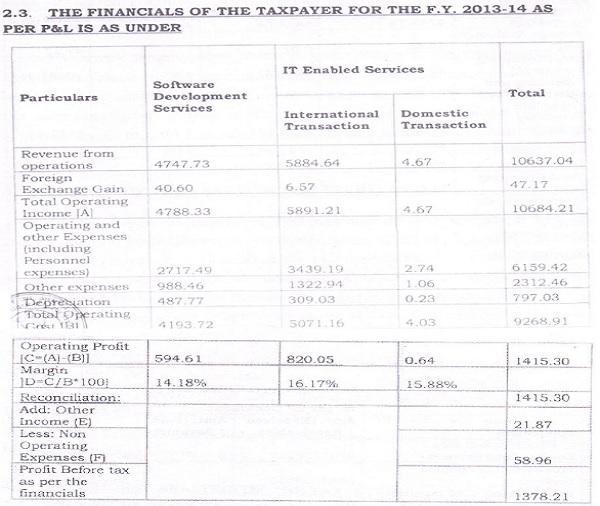
4. The assessee has international transactions in respect of Software Development Services and ITES whereas in TP Study the assessee has selected 7 comparables in respect of Software Development Services segment and 11 comparables in ITES. The assessee in Software Development Services to its AEs adopted TNMM method and the PLI on OP/TC (Total Cost) is 14.18%. The TPO has rejected TP Study and called for the documents in respect of comparables selected for determination of arm’s length in accordance with Section 92C(1) and 92C(2) of the Act. The TPO made comparison and examination of the comparables selected by assessee and found that the assessee has adopted 7 comparables on Software Development Services segment and Profit Level Indicator (PLI) i.e. OP/TC being 14.18%. Whereas the TPO has dealt on the filters in the TP Study and calculated the average Arithmetic Mean (AM) of comparables which has worked out to average OP/TC at 11.91%. After verification and examination of TP Document, the TPO found pertinent defects in the TP Study and finally the TPO has rejected the comparables selected by the assessee in TP Study and applied filters with criteria of current year data where the companies whose data for the F.Y. 2013-14 is excluded, the companies having different financial year ending falls within 12 months period for 1.4.2013 to 31.3.2014 were rejected. The companies whose income was less than Rs.1 Crore were excluded and the companies were Software Development Services / ITES income is less than 75% were rejected. The companies who have more than 25% Related Party Transactions (RPT) of sales were excluded. The companies who have export sales for service less than 75% of sales are excluded and companies with Employees Cost less than 25% of turnover were excluded. The TPO applied the filters on the comparables selected by the assessee at pages 12 & 13 of the order in Software Development Services segment and were rejected. Similarly, the TPO has dealt on 11 comparables of selected by the assessee in ITES segment. Further the TPO rejected the comparables on applicationof filters and has selected final set of comparables at page 61 para 18 of order on Software Development Services segment which are as under :
18. FINAL SET OF COMPARABLES CONSIDERED BY THE TPO FOR SWD SEGMENT
18.1 After considering the objections of the taxpayer to the comparable proposed in the show-cause notice, perusal of relevant annual reports and examination of additional comparable suggested by the taxpayer on the touchstones of filters and functionality, the final set of comparable companies considered by the TPO in respect of Software Development Services Segment, is as under:
| S. No. | Name of Taxpayer | OR/Sales (₹ lakh) | OC (₹ lakh) | OP (₹ lakh) | OP/OC (%) |
|---|---|---|---|---|---|
| 1 | Infosys Ltd. | 46,91,700 | 32,77,700 | 11,84,200 | 36.13% |
| 2 | Larsen & Toubro Infotech Ltd. | 4,54,360 | 3,64,619 | 89,741 | 24.61% |
| 3 | Mindtree Ltd. | 2,99,010 | 2,48,290 | 50,720 | 20.43% |
| 4 | Persistent Systems Ltd. | 1,18,412 | 87,649 | 30,762 | 35.10% |
| 5 | R S Software (India) Ltd. | 35,188 | 28,321 | 6,867 | 24.25% |
| 6 | Cigniti Technologies Ltd. | 5,563 | 4,359 | 1,204 | 27.62% |
| 7 | S Q S India B F S I Ltd. | 20,061 | 16,394 | 3,667 | 22.37% |
| 8 | Thirdware Solutions Ltd. | 19,883 | 13,742 | 6,140 | 44.68% |
| Average | 29.40% | ||||
Further, the TPO calculated the ALP in respect of Software Development Services segment at page 62 para 19.4 which are as under :
19.4 Computation of Arm’s Length Price:
19.4.1 The arithmetic mean of the Profit Level indicators is taken as the arm’s length margin. Please see Annexure A for details of computation of PLI of the comparables. Based on this, the arm’s length price of the services rendered by the taxpayer to its AE(s) in Software Development Services Segment (SWD) is computed as under:
| Arm’s Length Mean Margin on cost | 29.40% |
| Operating Cost | 4,19,37,20,000 |
| Arm’s Length Price (ALP) at 129.40% of Operating Cost | 5,42,66,73,680 |
| Price Received | 4,78,83,30,000 |
| Variation in Price | 63,83,43,680 |
| 3% of price received | 14,36,49,900 |
| Shortfall being adjustment | 63,83,43,680 |
The above shortfall of Rs. 63,83,43,680/- is proposed as transfer pricing adjustment u/s 92CA in respect of software development segment of the taxpayer’s international transactions.
The TPO has calculated the ALP of ITES at page 64 para 21.4 and summary of TP adjustment of Software Development segment and ITES segment at para 21.4 as under :
21.4 Computation of Arm’s Length Price:
21.4.1 The arithmetic mean of the Profit Level indicators is taken as the arm’s length margin. Please see Annexure B for details of computation of PLI of the comparables. Based on this, the arm’s length price of the services rendered by the taxpayer to its AE(s) in IT Enabled Services Segment (ITES) is computed as under:
IT Enabled Services Segment
| Arm’s Length Mean Margin on cost | 30.33% |
| Operating Cost | 5,07,51,90,000 |
| Arm’s Length Price (ALP) at 130.33% of Operating Cost | 6,61,44,95,127 |
| Price Received | 5,88,93,10,000 |
| Variation in Price | 72,51,85,127 |
| 3% of price received | 17,66,79,300 |
| Shortfall being adjustment | 72,51,85,127 |
The above shortfall of Rs. 72,51,85,127/- is proposed as transfer pricing adjustment u/s 92CA in respect of IT Enabled Services segment of the taxpayer’s international transactions.
The TPO passed the order under Section 92CA of the Act with adjustment in Software Development Services segment and ITES segment of Rs.136,35,28,807 vide order dt.21.07.2017. Subsequently the draft assessment order was passed under Section 143(3) r.w.s. 144C(1) Dt.27.12.2017. Aggrieved by draft assessment order, the assessee has filed objections in Form 35A before the DRP whereas the DRP considering the submissions and findings of the TPO has passed order under Section 144C(5) dt.12.09.2018. Finally, in pursuance to the directions of DRP, the TPO has passed the assessment order under Section 143(3) r.w.s. 144C(1) of the Act dt.29.10.2018 assessing the total income of Rs.239,45,82,870. Aggrieved by the final assessment order, the assessee has filed an appeal with the Tribunal.
5. At the time of hearing, the ld. AR submitted that the assessee has two segments (i) Software Development Services (SDS) and (ii) ITES and the turnover of SDS segment is Rs.474 Crores and ITES is Rs.588 Crores. The learned Authorised Representative reiterated his submissions made before the TP authorities and DRP and submitted that under the Software Development Services segment 4 comparables are to be excluded as they are functionally dissimilar and similarly inclusion of 7 comparables in the Software Development Services segment. Whereas in the case of ITES, the ld. AR prayed for exclusion of 3 comparables and inclusion of 3 comparables and filed synopsis and chart in support of his arguments. The assessee has only argued and made submissions on related grounds of appeal only. Contra, the ld. DR supported the orders of TPO and DRP and filed written submissions.
6. We heard the rival contentions and perused the material on record. The learned Authorised Representative submitted that the assessee has two segments (i) Software Development Services segment and (ii) ITES segment. We shall deal with the exclusion of comparables as submitted in the course of hearing by the learned Authorised Representative in Software Development Services segment.
(i) Infosys Limited : This company is functionally dissimilar and provides end to end business solutions like business consulting technology engineering and outsourcing services and no segmental details in respect of services are available and made investments and products to establish as a tradable IPO owner. Further the comparable owns significant brand value products and focus on brand building and incurred expenditure on R & D. The company owns 7 edge products / platforms and six other product based solutions. The company leverages on its premium banking solution and during the year the company merged with its wholly owned subsidiary Infosys Consulting India Limited. We found that the company was excluded from the final list of comparables in assessee’s own case for the Assessment Year 2011-12 by the DRP and revenue has accepted. The learned Authorised Representative supported his arguments relying on the decisions in the case of CIT Vs. Agnity (India) Technologies Pvt. Ltd. (2013); CGI Systems and Management Ltd. Vs. ACIT (2015) 94 taxman.com The learned Authorised Representative also substantiated that for the Assessment Year 2014-15, the co-ordinate Bench of the Tribunal in the case of LG Soft India Pvt. Ltd. Vs. DCIT in IT(TP)A No.3122/Bang/2018 for the Assessment Year 2014-15 Dt.28.5.2019. We support our views relying on the LG Soft India Pvt. Ltd. Vs. DCIT (supra) where the Tribunal has observed at paras 6 and 6.1 as under :
“6. We notice that the co-ordinate bench has excluded M/s.Infosys Ltd in A.Y 2008-09 by following the decision rendered by another co-ordinate bench in the case of 3DPLM Software Solutions Ltd (IT(TP)A No.1303/Bang/2012 dated 28.11.2013, wherein the decision rendered in the case of Triology E Business Software India P Ltd. (ITA No.1054/Bang/2011) was followed and it was held that M/s. Infosys Technologies Ltd is not functionally comparable since it owns significant intangible and has huge revenues from software products. It was further observed that the break up of revenue from software services and software product is not available.
6.1 It was stated that there is no change in facts. Accordingly, following the decision rendered in the assessee’s own case in A.Y 2008-09, we direct exclusion of M/s. Infosys Ltd.”
We found that the Infosys Ltd. has significant intangibles and huge revenues from software products and was considered by the co-ordinate Bench of the Tribunal for exclusion in the Assessment Year 2014-15. Accordingly, we direct the TPO to exclude the Infosys Ltd. from the final list of comparables for determination of ALP.
(ii) L & T Infotech Limited : The company has a margin of 24.61% and has high brand value and is a market leader, high presence and the intangible income in proprietary products. Significant expenditure in foreign currency to the extent of 57.13%. During the year the product engineering business service of the company was transferred to its subsidiary. The company segments are divided into service cluster, industrial cluster and telecom business. As per the Annual Report of the company, the company has a significant capital work-in-progress and the company has developmental products. The comparable was excluded from the final list of comparable in assessee’s own case for the Assessment Year 2011-12 by the DRP and further the comparable company was excluded by the co-ordinate Bench of Delhi Tribunal in the case of Pitney Bowes Software India Pvt. Ltd. Vs. ACIT 101 Taxman.com 350. The learned Authorised Representative also relied on CGI Information Systems & Management Consultants (P) Ltd. Vs. ACIT (2018) 94 taxman.com 97 and DCIT Vs. Taxman India Pvt. Ltd. (2016) 74 Taxmann.com 88 (Del). We found that the co-ordinate Bench of Tribunal in M.P. No.95/Bang/2019 in IT(TP)A No.3122/Bang/2018 for the Assessment Year 2014-15 has dealt on the issue at page 2 para 4 as under :
“4. We heard Ld D.R and perused the record. We find merit in the miscellaneous petition filed by the assessee. Accordingly following paragraph is inserted after paragraph 10 in the impugned order of the Tribunal, which will adjudicate the issue relating to “L & T Infotech Ltd”:-
“10A The assessee has sought exclusion of M/s L & T Infotech Ltd on the ground that there were extraordinary events during the year, it possesses brand and intangibles, it has not provided segmental information and it has got sub-contracting expenses. The Ld A.R submitted that the above said company has been excluded by the co-ordinate bench in the case of Metric Stream Infotech P Ltd (IT(TP)A No.1418 & 2735/Bang/2017) relating to AY 2013-14 and also in the case of Electronics for Imaging India P Ltd (IT(TP)A No.1506/Bang/2016 relating to AY 2011-12). The Ld A.R submitted that there is no change in facts in this year also and accordingly prayed for exclusion of the above said company.
10A.1 We heard Ld D.R and perused the record. We notice that M/s L & T Infotech Ltd has been excluded by the co-ordinate bench in the case of Metric Stream Infotech P Ltd (supra) for AY 2013-14 and also in the case of Electronics for Imaging India P Ltd (supra) for AY 2011-12. The Ld A.R submits that there is no change in facts prevailing in the current year vis-a-vis the years considered by the co-ordinate benches in the above said cases. Accordingly, following the above said decisions, we direct exclusion of M/s L & T Infotech Ltd.”
We considering the functional dissimilarity and judicial decisions and various facts which are not similar to the assessee’s functional profile, accordingly direct the TPO to exclude M/s. L & T Infotech Limited from the final list of comparable in determining the ALP.
(iii) Persistent Systems Ltd. : The company is functionally different as it is engaged in rendering IT services and in the development of software products without there being support segmental information and engaged in IP led solutions and undertakes significant R & D activities, owns IP. During the year the company made acquisitions. The company has made significant investment in IP and their solutions and has a dedicated team for Research and IP development. The learned Authorised Representative relied on decision of Tribunal in the case of CGI Information & Management Systems Pvt. Ltd. Vs. ACIT 94 Taxman.com 97 and PCIT Vs. Saxo India Pvt. Ltd. 74 taxmann.com 88 (Delhi). We relied on the decision of CGI Information Systems & Management Consultants Pvt. Ltd. (supra) at paras 28 to 30 as under :
28. The learned counsel for the Assessee submitted before us that the comparability of the 3 companies out of the aforesaid 4 companies which the Assessee seeks to exclude from the list of comparable companies chosen by the TPO viz., Infosys Ltd., Larsen & Toubro Infotech Ltd. and Persistent Systems Ltd., were considered by the ITAT Delhi Bench in the case of Agilis Information Technologies India (P.) Ltd. v. Asstt. CIT [2018] 89 taxmann.com 440 (Delhi – Trib.) for the same AY 2012-13. In this regard it was submitted that the functional profile of the Assessee is same as that of the Assessee in the case of Agilis Information Technologies India (P.) Ltd. (supra), is identical inasmuch as the said company was also involved in providing SWD services to its AE and the TPO had chosen 16 comparable companies out of which 6 companies chosen by the TPO in the case of the Assessee for the purpose of comparability were the same. His submission was that the decision rendered by the Tribunal in the case of Agilis Information Technologies India (P.) Ltd. (supra) would be equally applicable to the Assessee in the present case also. The learned DR. submitted that the DRP in its directions has merely accepted with the reasoning of the IPO and therefore the issue of exclusion of these companies should be directed to be examined afresh by the DRP.
29. We have considered the rival submissions. In the case of Agilis Information Technologies India (P.) Ltd. (supra), this Tribunal considered the comparability of the 3 companies which the Assessee seeks to exclude from the final list of comparable companies chosen by the TPO. The functional profile of the Assessee and that of the Assessee in the case of Agilis Information Technologies India (P.) Ltd. (supra), is identical inasmuch as the said company was also involved in providing SWD services to its AE and the TPO had chosen some comparable companies which were also chosen by the TPO in the case of the Assessee for the purpose of comparability. In the aforesaid decision the Tribunal held on the comparability of the 3 companies which the Assessee seeks to exclude as follows:
(a) Infosys Ltd., was excluded from the list of comparable companies by following the decision of the Hon’ble Delhi High Court in the case of CIT v. Agnity India Technologies (P.) Ltd. [2013] 36 taxmann.com 289/219 Taxman 26 (Delhi). The discussion is contained in paragraphs 4.5 to 4.7 of the Tribunal’s order. The Tribunal accepted that Infosys Ltd. is a giant risk taking company and engaged in development and sale of software products and also owns intangible assets and therefore not comparable with a software development service provider such as the Assessee in that case.
(b) Larsen & Toubro Infotech Ltd., was excluded from the list of comparable companies by relying on the decision of the Delhi Bench of ITAT in the case of Saxo India (P.) Ltd. v. Asstt. CIT [2016] 67 taxmann.com 155 (Delhi – Trib.). The discussion is contained in paragraphs 4.8 to 4.10 of the Tribunal’s order. The Tribunal held that L & T Infotech Ltd., was a software product company and segmental information on SWD services was not available. The Tribunal also noticed that the appeal filed by the revenue against the tribunal’s order was dismissed by the Hon’ble Delhi High Court in ITA No.682/2016.
(c) Persistent Systems Ltd., was excluded from the list of comparable companies on the ground that this company was a software product company and segmental information on SWD services was not available. The Tribunal in coming to the above conclusion referred to the decision rendered by ITAT Delhi Bench in the case of Cash Edge India (P.) Ltd. v. ITO ITA No.64/Del/2015 order dated 23.9.2015 and the decision of Hon’ble Delhi High Court in the case of Saxo India Pvt. Ltd. (supra). The findings in this regard are contained in Paragraphs 4.14 to 4.16 of its order.
30. Respectfully following the decision of the Tribunal we hold that the aforesaid 3 companies be excluded from the final list of comparable companies for the purpose of arriving at the arithmetic mean of comparable companies for the purpose of comparison with the profit margins. In this regard we are also of the view that the plea of the learned DR for a remand of the issue to the DRP on the ground that the DRP has not given any reasons in its directions cannot be accepted. The DRP has endorsed the view of the TPO in its directions and therefore the reasons given by the TPO should be regarded as the conclusions of the DRP.
We rely on judicial decisions and facts in respect of comparable Persistent Systems Ltd. and direct the Assessing Officer to exclude from the final list of comparable for determination of ALP.
(iv) Thirdware Solutions Ltd. the company is functionally dissimilar and is engaged in rendering software development implementation and support services and engaged in the development of software products and earns revenue from sale of user licenses and purchase stock in trade during the year and has intangibles. Further the margins of the company fluctuate year on year basis due to different revenue recognition model which the company has adopted. The above comparable was excluded in assessee’s own case on functional dissimilarity in the Assessment Years 2005-06 and 2007-08 and learned Authorised Representative also relied on Lime Labs (India) Pvt. Ltd. Vs. ITO 101 Taxman.com 201 (Delhi Trib.). We found the co-ordinate Bench of the Tribunal in the case of LG Software India Pvt. Ltd. Vs. DCIT in IT(TP)A No.3122/Bang/2018 dt.28.05.2019 for the Assessment Year 2014-15 has excluded the comparable as observed at paras 8 & 8.1 at page 4 as under :
“8. We also notice that in A.Y 2008-09, the co-ordinate bench has excluded M/s. Thirdware Solutions Ltd also by following the decision rendered in the case of 3DPLM Software Solutions Ltd (supra), where in it was held that M/s. Thirdware Solutions Ltd. is engaged in product development and earns revenue from sale of licenses and subscription. Further, the segmental details were not available.
8.1 It was stated that there is no change in facts. Accordingly, following the decision rendered in the assessee’s own case in A.Y 2008-09, we direct exclusion of M/s. Thirdware Solutions Ltd.”
The comparable Thirdware Solutions Ltd. has to be excluded as it is predominant in activity and segmental details are not available. Accordingly we direct the TPO/A.O to exclude this comparable from the list of comparables for determining the ALP.
7. Now, we shall take up the comparables in the Software Development Services segment to be included. The learned Authorised Representative submitted that 7 comparables are to be included and made submissions.
(i) Akshay Software Ltd. which has a margin of 8.13%. The income from commission on sale of software license constitute meager 0.5% of total revenue and TPO has not applied transfer development filter. The said company was rejected by the TPO for the reason that the company is engaged in providing provisional services, procurement installation, employment support of ERP products. The DRP has rejected the comparable without applying the filter and there is no difference in the business model adopted by the company and the assessee. We on perusal of the Annual Report at Page 1373 of Paper Book, found that major revenues are from operations as per Note 19 being income from software services and commission received on sale of software licenses. The earnings as per Note 28 as per the financial statements, the company has earning from export of software and in the F.Y. 2013-14 which constitute more than 95% of income. Therefore we found these facts are not considered by the TPO or DRP and accordingly we restore this issue to the file of TPO for examination and verification.
(ii) Sasken Communication Technologies Ltd. : The company has a margin of 10.25% and was rejected by the TPO on the functional dissimilarity and was confirmed by the DRP observing that the company fails export turnover filter. The company earns revenue from licensing and software development and royalty and the company offers software products. The learned Authorised Representative submissions are that the company is functionally similar to the assessee’s profile and services rendered are predominantly software development services and income from software products constitute a meager amount of total revenue shall not have any impact on the profitability of the company’s software development segment. The learned Authorised Representative referred to the profit and loss account at page 1455 where the abridged statement profit and loss account was disclosed and as on 31.3.2014, the revenue from the operations of software products is Rs.309.17 lakhs and software services are Rs.3508.49 lakhs. The learned Authorised Representative emphasizing that there is no impact on the profits. We are of the opinion that the assessee company has customers in US and Europe area and the export revenue filter test has to be applied by the TPO. Accordingly we restore this issue to the file of TPO for fresh consideration.
(iii) Maveric Systems Limited : This comparable was rejected by the TPO and it was sought for inclusion by the assessee and whereas TPO has rejected without any basis and was excluded on the ground that the company was engaged in R & D activity and expenditure is 6% of total turnover. Similarly, the DRP has upheld the exclusion of the company. The learned Authorised Representative submitted that company’s functional profile is comparable and applied the TPO filters. Whereas the DRP has observed that the company has incurred substantial expenses to the tune of 6% of turnover towards R & D and the tolerable limit is 3%. We found the observations of the DRP are without any basis. Accordingly we restore this issue to the file of TPO to give a logical conclusion and findings.
(iv) I2T2 India Limited : This comparable was sought to be included by the assessee but was rejected by the TPO and RPT data are not available in the Annual Report. The DRP has observed that the company does not specify the filters adopted by the TPO and on perusal of the Annual Report, the company is in ITES industry services and is not comparable to the assessee. On perusal of the Annual Report, Paper Book page 1581 at para 2.13, the income from export of software services is higher therefore we are of the opinion that the observations of the TPO and the DRP are to be accepted and hence this comparable is rejected for inclusion.
(v) Keerthi Soft Technologies Ltd., where the margin of the company is 4.11%. The observations of the DRP that the TPO has rejected the company on the ground of functional dissimilarity. On perusal of Paper Book at page 1641 where statement of profit and loss account was disclosed, the revenue from sale of products is disclosed as NIL and at page 1635, there is no segmental reporting except domestic and export reporting available. We are of the opinion that the DRP has made observations on the functionality of the company. Therefore we consider it appropriate to restore this issue to the file of TPO for verification and examination.
(vi) Excellent Technologies Pvt. Ltd. : The TPO has rejected this comparable as P & L Account is not available in the public domain and the DRP has confirmed the observations. Before us, the learned Authorised Representative relied page 1677 of Paper Book disclosed the financial summary of business for the relevant year. As this information is available, we consider it proper to restore this comparable to the file of TPO for examination and verification.
(vii) Celstream Technologies Limited – The TPO and DRP has rejected the comparable as profit and loss account is not available in public domain and the learned Authorised Representative referred to page 1755 to 1786 of Paper Book where the details of profit and loss account and Annual Report of the company are filed. Since the financial statements are available, we restore this issue to the file of the TPO to consider the financial statements, profit and loss account and Director’s Report. Accordingly, we restore the comparable to the file of TPO for verification of the financial statements.
8. The learned Authorised Representative made submissions in respect of exclusion of three comparables in the ITES segment and substantiated with chart and Paper Book.
(i) Infosys BPO Limited – The comparable is functionally dissimilar as it is engaged in provision of Integrated IT and end to end business process, outsourcing solutions and has high brand value and also made significant investment creating intangibles and made several IPs. The comparable also engaged in cloud based services as e-dictionary. The learned Authorised Representative supported his stand relying on the decisions of CGI Information Systems & Management Consultants (P) Ltd. Vs. ACIT 94 taxman.com 97 and PCIT Vs. Saxo India P. Ltd. on the constitution. We found that the co-ordinate Bench of Tribunal in the case of Ocwen Financial Solutions Pvt. Ltd. Vs. JCIT (2019) 108 taxman.com 306 where at paras 7 to 7.41 and dealt on comparable Infosys BPO Ltd. at para 7.4.1 and held as under :
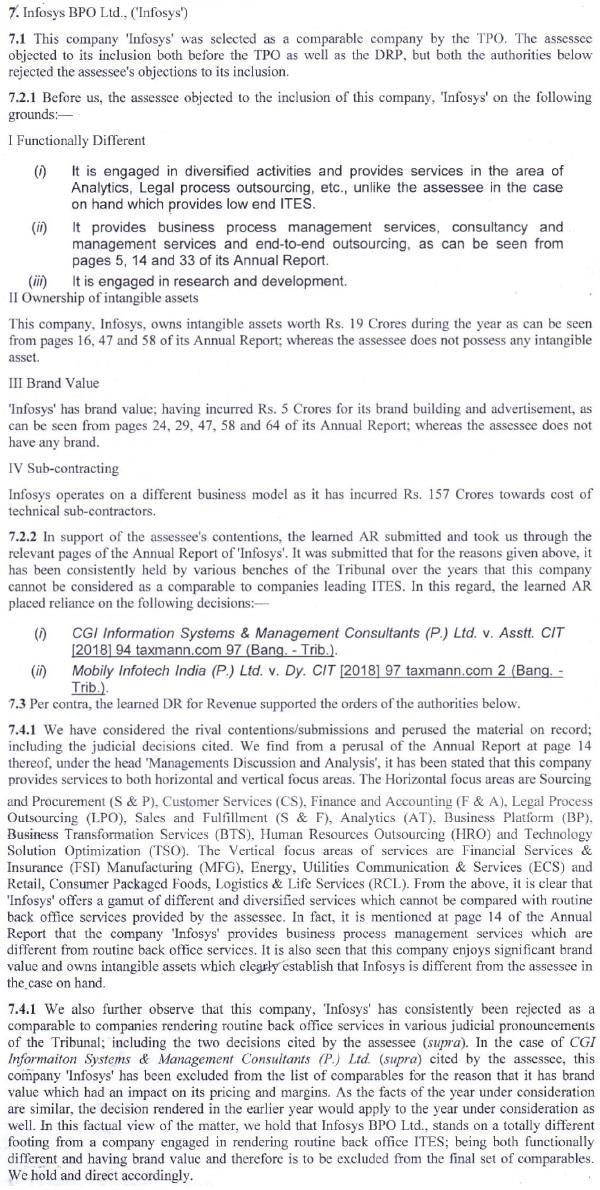
We find the judicial decisions, applicable for the Assessment Year 2014-15 and based on the observations of the co-ordinate Bench, we consider the company Infosys BPO Limited comparable has to be excluded and accordingly direct the TPO to exclude this company form the final list of comparables.
(ii) E-Clerx Services Limited has a margin of 70.26% and engaged in both rendering KPO and BPO services and no segmental information is available and the company has acquired entire share holding of Agilyst Inc. The company was excluded for the Assessment Year 2014-15 in the case of Hyundai Motor India Engineering Pvt. Ltd. Vs. ACIT 109 taxmann.com 429 at para 32 which read as under :
“Thus, on a comparison of the functions of the assessee and other companies reproduced above, we find that E-Clerx Ltd is not only into ITeS services, but is also rendering KPO services and therefore, it cannot be compared to the assessee. In the decisions of the ITAT where it has been held to be a comparable to the assessee, we find that ITAT has held that the services provided by the assessee company and E-Clerx Ltd. are similar and that the extraordinary event of winding up of the subsidiary company has not been proved to have any bearing on the assessee’s profits and that super Normal profit may not be a basis for exclusion of this company. However, we find that the co-ordinate Benches of the Tribunal in the Revenue Officers have not brought out functions which are similar to both the companies. Further, we are of the opinion that the decisions of the ITAT for the A.Y 2011-12 to 2012-13. Therefore, we are of the opinion that these decisions cannot exactly be binding on this Tribunal for the relevant A.Y. where the AO/TPO have considered the assessee as an IT service provider and not as a KPO. Further, as pointed out by the ld counsel for the assessee, The TPO himself has not taken E-Clerx Ltd as a comparable for the A.Y 2013-14. Therefore, we direct the TPO/AO to exclude this company from the final list of comparables to the assessee.”
We found the decision of the co-ordinate Bench of Tribunal where the said comparable is in KPO services and accordingly we direct the TPO to exclude the comparable from the final list of comparables for determination of ALP.
(iii) Cross Domain Solutions Pvt. Ltd., the company margin is 21.07% and has to be excluded as the company is providing value based quality services in the fields of HF, Finance, Administration, tax process etc and falls within the ambit of KPO services and dissimilar to ITES. The KPO service provider cannot be compared to the ITES provider and has to be excluded. The company was excluded in the co-ordinate Bench decision in the case of Symphony Marketing Solutions India Pvt. Ltd. Vs. ITO 38 Taxmann.com 55 at paras 18 & 19 held as under :
18. This company was considered as a comparable and listed at Sl.No.8 of the comparables chosen by the TPO. It is the stand of the assessee that this company is not functionally comparable. As observed in the case of Coral Hubs Ltd., the TPO rejected the plea of the assessee on the basis of a non-existent TP order passed for the A.Y. 2007-08. It is seen that the business profile of this company is re-engineered payroll service. This company is also engaged in the development of information systems. These activities are totally different from the activities of the assessee which perform very limited/low end functions back office services. The review and business functions of Cross Domain is as follows:-
“With a decade of experience in Payroll Outsourcing, Crossdomain has created a re-engineered payroll service EFFIPAY – that processes and delivers accurate payroll to clients with headcount up to 1000 employees in just 4 hours*. With Effipay Lite and Effipay Lite Plus, our bouquet of services cover end to end payroll, retrials, reimbursement, tax proof verifications upto issue of Form 16 for employees of our clients across different industry verticals. Our processes are highly scalable and provide end to end payroll solutions to clients with headcount ranging from 5 to 65,000.”
“Crossdomain’s IT knowledge and domain competence has provided the edge to develop information systems to implement process innovation and continuously increase efficiency and turn-around-time for business critical processes.”
Source: http://www.cross-domain.com
As can be seen from the above, the business of Cross Domain ranges from high end KPO services, development of product suites and routine low end ITES service. However, there is no bifurcation available for such verticals of services. Therefore the assessee contends that Cross Domain cannot be compared to a routine ITES service provider.
19. We are of the view that in the absence of any reasons given to the contrary either by the TPO or DRP for regarding this company as a comparable, this company should be excluded from the list of comparables, accepting the plea of the Assessee. We hold accordingly.”
Also in the case of PCIT Vs. BNY Mellon International Operations (India) (P.) Ltd., 93 taxmann.com 363 (Bom) the Hon’ble Bombay High Court has held the comparable Cross Domain Solutions Pvt. Ltd. is in the nature of KPO and observed at paras 3 to 8 as under :
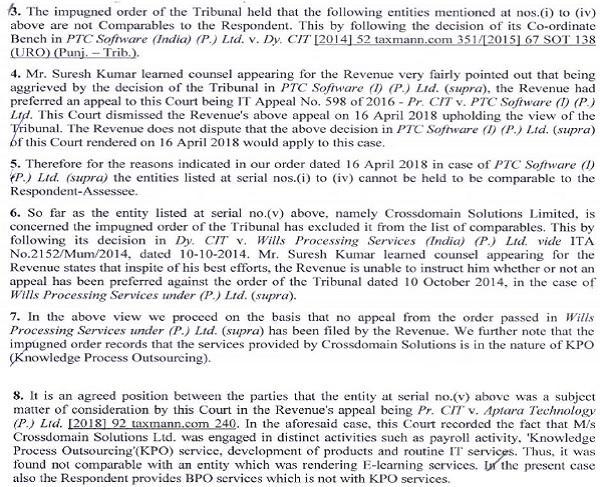
Further the learned Authorised Representative substantiated his argument with Annual Report of comparable and we consider it proper to direct the TPO to exclude the comparable from the list of comparables for determination of ALP.
9. The learned Authorised Representative argued for inclusion of three comparables in ITES segment.
(i) Jindal Intelcom Ltd., margin is 11.86% and the company was rejected by TPO. The assessee sought for inclusion. But the TPO observed that it is dissimilar and is engaged in call centre services and DRP has confirmed the TPO’s rejection. The DRP has observed that it is engaged in IT and ITES services and no segmental reporting is available. The learned Authorised Representative supported with judicial decision in the case of CGI Information Systems & Management Consultants (P.) Ltd. Vs. ACIT 94 taxmann.com 97 (Bang. Trib.) and we found the co-ordinate Bench decision for the Asst. Year 2014-15 in the case of Ocean Financial Solutions Pvt. Ltd. Vs. JCIT (supra) held at paras 12.1 to 12.4.1 as under :
12. Jindal Intellicom Ltd., (‘Jindal’)
12.1 This company, ‘Jindal’ was proposed by the assessee before the TPO as an additional comparable for inclusion in the final set of comparables. The TPO, however, rejected the assessee’s proposal on the grounds that this company ‘Jindal’ is engaged in providing services of a call centre in the overseas and domestic market; export of call centre services forming a major part of its business activities it was functionally different from the assessee and further on account of non-availability of segmental data. The DRP concurred with the findings of the TPO; holding that this company, ‘Jindal’, is engaged in both software development services and ITES and therefore it is difficult to treat this company as functionally comparable to the assessee in the case on hand.
12.2 Before us, it was submitted by the learned AR that this company, ‘Jindal’, is functionally comparable to the assessee in the case on hand and passes all the filters applied by the TPO. According to the learned AR, the TPO himself had selected this company, ‘Jindal’ as a comparable in the earlier Assessment Years 2011-12 and 2012-13 and also in the subsequent Assessment Year 2015-16 and as the facts in the year under consideration are similar, there is no good reason to exclude this company from the final set of comparables in this year. In support of the claim that this company ‘Jindal’ was functionally comparable to the assessee in the case on hand, the learned AR placed reliance on the decision in the case of CGI Information Systems & Management Consultants (P.) Ltd. (supra), wherein this company ‘Jindal’ was held as comparable to companies rendering ITES.
12.3 Per contra, the learned DR for Revenue supported the orders of the TPO/DRP in not including this company ‘Jindal’ in the final set of comparables.
12.4.1 We have considered the rival contentions/submissions put forth and perused the material on record. We have also perused the Annual Report of this company, ‘Jindal’; which is placed at pages 498 to 975 of the paper book. At page 130 of the Annual Report (i.e., page 627 of the paper book), it is mentioned that the company is engaged in providing call centre services, both in the overseas and domestic market; export of call centre services forming a major part of its business activities. In these circumstances, the observation of the DRP that this company ‘Jindal’ is engaged in software development services and ITES and segmental information is not available is not a factually correct observation; as borne out from the Annual Report of this company. Further, at page 160 of the Annual Report (i.e., page 657 of the paper book), it is seen that the segmental data of domestic and international segments of operation are given; thereby rendering the observations of the TPO is factually incorrect.
We follow the co-ordinate Bench decision and the information envisaged by the ld. AR in the Annual Report and direct the TPO to include the comparable for determination of ALP.
(ii) Informed Technologies Limited, which has the margin of 7.11% whereas the TPO has applied the filter, the company’s ITES services are less than 75% of their total operating revenues. The company passes the filter, as its operating revenue is from ITES. We found that this issue was considered by the co-ordinate Bench in the case of Ocwen Financial Solutions Pvt. Ltd. Vs. JCIT (supra) at para 10.4.1 held as under :
10.4.1 We have considered the rival submissions and carefully perused the material on record. On a perusal of the Annual Report of this company ‘Informed’, it is seen that at page 12 thereof it is stated that this company is engaged in and operating as an ITES provider. A perusal of the TPO’s order also indicates that the TPO has not disputed that this company is functionally comparable to the assessee in the case on hand; which is rendering back office ITES. From a perusal of the profit and loss account at page 30 of the Annual Report of ‘Informed’ it is seen that the total revenue is shown as Rs. 3,81,38,665/- and ‘other income’ of Rs. 1,22,85,303/-. As can be seen from Schedule 19 on page 40 of the Annual Report, the ‘other income’ comprises of non-operating income, interest, dividend, sale of current investments and miscellaneous income and evidently these incomes cannot be considered as operating income. The percentage of 67.7% worked out by the TPO is after considering these “other income” as service income; which is factually incorrect. It is evident from a perusal of the profit and loss account of ‘Informed’ that the service income is Rs. 2,58,53,362/- which is entirely the revenue from operations and therefore in our considered view, the service income filter of 75% of service income to be from ITES as applied by the TPO, is satisfied in this case. In view of this factual finding rendered in the matter, we hold that this company ‘Informed Technologies Ltd.’, satisfies the service income filter and is therefore to be included in the final set of comparables. We hold and direct the AO/TPO accordingly.
We follow the co-ordinate Bench decision and direct the TPO to include comparable for determination of ALP.
(iii) Accentia Technologies Limited, the TPO has rejected the comparable and DRP has upheld the exclusion of comparable altogether on a new basis that the company failed the RPT filter. The DRP has observed that the RPT is more than 25% therefore it cannot be comparable. Considering the facts and circumstances and material on hand, we consider it proper to restore this issue to the file of the TPO for verification and examination.
10. Further, the learned Authorised Representative argued on Ground of Appeal No.4C and 4D in respect of Revenue not considering the foreign exchange gain and Working Capital Adjustment. Whereas the TP Adjustment was made to non-AE transactions and foreign exchange gain in ITES has to be considered. Considering these facts, we restore this disputed issue to the file of the TPO to consider the assessee’s submissions and facts envisaged for determination of ALP. Accordingly, Ground of appeal of the assessee is allowed for statistical purposes.
11. Whereas the charging of interest under Sections 234B & 234C are consequential in nature and we direct accordingly.
12. In the result, the assessee’s appeal is partly allowed for statistical purposes.
Order pronounced in the open court on 18th Dec., 2019.







